


Carlsberg brewery closure puts UK ale footprint in focus
Carlsberg (CPSE:CARL B) has moved to shut its Marston's brewery in Burton upon Trent, along with a key UK logistics site, after ongoing weakness in the traditional ale market.
The brewer plans to keep brands such as Hobgoblin, McEwan's and Brooklyn within its line up, while seeking new owners for other cask and regional ales that no longer fit its UK production setup.
Carlsberg shares trade at DKK872.4, with a 1-day share price return of 1.28% and a 7-day gain of 2.42%. Momentum has faded over the last three months, while the 1-year total shareholder return of 20.28% contrasts with a more muted 5-year total shareholder return of 7.14%.
Scan how other beverage players are repositioning their footprints by checking our curated list of list of solid balance sheet and fundamentals (207 results) as potential peers to Carlsberg's UK rethink.
Carlsberg is trimming its UK ale footprint while the share price sits well below some intrinsic and analyst estimates. Does that mix of operational reset and valuation still stack up in favour of buyers?
Most Popular Narrative: 16.9% Undervalued
Carlsberg last closed at DKK872.4, while the most followed narrative pegs fair value around DKK1,050, which frames today's price as a discount that hinges on how investors view the shift toward a broader premium beverage mix.
Carlsberg will gradually evolve from a traditional beer company into a broader premium beverage group, with beer, soft drinks and alcohol-free beverages all contributing to growth. The acquisition of Britvic strengthens Carlsberg’s exposure to soft drinks and gives the group a more balanced portfolio at a time when beer volumes are under pressure in some markets. Premium beer, alcohol-free beer and soft drinks should support modest organic revenue growth, while cost discipline, integration synergies and operating leverage should allow operating profit to grow slightly faster than revenue. I expect Carlsberg to remain a defensive, cash-generative consumer staples company rather than a high-growth stock. My base case is that adjusted EPS grows from about DKK 61 in 2025 to the mid-to-high DKK 60s over the next few years, supported by Britvic synergies, premiumisation, Asia growth and continued dividend discipline. Using a fair multiple of around 16 to 17 times normalised earnings. This assumes moderate earnings growth, no major deterioration in consumer demand, gradual deleveraging and continued dividend growth.
See why 4 investors see Carlsberg as 17% undervalued.
According to NordicWolf, that fair value view builds on Carlsberg's profile as a defensive, cash generative beverage group, rather than a fast growing stock, with Britvic integration, premium offerings and Asia exposure doing much of the heavy lifting in the thesis.
That narrative sits alongside Simply Wall St's own estimate that the shares trade about 59.8% below an intrinsic value based on future cash flows, and a DKK2,169.41 future cash flow value, which underlines how much of the debate is about how conservative or optimistic investors want to be about those long term assumptions.
Analysts currently point to a DKK1,049.18 price target, roughly 20.3% above the latest close, so anyone tracking Carlsberg now is effectively weighing a user driven fair value around DKK1,050, a higher DCF based value and a lower but still higher than spot broker consensus, all while the stock carries a DKK120.6b market cap supported by DKK90,293m of revenue and DKK6,395m of net income.
Result: Fair Value of DKK1,050 (UNDERVALUED)
Still, that storyline around Carlsberg could be challenged if the Britvic integration proves more complicated than expected or if beer and soft drink demand weakens further.
Find out about the key risks to this Carlsberg narrative.
Another View: Carlsberg on Earnings Multiples
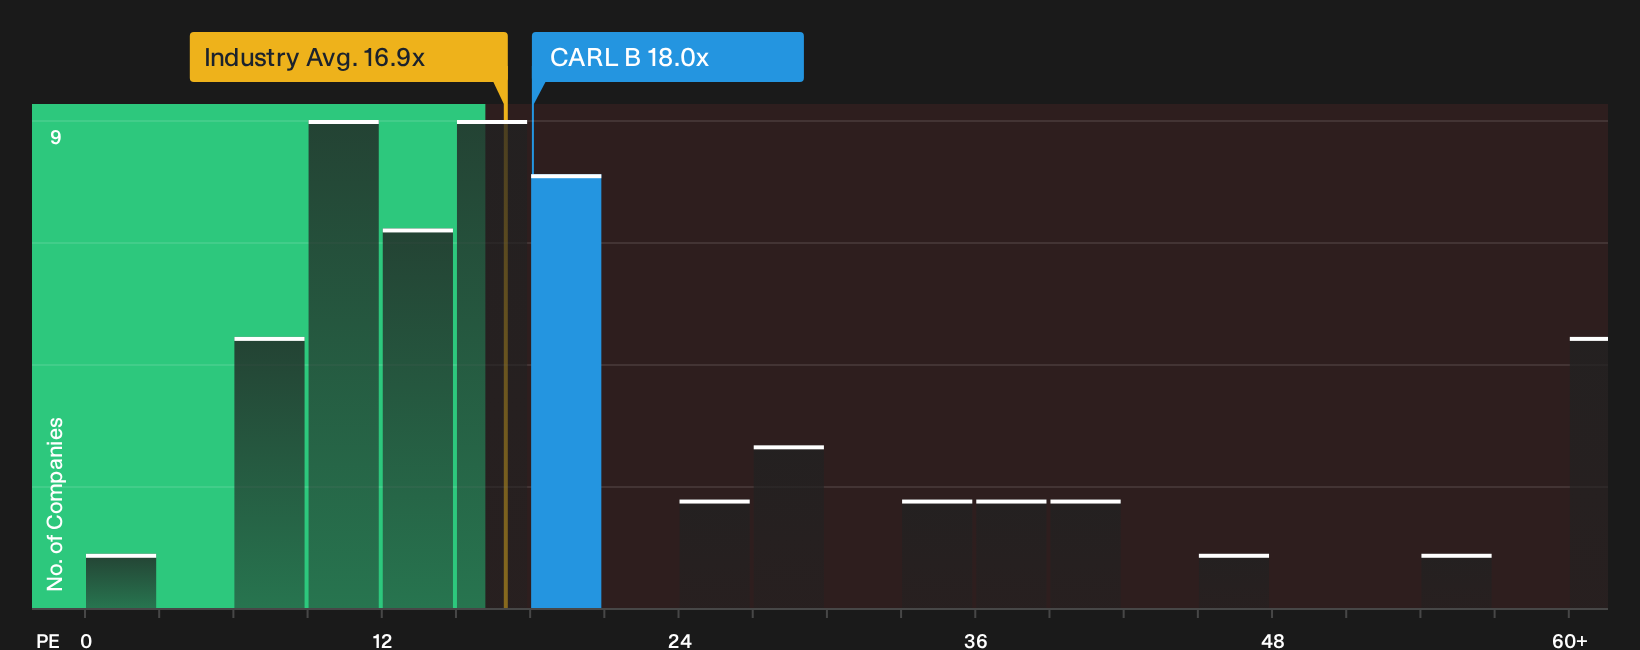
Carlsberg might look inexpensive based on some fair value estimates. However, its P/E of 18x is slightly higher than the European beverage group average of 17.2x, the peer average of 17.7x and an internal fair ratio of 17.2x. That premium reflects perceived quality, which raises the question of how much mispricing may still exist for investors.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Carlsberg's valuation and UK reset have probably raised as many questions as answers, so act while the data is fresh and stress test the thesis against the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Carlsberg?
Carlsberg gives you one angle on beverages, but you widen your edge by lining it up against other high quality businesses with different risk and return profiles.
- Spot potential bargains early by checking companies that combine strong fundamentals with room for a re‑rating through the 618 high quality undiscovered gems.
- Prioritise resilience by filtering for businesses that carry healthier finances and steady operations using the 226 resilient stocks with low risk scores.
- Target value with quality by scanning a curated pool of underpriced yet fundamentally sound opportunities via the 186 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com