


What Sparked The Latest Move In Rocket Companies Stock
Rocket Companies (RKT) just delivered its most profitable quarter in four years, with revenue up 92.9% year on year, yet the share price dropped 11.6% after the earnings release.
That sharp post earnings drop fits into a wider losing streak for Rocket Companies, with the share price down 18.63% over the past month and 42.45% year to date, even though the 3 year total shareholder return remains positive at 47.61%.
Contrast the recent pullback in Rocket Companies with other mortgage and finance players by scanning our hand picked list of solid balance sheet and fundamentals (25 results) that have navigated recent volatility more steadily.
Rocket Companies now trades well below the average analyst target and at a discount to one estimate of fair value. Is that gap skepticism that proves sensible, or hesitation that misprices the stock after this earnings drop?
Most Popular Narrative: 34% Undervalued
Rocket Companies closed at $11.44, while the most followed narrative framework points to a fair value of about $17.27 using an 8.94% discount rate. That gap sets up a story where the recent price drop clashes with a model that leans heavily on recurring revenue, integrations and cost savings.
The move to a revenue mix where more than 70% comes from servicing, purchase, home equity, personal loans, Redfin and Rocket Money subscriptions shifts Rocket Companies further away from pure rate driven refinance exposure and can support a steadier base for revenue and earnings.
The build out of AI tools that cut prospecting time, raise conversion and support roughly US$300b of fixed origination capacity with fewer production staff gives Rocket Companies room to add volume without matching growth in expenses, which can support net margins.
See why 35 investors see Rocket Companies as 34% undervalued.
Result: Fair Value of $17.27 (UNDERVALUED)
Still, the bullish narrative around Rocket Companies can unravel if mortgage rates stay elevated and keep purchase and refinance volumes under pressure, or if Redfin and Mr. Cooper integrations fail to deliver the expected cross sell and cost savings that underpin the current fair value story.
Find out about the key risks to this Rocket Companies narrative.
Another Take On Rocket Companies Valuation
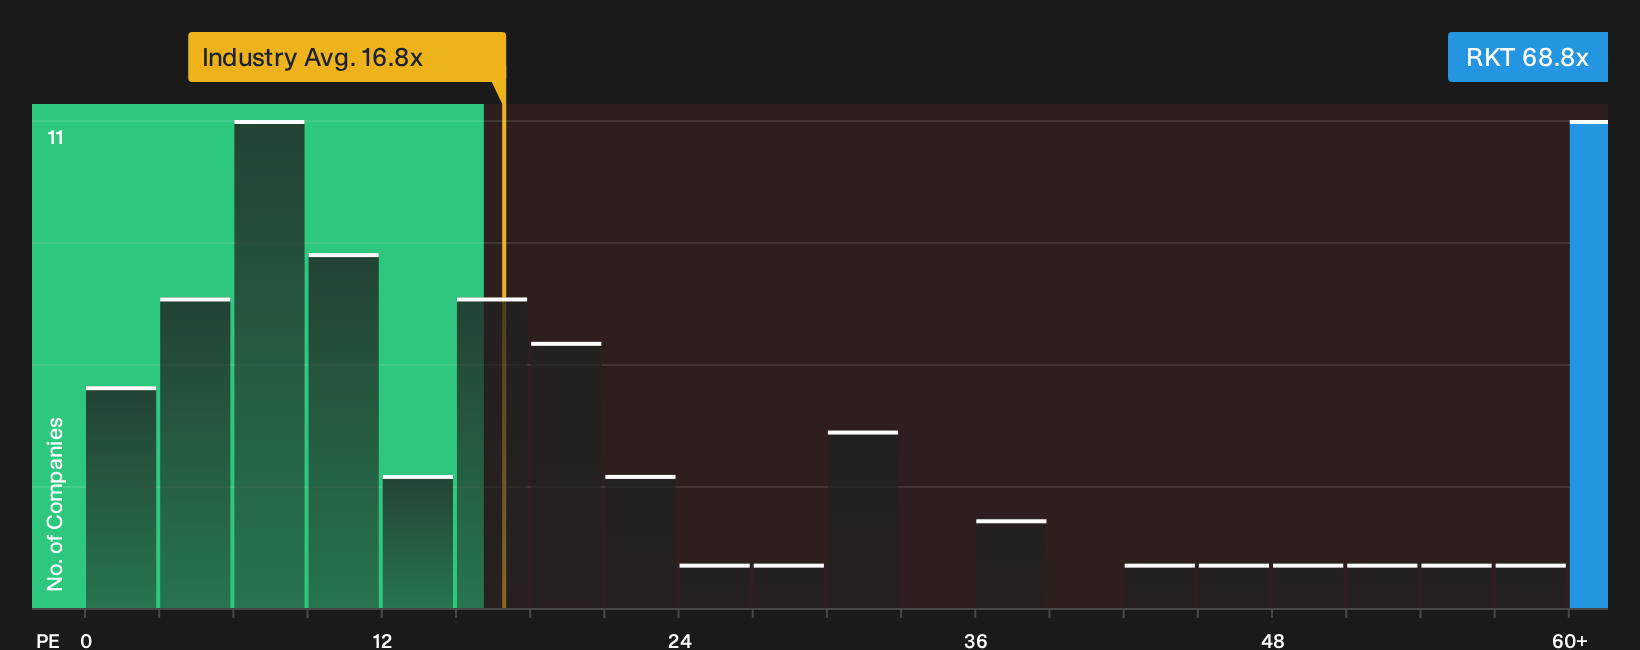
The story looks very different once the focus shifts from discounted cash flows to earnings multiples. Rocket Companies trades on a P/E of 68.8x, which is far above the US Diversified Financial industry on 16.9x and the peer average on 31.5x. It also sits well above the 26.3x fair ratio that the market could move toward. This raises the question of whether today’s price leaves much room for error if the bullish narrative stalls.
For a closer look at how those earnings multiples stack up against sector peers and that fair ratio, check the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Rocket Companies so far. Use the same data, move quickly while sentiment is unsettled, and weigh both the bright spots and red flags with the 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Rocket Companies?
If Rocket Companies has your attention, do not stop here. Use fresh ideas from powerful stock screens to spot opportunities before attention fully shifts their way.
- Target potential mispricing by scanning a focused group of quality companies using the 29 high quality undervalued stocks.
- Prioritize stability by reviewing a curated pool of steadier businesses through the 31 resilient stocks with low risk scores.
- Hunt for future leaders early by checking companies with strong fundamentals in the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com