


Intershop Holding (SWX:ISN) has drawn fresh attention after its recent share price moves, with the stock last closing at CHF 154. Investors are now weighing that valuation against recent return trends.
Recent trading paints a mixed picture for Intershop Holding, with the 1-day share price return of 0.79% and 7-day gain of 1.32% set against a 90-day share price decline of 11.39%. At the same time, long-term total shareholder returns of 41.44% over three years and 67.67% over five years point to momentum that has been stronger over time than in the most recent quarter.
Scan beyond Intershop Holding and identify other real estate and asset focused plays with resilient profiles using our curated list of solid balance sheet and fundamentals (207 results).
For Intershop Holding, the latest share price uptick sits against weaker recent returns and stronger multi year gains, so is this move about the real estate portfolio or just changing sentiment around the stock?
Price-to-Earnings of 13.5x: Is it justified?
Intershop Holding trades on a P/E of 13.5x, which leaves the CHF 154 share price sitting slightly above both peer and industry averages for Swiss real estate stocks.
The P/E ratio compares the current share price with earnings per share, so it reflects how much investors are paying for each unit of profit. For a property owner such as Intershop Holding, which reported high profit margins of 87% but also a large one off gain of CHF 36.0m, this measure can be sensitive to short term swings in earnings quality.
That 13.5x multiple is described as a discount to the broader Swiss market on 20x. However, it is marginally higher than both the Swiss real estate industry average of 13.3x and the immediate peer group on 13x. The premium to sector and peer levels suggests investors are paying a slightly richer price for each franc of earnings. At the same time, the comparison to an estimated fair P/E of 15.4x points to some room where the market could shift if sentiment around Intershop Holding changes.
Explore the SWS fair ratio for Intershop Holding.
Result: Price-to-Earnings of 13.5x (ABOUT RIGHT)
Still, the narrative around Intershop Holding can shift quickly if earnings soften after the recent one off gain, or if Swiss property valuations come under pressure.
Find out about the key risks to this Intershop Holding narrative.
Another View on Intershop Holding's Value
While the 13.5x P/E for Intershop Holding looks roughly in line with the real estate pack, our DCF model lines up differently. On that approach, the shares at around CHF 154 trade slightly above an estimated future cash flow value of CHF 151.12, which nudges the story toward mild overvaluation rather than comfort zone. For anyone weighing P/E against cash flows, that contrast raises a simple question: Which signal feels more reliable for a property owner with recent one off gains and forecast earnings declines?
Look into how the SWS DCF model arrives at its fair value.
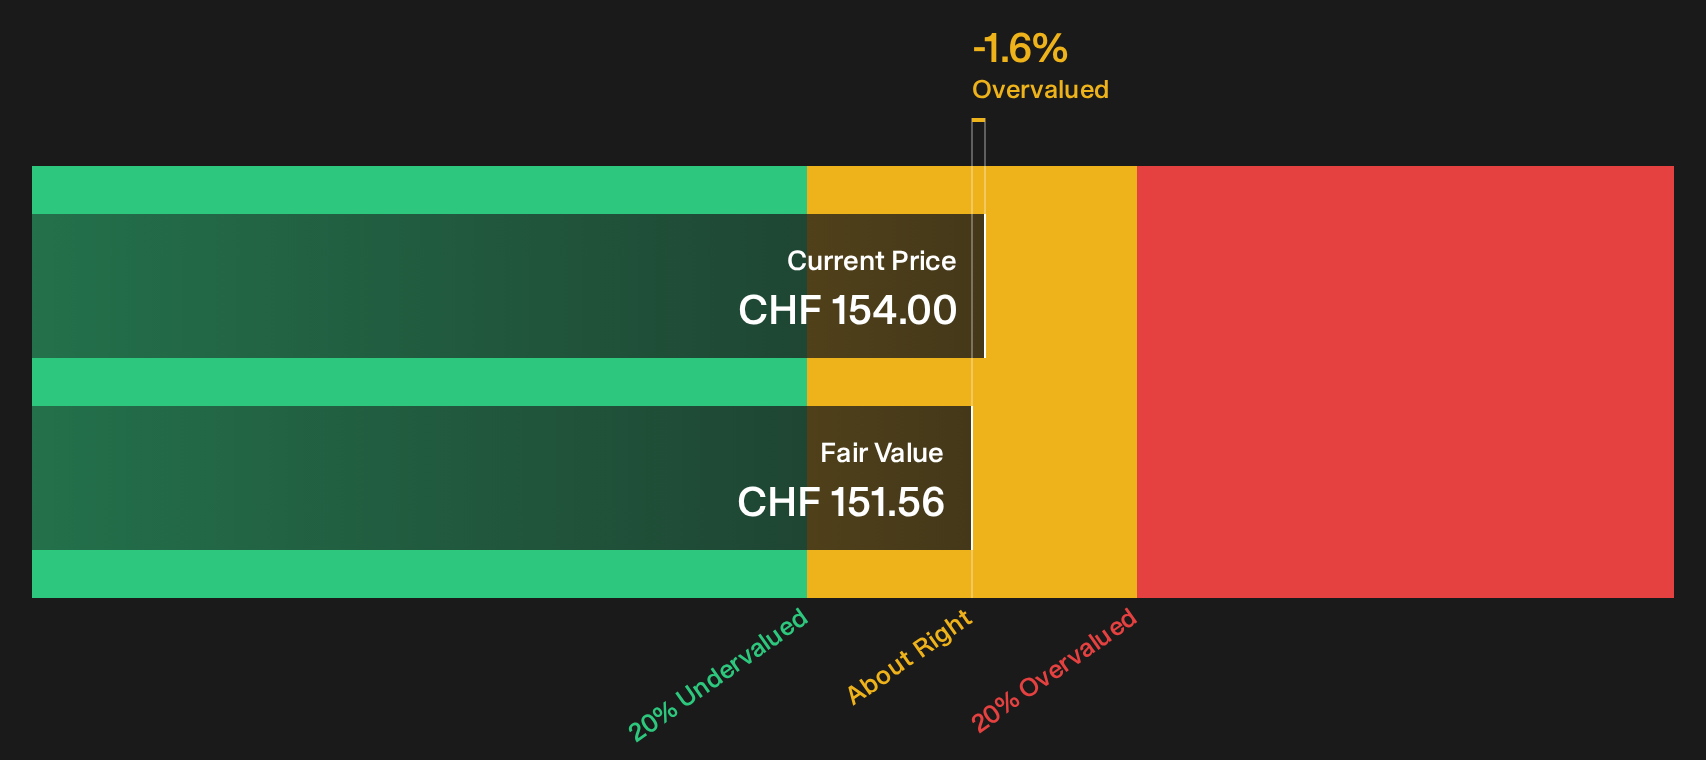
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Intershop Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or emerging opportunity for Intershop Holding investors. If you want to move quickly, check the balance of risks and potential upsides yourself with the 1 key reward and 5 important warning signs.
Looking for more Intershop Holding sized ideas?
If Intershop Holding has you reassessing where your capital works hardest, do not stop here. The next opportunity might already be on the screen.
- Spot potential value candidates early by scanning our hand picked list of 619 high quality undiscovered gems.
- Prioritise resilience and focus on capital preservation by checking companies in the 225 resilient stocks with low risk scores.
- Target quality at a sensible entry point by reviewing the 184 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com