


Weyerhaeuser (WY) is back in focus after signing a commercial partnership with TimberHP that gives the forestry group U.S. distribution rights for TimberHP’s wood fiber insulation across the lumber and building materials channel.
Recent price action has been tougher for Weyerhaeuser, with the share price down 19.3% over the past month and the year-to-date share price return declining 22%, while the 5 year total shareholder return is down 39%. This TimberHP deal arrives as sentiment is under pressure.
Scan how Weyerhaeuser compares with other beaten down building and materials plays by checking our hand picked list of solid balance sheet and fundamentals (25 results) before sentiment turns.
The recent slide raises a simple tension. Are investors marking Weyerhaeuser down because the core timber and wood products engine has changed, or has sentiment simply swung harder than the fundamentals justify as valuation resets?
Most Popular Narrative: 38% Undervalued
On the most followed view, Weyerhaeuser’s fair value of $29.91 sits well above the last close at $18.57. This puts the current slide against a backdrop of a business that analysts still model for steady revenue and earnings expansion.
The current valuation implies that the market is not fully pricing in the potential cash generation from Weyerhaeuser’s targeted 75 to 80% Adjusted FAD capital return framework, the higher EBITDA contribution from Strategic Land Solutions and Climate Solutions, and the expected earnings uplift from lumber supply tightening and new engineered products such as Monticello TimberStrand.
See why 24 investors see Weyerhaeuser as 38% undervalued.
Result: Fair Value of $29.91 (UNDERVALUED)
Still, the Weyerhaeuser narrative depends on housing demand improving from what management calls second gear, and on OSB economics recovering from recent loss making levels.
Find out about the key risks to this Weyerhaeuser narrative.
Another View: What Weyerhaeuser’s P/E Ratio Signals
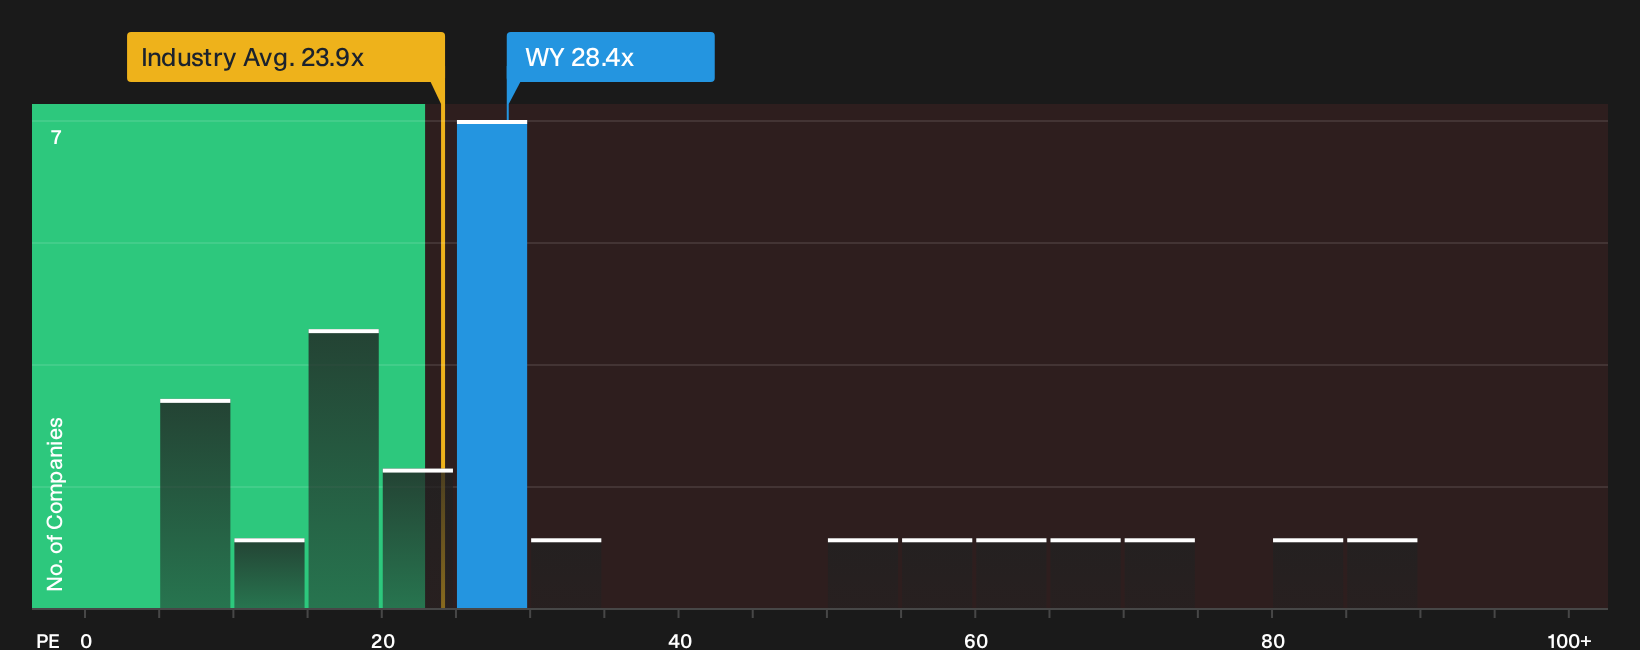
Zoom out from fair value models and the picture shifts. On a P/E of 28.4x, Weyerhaeuser trades above the North American Specialized REITs average of 24x, yet below its own fair ratio of 38.5x. That mix points to real valuation risk as well as opportunity. Which side do you think the market is pricing in?
To see how that trade off looks when you line up Weyerhaeuser against peers and its own fair ratio, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Weyerhaeuser is clearly divided right now, so move quickly, review the underlying data yourself, and weigh both the 3 key rewards and 3 important warning signs.
Looking for more Weyerhaeuser sized opportunities?
If Weyerhaeuser has you rethinking your watchlist, use this pullback as a prompt to widen your search and stress test your next moves.
- Target stability first by scanning companies with strong cash positions and cleaner finances through our 31 resilient stocks with low risk scores so short term swings feel less disruptive.
- Chase value where quality meets a discounted tag by reviewing the 29 high quality undervalued stocks that might line up better with your risk and return expectations.
- Spot potential future favorites before they hit the spotlight by running through the 20 high quality undiscovered gems and get in ahead of wider market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com