


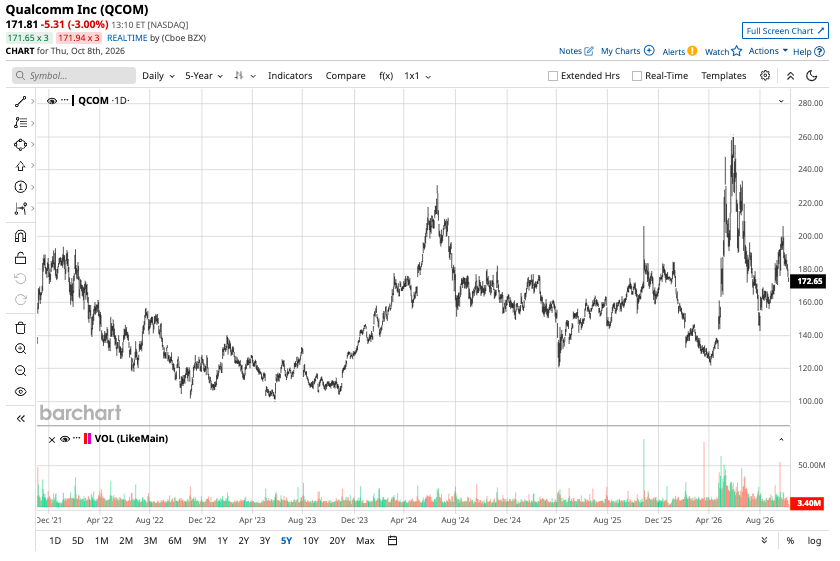
Qualcomm (QCOM) now appears to be very well-positioned to benefit from the proliferation of agentic artificial intelligence (AI) in smartphones and its new agreement with Amazon (AMZN). Moreover, the valuation of QCOM stock is quite low considering the powerful positive catalysts working for the company.
On the other hand, Qualcomm's positive game changers may take two or three years to move the needle for QCOM stock. In the near-to-medium term, volatility in the handset market also seems poised to negatively impact the company's top and bottom lines.
As a result, although shares of QCOM look like they will trade much higher within three to four years, this name seems best-suited for long-term, patient investors. It may be best to allocate only a small percentage of portfolios to Qualcomm stock right now. Let's take a closer look at why.
Qualcomm's Agentic AI and Amazon Accelerators
On Sept. 22, Qualcomm introduced two new processors — the Snapdragon 8 Elite Extreme Gen 6 and Snapdragon 8 Elite Gen 6 — designed “to power the agentic AI age and the next generation of premium mobile experiences.” The chipmaker reported that these chips can enable "agentic AI experiences that are immediate, personal, and adaptive." The offerings should help enable increased automation of tasks, boost memory on smartphones based on individual usage, and facilitate enhanced AI-agent personalization.
With many smartphone makers and software companies urgently looking to add agentic AI to handsets, this technology is likely to be incorporated into a high percentage of smartphones in the medium-to-long term. According to Counterpoint Research, “Full agentic AI on the smartphone requires robust on-device processing for lower latency, enhanced user privacy, cost efficiency and offline functionality.” So, demand for Qualcomm's chips is likely to be strong over the longer term. The fact that Samsung, one of the world's leading smartphone makers, already buys chips from Qualcomm may also help QCOM stock benefit meaningfully from the proliferation of agentic AI in handheld devices.
But that's not the only thing Qualcomm has going for it. In early September, Amazon agreed to a 10-year deal to buy up to $60 billion of Qualcomm's products and partner with the chipmaker on the development of hardware used in AI inference. Because this deal also gives Amazon warrants to buy up to 25 million shares of QCOM stock, Amazon is financially incentivized to buy Qualcomm's products rather than the products of competitors. In light of the rapid growth of Amazon's AI business, along with its partnerships with both Anthropic and OpenAI, the tech giant may need a large number of these products, too.
The Positive Drivers May Take Years to Materialize
When Qualcomm announced its new chips for agentic AI, the company named nine original equipment manufacturers (OEMs) and smartphone brands that had agreed to utilize the processors, but Samsung and Apple (AAPL) were not among those names. Apple has appeared to be backing away from Qualcomm over the last few years. Meanwhile, unless or until Samsung starts buying these new chips, they may not move the needle for Qualcomm stock a great deal.
As flash memory prices rise meaningfully and handset companies generally respond by raising prices, smartphone demand could potentially decline in the near-to-medium term as well. This latter potential scenario, in addition to hurting Qualcomm generally, could limit the extent to which it benefits from its new AI chips in particular.
Finally, Qualcomm did not raise its estimates for its current fiscal year or the upcoming fiscal year in the wake of the Amazon deal. Consequently, it's possible that the agreement will take a couple of years to meaningfully boost Qualcomm's financial results.
What Should You Think of QCOM Stock?
Shares of Qualcomm are changing hands at a trailing price-to-earnings (P/E) ratio of 20.4 times currently. In light of the company's positive catalysts, QCOM stock appears to be trading for quite cheap with some handset weakness baked in for the next year or two. While Qualcomm could experience some volatility over the next couple of years amid lower handset sales, its low valuation and longer-term catalysts should enable the stock to climb significantly in the next three to four years.
Overall, based on 33 analysts with coverage, QCOM stock has a consensus “Hold” rating on Wall Street.
On the date of publication, Larry Ramer had a position in: AMZN , AMZU . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.