


Dynagreen Environmental Protection Group (SEHK:1330) has drawn attention after a recent one day move of 2.37%, prompting investors to reassess how its waste-to-energy focus aligns with recent share performance.
Viewed over a longer stretch, Dynagreen Environmental Protection Group has a 90 day share price return of 17.18% and a year to date share price return of 15.83%, while the 1 year total shareholder return sits at 21.15%, pointing to momentum that has built gradually rather than in a straight line.
Scan beyond Dynagreen Environmental Protection Group and compare its momentum with a curated 182 high quality undervalued stocks that also pair recent strength with balance sheet support.
For Dynagreen Environmental Protection Group, that 2.37% jump can either read as a catch up to the underlying waste to energy business or as short term enthusiasm. Which picture do the current valuation markers support?
Price-to-Earnings of 10.5x: Is it justified?
On current numbers, Dynagreen Environmental Protection Group trades on a P/E of 10.5x, which leaves the HK$6.04 share price looking rich compared to both a modelled fair P/E and the immediate industry reference point.
The P/E multiple compares what investors are paying for each unit of earnings. For a waste to energy operator like Dynagreen Environmental Protection Group, this ratio becomes a shorthand for how the market weighs its earnings profile against listed peers in Hong Kong Commercial Services.
At 10.5x earnings, the stock carries a higher tag than the estimated fair P/E of 8.2x. This implies the market is attaching a premium to the current profit stream relative to the level a fair value model suggests it could settle towards. The same 10.5x also screens slightly above the Hong Kong Commercial Services average of 10x, putting Dynagreen Environmental Protection Group on the expensive side compared with the broader peer group.
Explore the SWS fair ratio for Dynagreen Environmental Protection Group.
Result: Price-to-Earnings of 10.5x (OVERVALUED)
Still, the story can break if Dynagreen Environmental Protection Group faces tighter waste regulations or slower project rollouts that weigh on revenue and earnings momentum.
Find out about the key risks to this Dynagreen Environmental Protection Group narrative.
Another View on Dynagreen Environmental Protection Group's Value
The P/E points to Dynagreen Environmental Protection Group as expensive, yet the SWS DCF model presents a very different picture. At HK$6.04, the stock is described as trading well below an estimated future cash flow value of HK$37.50, which frames it as heavily undervalued. Which signal should carry more weight for you: the earnings multiple or the cash flow model?
Look into how the SWS DCF model arrives at its fair value.
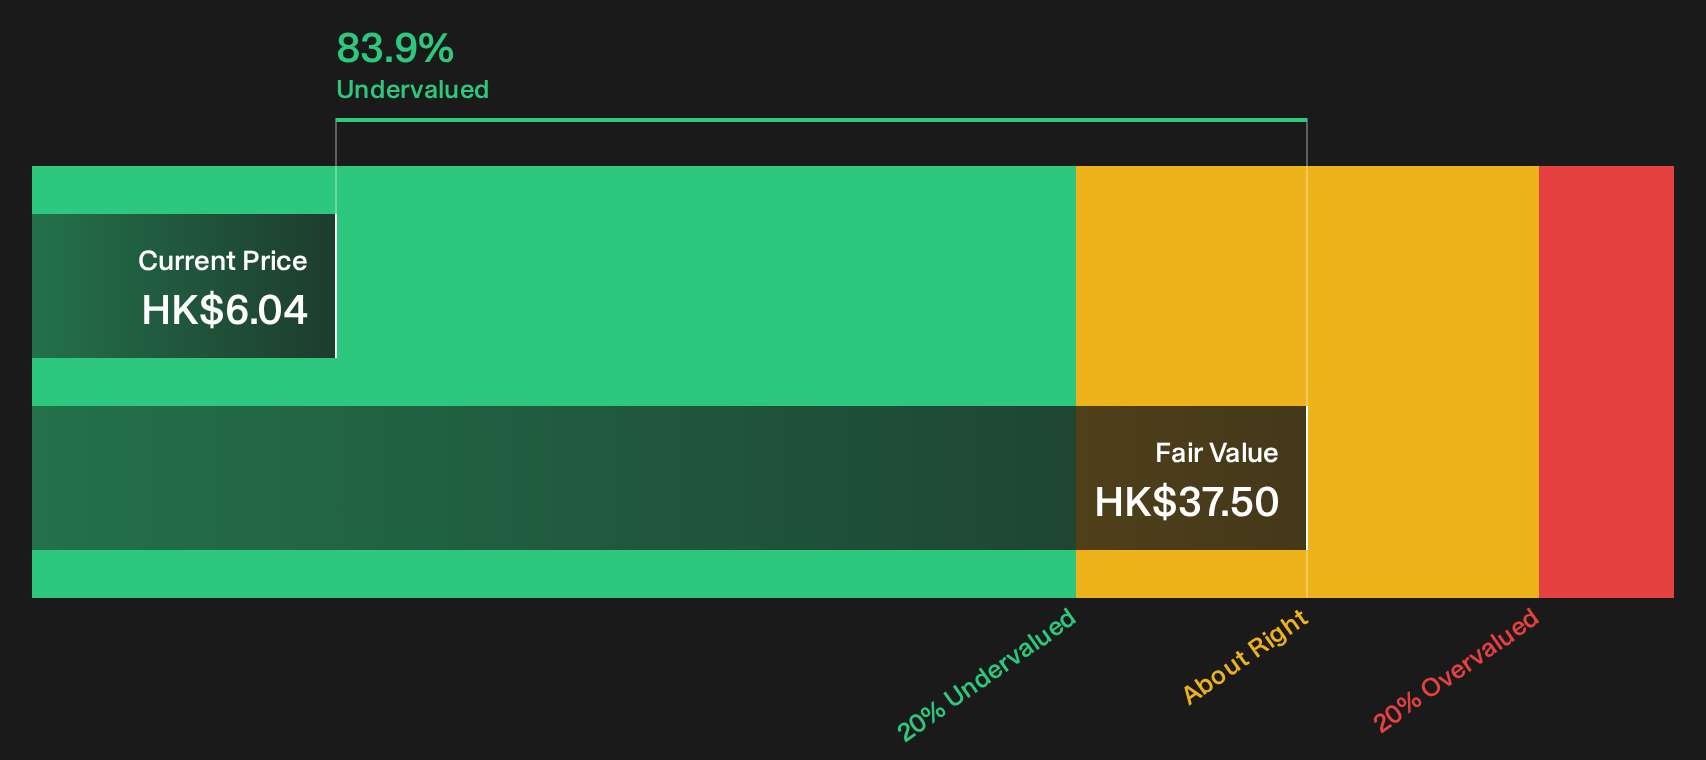
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dynagreen Environmental Protection Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Dynagreen Environmental Protection Group's value can feel confusing, so it may help to move quickly to weigh the data and refine your own view of the balance between risk and reward. To see the key points investors are considering on both sides, start with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Dynagreen Environmental Protection Group?
If Dynagreen Environmental Protection Group has sharpened your focus on valuation, do not stop here. Broaden your watchlist with fresh opportunities sourced from a data driven screener.
- Target value opportunities by reviewing companies that combine quality fundamentals with attractive pricing through the 182 high quality undervalued stocks.
- Prioritise resilience and capital preservation by scanning a 225 resilient stocks with low risk scores that highlights businesses with more defensive profiles.
- Spot fresh prospects before the crowd by running through a 619 high quality undiscovered gems built to surface quieter high quality stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com