


Eurozone cash markets have suddenly moved from financial footnote to front-page story, as expectations firm for another ECB rate hike and bond yields pull investor money in new directions. That shift creates potential openings and risks around money market and short-duration products that many investors still overlook. This article walks through 3 specific stocks exposed to this rate story and explains where the changing backdrop could help or hurt them.
The stocks highlighted below are only a small sample, as the full screen surfaced 12 more Eurozone cash and money market product providers with equally compelling narratives that are not covered here. To see the wider opportunity set, head straight into the Eurozone Short-Duration Cash & Money Market Product Providers screener to identify, filter, and analyze the Eurozone players that best fit your own highest conviction views.
Crédit Agricole (ENXTPA:ACA)
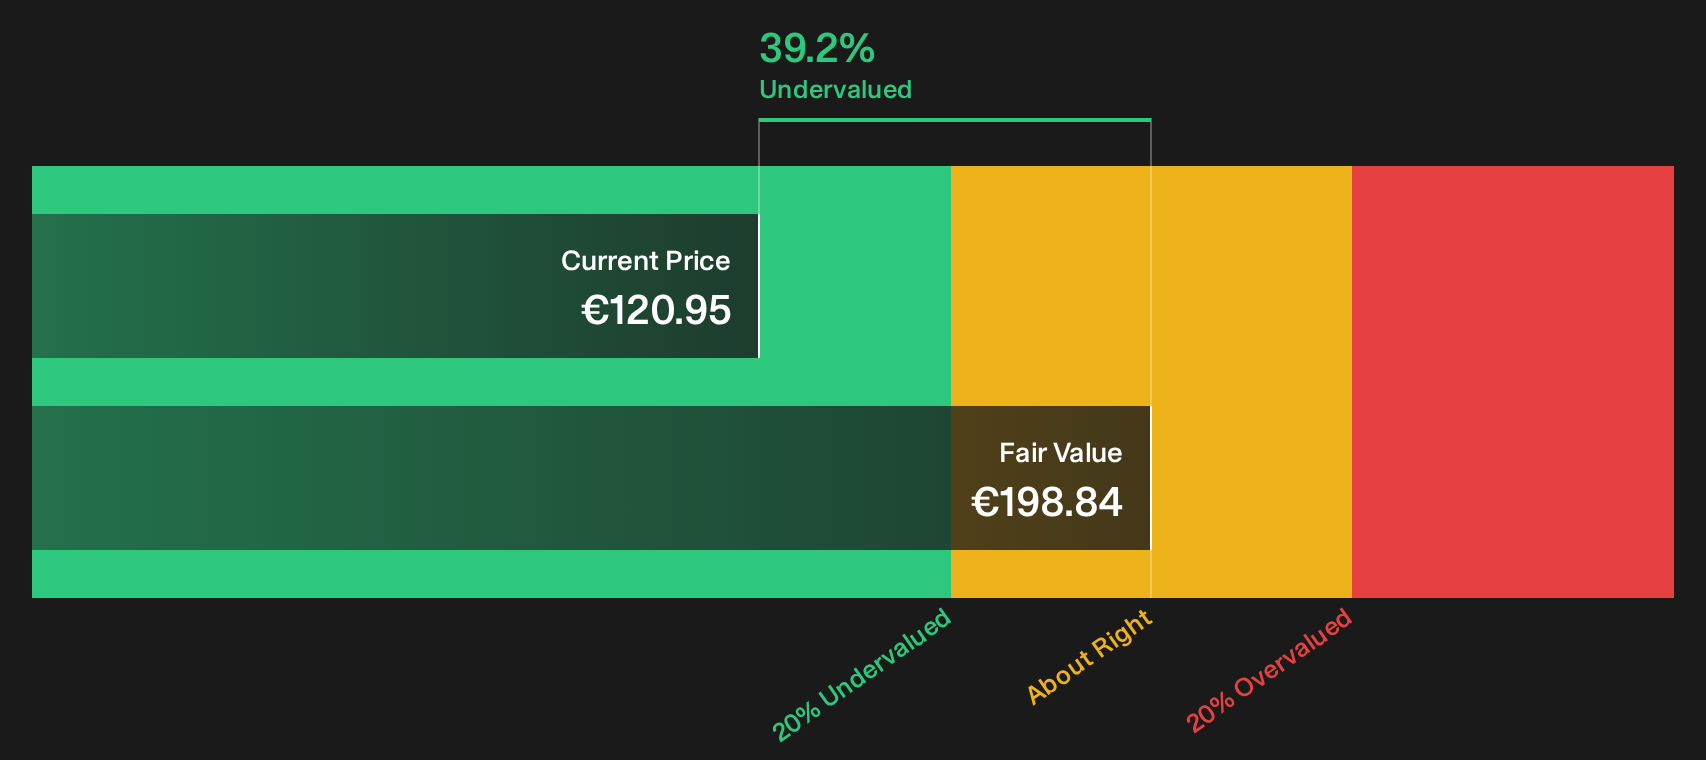
Crédit Agricole is one of the clearest plays in this screener on euro cash and liquidity, with a universal banking model that touches almost every corner of short-term savings, cash management, and treasury services across Europe.
Crédit Agricole S.A. runs a broad retail, corporate, insurance and asset management platform that naturally leans into euro cash and liquidity flows. Revenue is anchored in Asset Gathering at about €8.1b and Large Customers at roughly €8.7b, alongside French and international retail banking of about €3.7b each, on top of a €49.5b market cap.
"Expansion in savings and investment products across Europe, supported by record insurance premiums of €52b and asset management inflows of €88b in 2025, positions fee based businesses such as asset management, insurance and wealth management to further support revenue and fee income."
The real swing factor is how one quiet shift in funding and liquidity conditions feeds through to pricing power on those short-duration cash solutions.
As that pricing power story unfolds, the full narrative for Crédit Agricole shows how Crédit Agricole's euro cash engine could accelerate or stall as funding conditions evolve.

Van Lanschot Kempen (ENXTAM:VLK)
Van Lanschot Kempen taps directly into the euro cash theme by helping wealth clients park and shift large savings pools into short-term euro instruments. Its business model is closely linked to how attractive higher policy rates appear to cautious, yield-hungry investors.
"Acquisitions, digital platform investments, and a focus on ESG solutions enhance efficiency, strengthen margins, and attract high-net-worth clients for long-term growth."
What happens to those carefully built economics if one quiet pressure on client risk appetite starts to pull assets away from short-duration cash options?
Van Lanschot Kempen is a specialist wealth and investment manager focused on affluent and high net worth clients in the Netherlands and Belgium. It earns most of its €792 million revenue from Private Clients Netherlands at about €435 million, with additional contributions from Belgium at €157 million and investment management, and carries a market value of roughly €2.8b.
That quiet pressure on risk appetite is exactly what the full narrative for Van Lanschot Kempen unpacks, revealing how Van Lanschot Kempen could turn shifting client preferences into accelerating fee momentum.

KBC Group (ENXTBR:KBC)
KBC Group is one of the purest plays in this screener on euro cash, short-duration savings, and liquidity products, with a universal banking and asset management set up that channels client deposits and investment balances directly into money market and cash management solutions.
KBC Group runs an integrated banking, insurance, and asset management platform across Central Europe, with most of its income coming from Belgium at about €7.4b, followed by the Czech Republic at roughly €2.7b and other markets, and a market cap near €48.9b.
"If KBC’s equity beta normalizes toward 1.0 (pushing Cost of Equity to approximately 8.15%), both model outputs drop significantly below the bottom of their sensitivity ranges. Regulatory restrictions or capital preservation moves could disrupt dividend flows."
What happens to cash product margins if a single quiet shift in how the market prices KBC’s risk collides with those higher short euro rates?
That collision risk is exactly why the full narrative for KBC Group explores in detail how KBC Group’s cash engine, capital stack, and payout profile could decouple from headline rate moves.
Seeking Alternatives Before The Crowd?
Fresh ideas move first, and slow research often gets caught chasing momentum once prices start flying. Scan under the radar for now, while it matters, and act now.
- Spot resilient income streams as yields move by reviewing the curated 224 dividend fortresses before those payout stories stop looking cheap and patient capital locks them up.
- Track the next wave of infrastructure behind AI’s breakout phase through the focused 92 AI infrastructure stocks while these enablers are still priced like side characters, not lead roles.
- Position ahead of potential demand spikes by scanning the carefully filtered 16 top copper producer stocks before copper supply stories start driving headlines and late money chases the momentum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com