


Natural Resource Partners (NRP) has drawn fresh attention after recent trading left the units with an intrinsic discount of about 47% relative to one intrinsic value estimate, raising questions about how investors are pricing its mineral portfolio.
Recent trading in Natural Resource Partners has been mixed, with a 90-day share price return of 10.05% and a year to date share price gain of 6.12%. This contrasts with a softer 30-day share price move that declined 2.94%, while the 5-year total shareholder return above 7x original capital highlights longer term momentum and frames the current intrinsic discount in a different light.
Scan beyond Natural Resource Partners and size up other potential deep value ideas on our curated list of 29 high quality undervalued stocks.
The units trade near recent highs while one intrinsic value estimate still points to a steep discount. Does that skew the risk reward on Natural Resource Partners toward buyers, or toward investors waiting for a better entry point?
Price-to-Earnings of 14x for Natural Resource Partners: Is it justified?
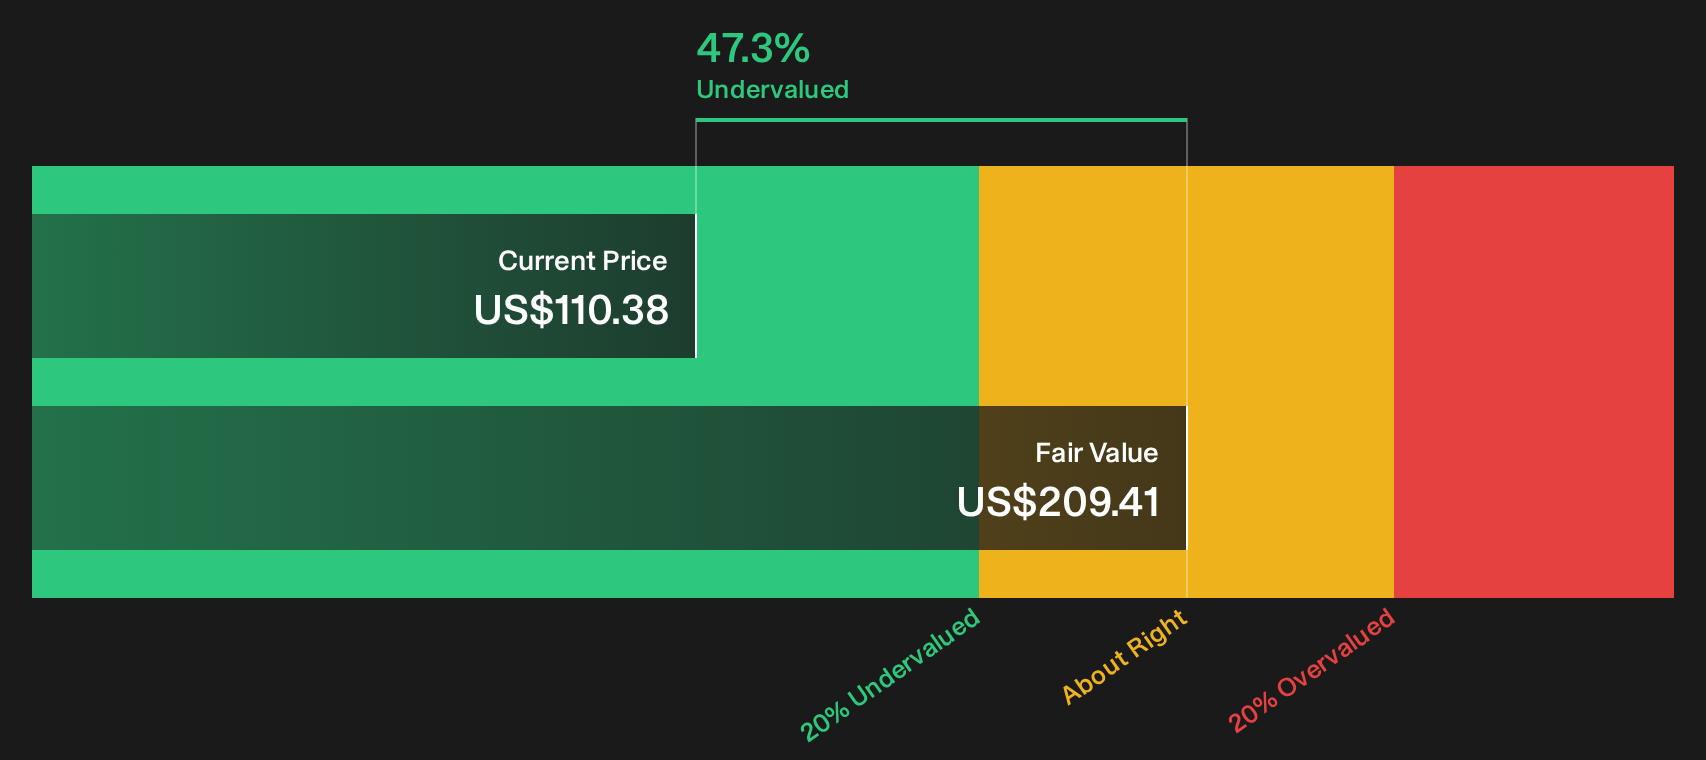
Valuation on Natural Resource Partners currently splits in two directions, with the units trading at a P/E of 14x while the SWS DCF model suggests a future cash flow value of $209.41 per unit compared with the recent close at $110.38.
The P/E ratio of 14x compares the latest unit price to the partnership’s earnings, giving a shorthand way to see how much investors are paying for each dollar of profit. For a minerals leasing and soda ash business with $199.97m of revenue and $104.56m of net income, that multiple frames how the market is weighing current profitability against the risks in coal, industrial minerals and soda ash royalties.
On relative terms the picture is mixed. Natural Resource Partners looks expensive compared with the broader US Oil and Gas industry on 12.3x earnings, yet appears cheap against a peer group on 33.5x earnings, which signals that investors are pricing in less optimism than the higher peer average but more than the wider sector is getting.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 14x (ABOUT RIGHT)
Still, the story on Natural Resource Partners can break if coal royalty volumes weaken sharply or if soda ash pricing pressure cuts into that $104.56m in net income.
Find out about the key risks to this Natural Resource Partners narrative.
Another View on Natural Resource Partners' Valuation
The SWS DCF model takes a different angle on Natural Resource Partners. It values future cash flows at $209.41 per unit while the recent price is $110.38. That implies the units trade at a heavy discount. If that gap holds, is the market misreading the durability of those royalties?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Natural Resource Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed sentiment around Natural Resource Partners is clear, so move fast, review the full picture of concerns and potential upsides, then weigh the 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Natural Resource Partners?
If you stop with Natural Resource Partners, you risk missing other opportunities that fit your style, risk tolerance, and income goals across the wider market.
- Target resilient performers by scanning a 31 resilient stocks with low risk scores that aims to keep potential downside in sharper focus while you hunt for steadier returns.
- Spot potential mispricings by reviewing a curated 29 high quality undervalued stocks where strong fundamentals and lower valuations line up for further research.
- Build a sturdier core by filtering through a list of solid balance sheet and fundamentals (25 results) that highlights businesses with financial structures designed to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com