


Indian markets are wrestling with rising RBI and US rates, surging US bond yields and Brent crude above $102, while foreign investors keep pulling money from local equities. That mix can punish stretched growth stories, yet spotlight steadier cash generators with dividends and cleaner balance sheets. This article walks through three Indian value and income stocks exposed to these macro shocks, and explains why their profiles might matter for your portfolio decisions now.
The three stocks covered next are just a starter set for this idea, and the full screen surfaced 13 more Indian-listed income and value candidates with equally detailed stories that are not unpacked in this article. If you want to quickly identify your own shortlist of potential higher rate beneficiaries, head straight into the Indian value stocks and high-quality dividend payers benefiting from higher interest rates screener to filter, analyze and focus on the highest conviction options.
Power Grid Corporation of India (NSEI:POWERGRID)
Overview: Power Grid Corporation of India runs India's interstate high voltage power transmission network, with additional telecom and consultancy activities.
Operations: The business generates most of its ₹443.2b revenue from transmission, with smaller contributions from telecom at ₹11.6b and consultancy at ₹24.6b.
Market Cap: ₹2.28t
Power Grid Corporation of India fits this higher rate, dividend-focused screen as a large regulated utility that many investors treat as a core income anchor when they want steadier cash flows than more cyclical sectors.
"The accelerating pace of nationwide electrification and urbanization is driving ongoing and large-scale CapEx in power transmission infrastructure. PGCIL is executing and commissioning record-high projects and holding a robust multi-year pipeline (over ₹148,000 crore of projects in hand, and annual CapEx plans rising from ₹28,000 crore to ₹45,000 crore in the next few years), which together could support revenue growth and long-term asset expansion."
What happens to those steady dividends and regulated returns if a single unseen pressure quietly reshapes the economics of that project pipeline?
That quiet pressure is exactly what you need to stress test. Read the full narrative for Power Grid Corporation of India to see how those CapEx plans could respond if project economics start to shift.

ACC (NSEI:ACC)
Overview: ACC Limited is an Indian cement and ready-mix concrete manufacturer supplying building materials and related products to housing, infrastructure and commercial projects.
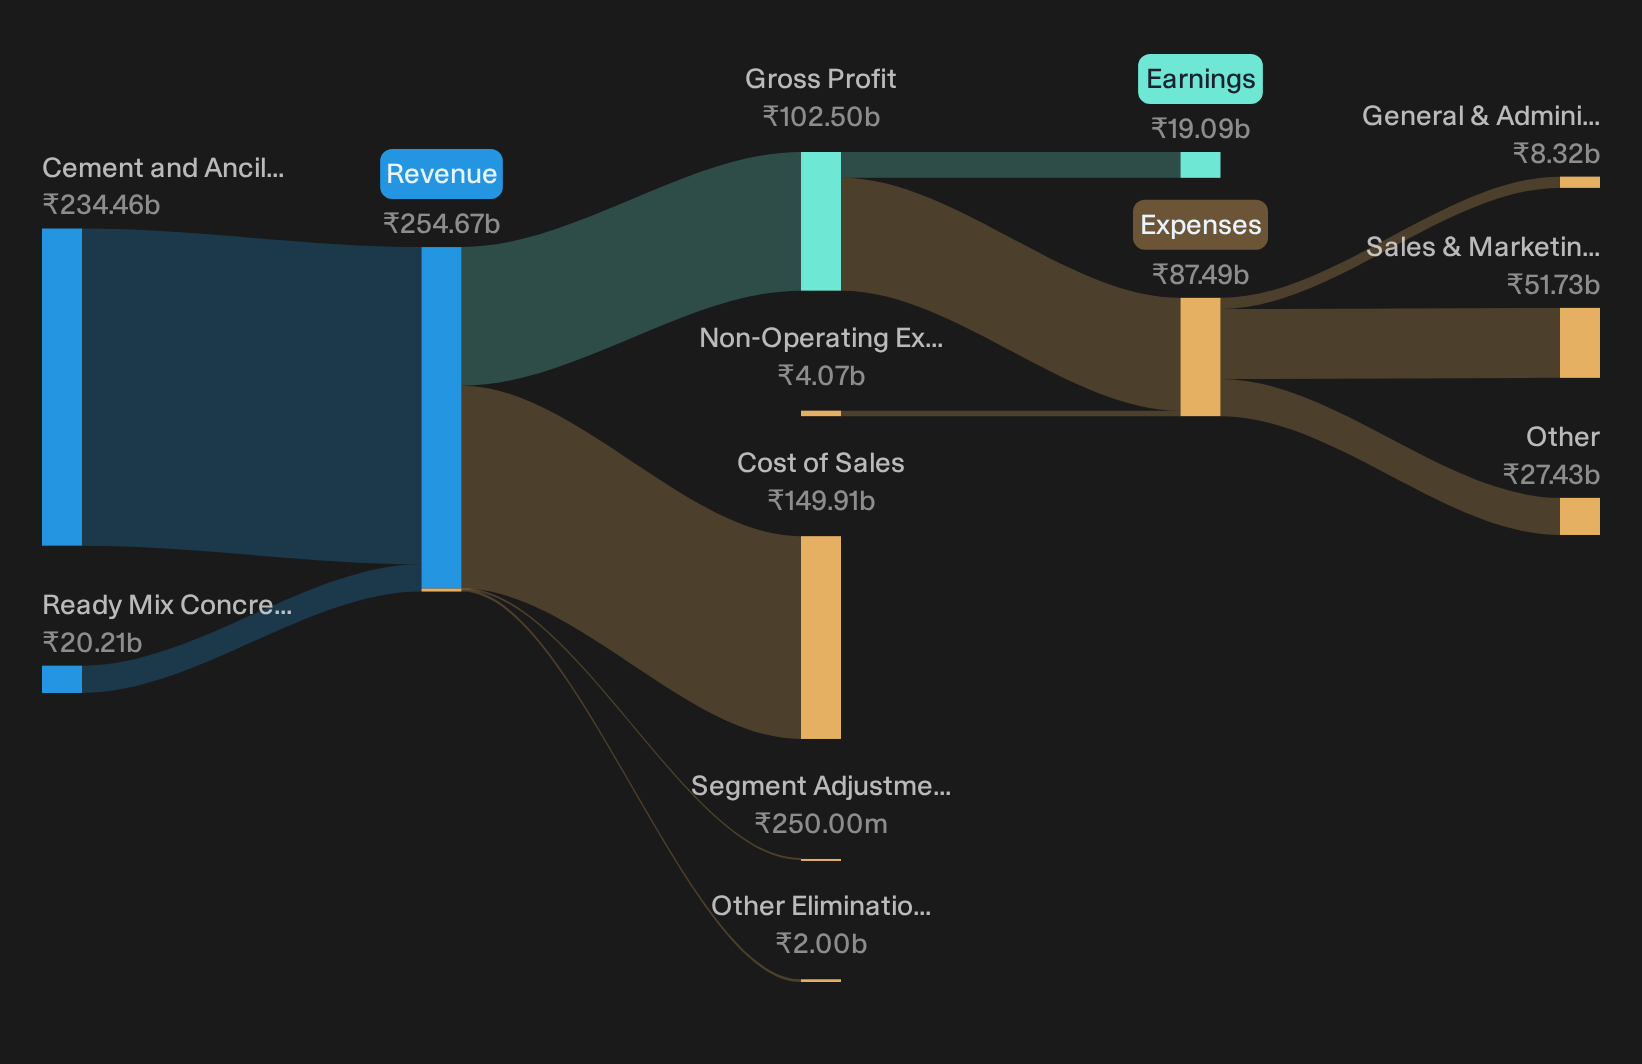
Operations: ACC generates about ₹234.5b from cement and ancillary services and ₹20.2b from ready-mix concrete, with a small segment adjustment.
Market Cap: ₹212.2b
ACC fits this higher rate, value oriented screener as a long established, asset backed cement producer that investors often view as a more grounded alternative to fast growing but richly priced growth stocks when borrowing costs climb.
"Rapid capacity expansion from 107 MTPA to 155 MTPA by FY '28, including low CapEx debottlenecking and new clinker lines, is expected to unlock operating leverage and support volume led revenue growth."
The key factor is how any shift in cost discipline and pricing power interacts with that expansion when funding costs stay elevated.
That tension is exactly what the full narrative for ACC unpacks, showing where ACC's expansion plans could accelerate returns and where funding costs might quietly cap the upside.
Bharti Airtel (BSE:532454)
Overview: Bharti Airtel runs large mobile, broadband, enterprise and digital TV networks across India and Africa, selling subscription connectivity and digital services.
Operations: Bharti Airtel generates about ₹1.16t from Mobile Services India, ₹622.9b from Mobile Services Africa and ₹331.3b from Passive Infrastructure Services, with Airtel Business contributing ₹217.8b.
Market Cap: ₹11.20t
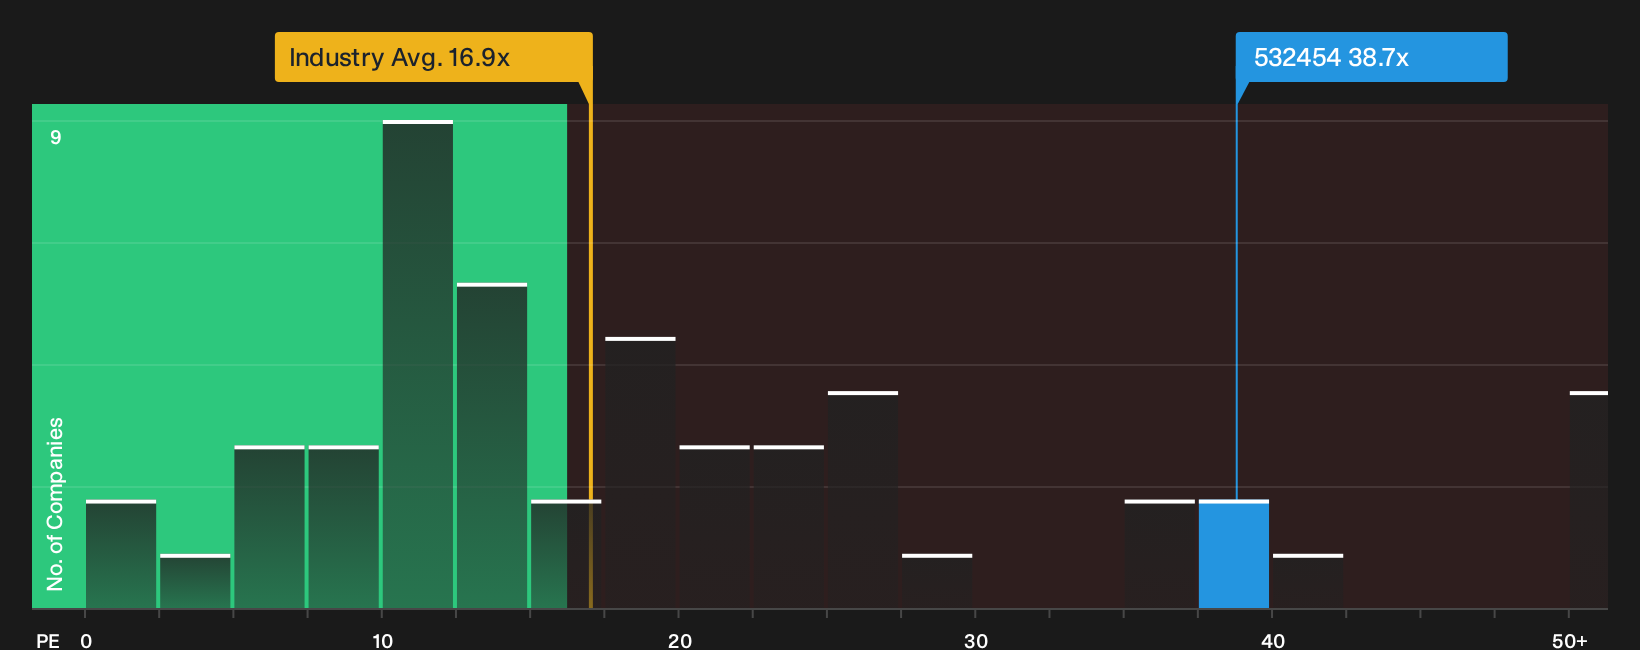
Bharti Airtel fits this higher rate, value and dividend screen as a telecom operator with subscription style cash flows. However, a rich 38.7x P/E, an unstable dividend record and margins that moved from 19.2% to 13.1% mean its appeal as a core income anchor now hinges on how one pressure on future profitability settles.
That single profitability pressure is exactly what you need to unpack, so head into the analyst forecasts for Bharti Airtel to explore Bharti Airtel's cash flows in more detail.
Seeking Alternatives Before The Crowd Moves
Fresh ideas often move first when momentum builds and laggards get caught dropping. Scan these under the radar for now opportunities while the window still looks open and consider acting before conditions change.
- Spot cash rich businesses quietly building momentum before headlines catch up by running the list of solid balance sheet and fundamentals (206 results) that filters out weak finances and fragile balance sheets.
- Identify potential yield opportunities by scanning the 224 dividend fortresses that focuses on sturdier payouts and higher income candidates while prices still look reasonable.
- Look for early stage outliers with earnings strength using the 35 profitable AI stocks that aren't just burning cash that zeros in on AI companies not purely burning cash.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com