


- First Citizens Bank recently launched First Citizens Innovation Banking and First Citizens Fund Banking to serve technology, healthcare and private equity and venture capital clients in the United States and internationally, building on the former Silicon Valley Bank operations.
- This move expands First Citizens BancShares' reach into the innovation economy and aligns its commercial banking focus with sectors that typically rely heavily on specialized credit, treasury and fund banking services.
- We will now see how the investment narrative of First Citizens BancShares could be shaped by the new Innovation Banking platform launch.
Scan how First Citizens BancShares’ push into tech and healthcare banking compares with other potential breakouts in the sector by reviewing our curated list of list of solid balance sheet and fundamentals (25 results).
First Citizens BancShares Investment Narrative Recap
To be a shareholder in First Citizens BancShares, you need to be comfortable with a bank that leans heavily into specialized commercial verticals while working through pressure on net interest margins. The big near term swing factor is whether management can keep remixing deposits and repaying higher cost funding quickly enough to stabilise net interest income after the recent US$101 million decline.
The largest risk right now is prolonged deposit competition. Some rivals are paying what management describes as unprofitable rates, which could keep funding costs sticky and leave the net interest margin around the recent 3.09% level or worse. The latest announcements do not fundamentally change that risk, even if execution goes well elsewhere.
The launch of First Citizens Innovation Banking and Fund Banking matters most for the current story. It ties directly into the existing Global Fund Banking pipeline of roughly US$11b and the push into Tech & Healthcare and Middle Market Banking that analysts highlight as key volume drivers for future loan and interest income potential.
If these platforms scale well, they could help offset margin pressure by focusing on fee based services and higher value commercial relationships. That still depends on disciplined underwriting and funding costs. Execution missteps, or a slower build out than expected, would weaken one of the clearer operational catalysts in the First Citizens BancShares narrative.
First Citizens BancShares' current analyst narrative points to revenues of US$9.6b and earnings of US$2.3b by 2029, based on an assumed 1.0% yearly revenue growth rate and flat profit of US$2.3b compared with earnings today.
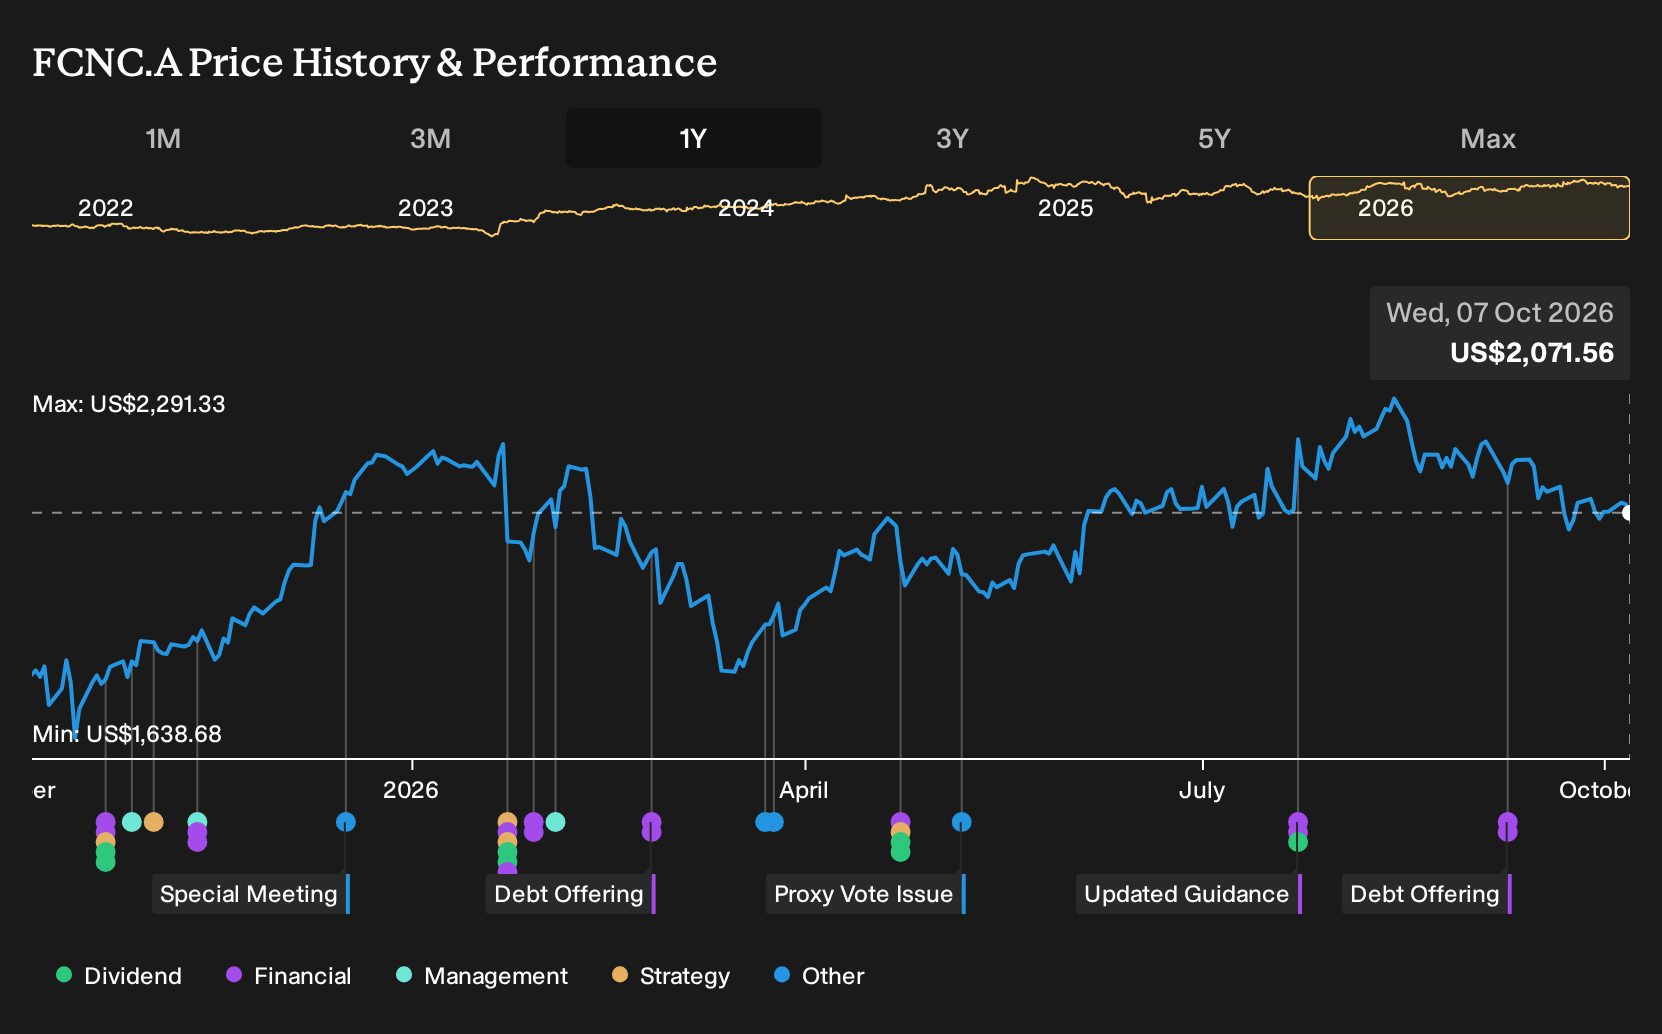
Uncover how First Citizens BancShares' fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Fair value views on First Citizens BancShares from the Simply Wall St Community currently span roughly US$2,336 to US$3,040 across just 2 individual assessments, so even a small sample produces a wide gap. Set that next to ongoing margin pressure and fierce deposit competition, and you can see why opinions vary so much. Explore those alternative viewpoints before deciding how this story fits your portfolio.
Explore another First Citizens BancShares fair value estimate, including one that suggests it could be worth just $2,336.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Citizens BancShares research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for First Citizens BancShares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Citizens BancShares' overall financial health at a glance.
Looking For More Investment Ideas Beyond First Citizens BancShares?
If the First Citizens BancShares story has sharpened your thinking, use that same lens across a broader watchlist. The Simply Wall St Screener lets you filter by fundamentals, balance sheet strength, and income profile so you can quickly zero in on opportunities that match your own risk and return preferences.
- If you want potential upside with stricter quality filters, scan a curated pool of 20 high quality undiscovered gems that already show robust fundamentals.
- For investors who care most about capital resilience, focus your search on 31 resilient stocks with low risk scores that score well on financial stability metrics.
- If reliable income is a priority, concentrate on 8 dividend fortresses that combine elevated yields with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com