


Oil-Dri Corporation of America (ODC) just reworked its balance sheet tools and confirmed fresh cash returns, updating its long running credit facilities and affirming the next quarterly dividend for both share classes.
The latest credit amendments and dividend affirmation land after a choppy spell in the chart, with Oil-Dri Corporation of America’s share price down 3.9% on the day and 19.2% over the past 90 days, yet still up 74.1% year to date and supported by a 42.5% 1 year total shareholder return that reflects strong multi year momentum rather than a short lived spike.
Scan beyond Oil-Dri Corporation of America and size up other balance sheet focused plays with disciplined capital returns in our curated list of solid balance sheet and fundamentals (25 results).
Oil-Dri Corporation of America now trades close to one estimate of intrinsic value after a sharp pullback. Is that a fair warning sign or a chance to pick up disciplined capital returns at a discount?
Price-to-Earnings of 23x: Is it justified?
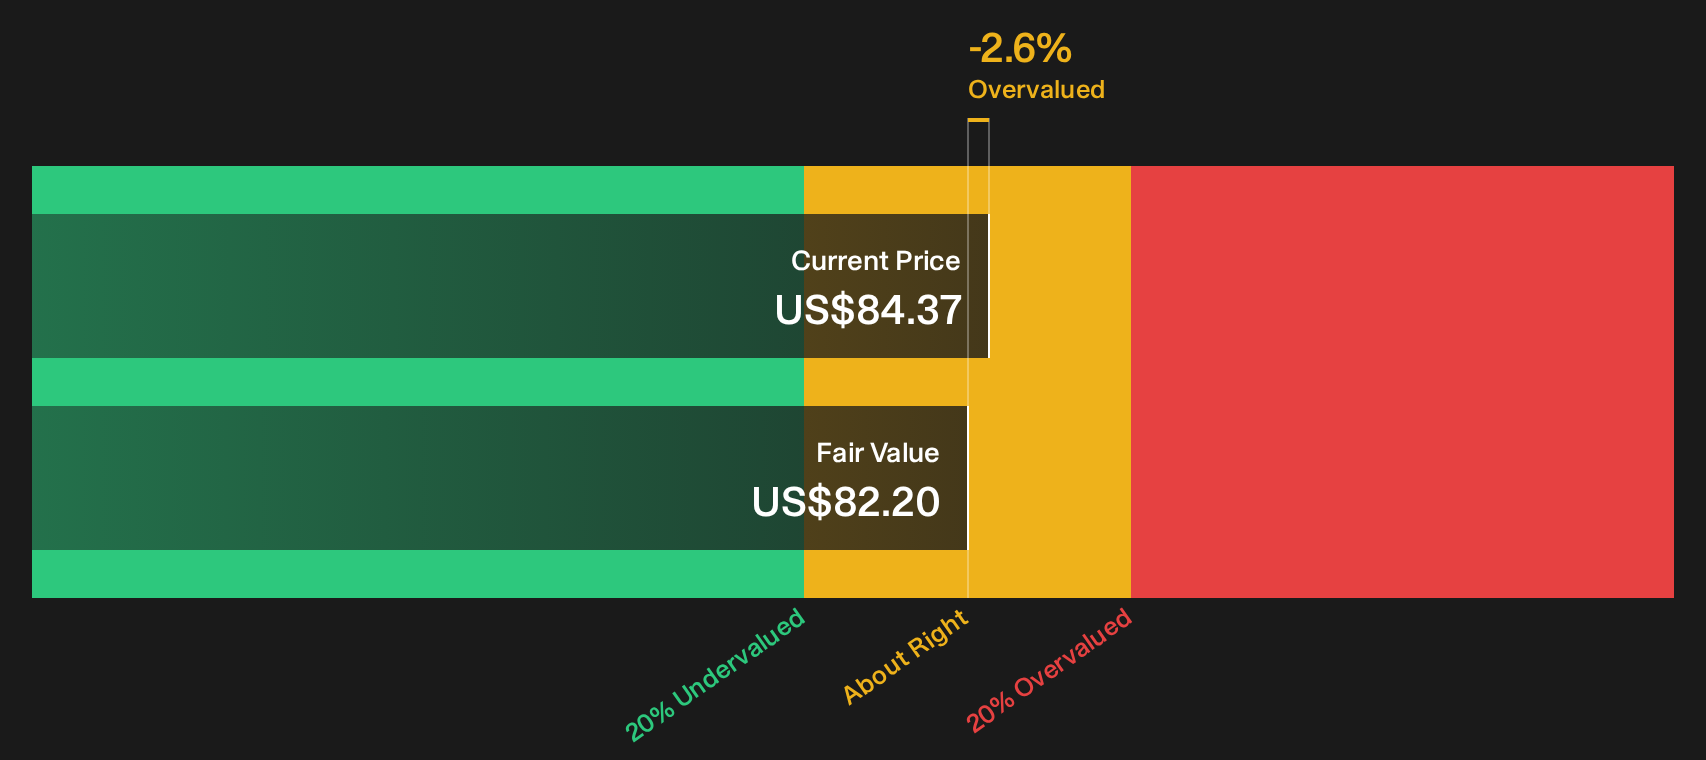
Valuation is tight around Oil-Dri Corporation of America at the moment, with the shares on a P/E of 23x and trading close to one internal cash flow estimate of fair value at $82.20 versus a last close of $84.37.
The P/E ratio compares what you pay per share to the earnings that Oil-Dri Corporation of America generates per share. For household products businesses that already produce consistent profits, investors often watch this measure closely because it reflects how much they are willing to pay for each dollar of earnings that is already in place.
Oil-Dri Corporation of America carries a P/E of 23x, which is higher than both the global Household Products industry average of 16.8x and a peer average of 21.6x. The richer valuation points to the market placing a premium on this earnings profile rather than discounting it, especially given earnings growth of 12.9% over the past year and a 5 year earnings growth rate of 37.6% per year.
That premium is not small. Compared with the wider Household Products group, the stock trades on a meaningfully higher multiple, which indicates investors are willing to accept a thinner earnings yield today relative to sector alternatives.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 23x (OVERVALUED)
Still, Oil-Dri Corporation of America faces real pressure points, including any slowdown in sorbent demand and potential margin strain if input or freight costs increase.
Find out about the key risks to this Oil-Dri Corporation of America narrative.
Another view on Oil-Dri Corporation of America’s value
Price guidance from a different valuation tool tells a similar story. Oil-Dri Corporation of America trades at $84.37 compared with an SWS DCF model estimate of future cash flow value at $82.20, which points to a mildly overvalued outcome rather than a clear bargain. Whether that small premium is a concern or simply reflects the cost of quality earnings is open to interpretation.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Oil-Dri Corporation of America for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Oil-Dri Corporation of America’s valuation and rewards can feel messy, so this is a good moment to move fast and test the numbers yourself. To weigh the optimism already priced in against those potential rewards, start with the 1 key reward.
Looking for more investment ideas beyond Oil-Dri Corporation of America?
You have already done the hard work on Oil-Dri Corporation of America, so do not miss the chance to pressure test your watchlist against fresh, data driven stock ideas.
- Target resilient balance sheets and clear fundamentals by running your own screen through the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a discount by scanning companies that line up in the 27 high quality undervalued stocks.
- Sharpen your income focus by reviewing a curated 8 dividend fortresses that may complement or challenge what you already own.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com