


- KB Home recently opened City Vista, a community of three-story paired homes in Escondido, California, with prices from the mid US$600,000s and an emphasis on energy efficiency, wildfire resilience, and family friendly amenities.
- The project pairs ENERGY STAR certified design with Insurance Institute for Business & Home Safety wildfire standards, highlighting how KB Home is responding to buyer demand for lower utility costs and physical risk mitigation in one package.
- We will now look at how KB Home's investment narrative is shaped by the energy efficient, wildfire resilient City Vista launch.
Scan how KB Home’s energy efficient, wildfire resilient approach compares with other builders by reviewing our hand picked list of solid balance sheet and fundamentals (25 results) targeting quality-focused housing and construction stocks.
KB Home Investment Narrative Recap
To own KB Home, you need to believe that a slower growing but still profitable builder can keep turning its land pipeline, build time gains, and design customization into steady earnings, even with softer demand. City Vista fits that story. It showcases energy efficient, wildfire resilient product in a higher priced California market, without changing the near term thesis on its own.
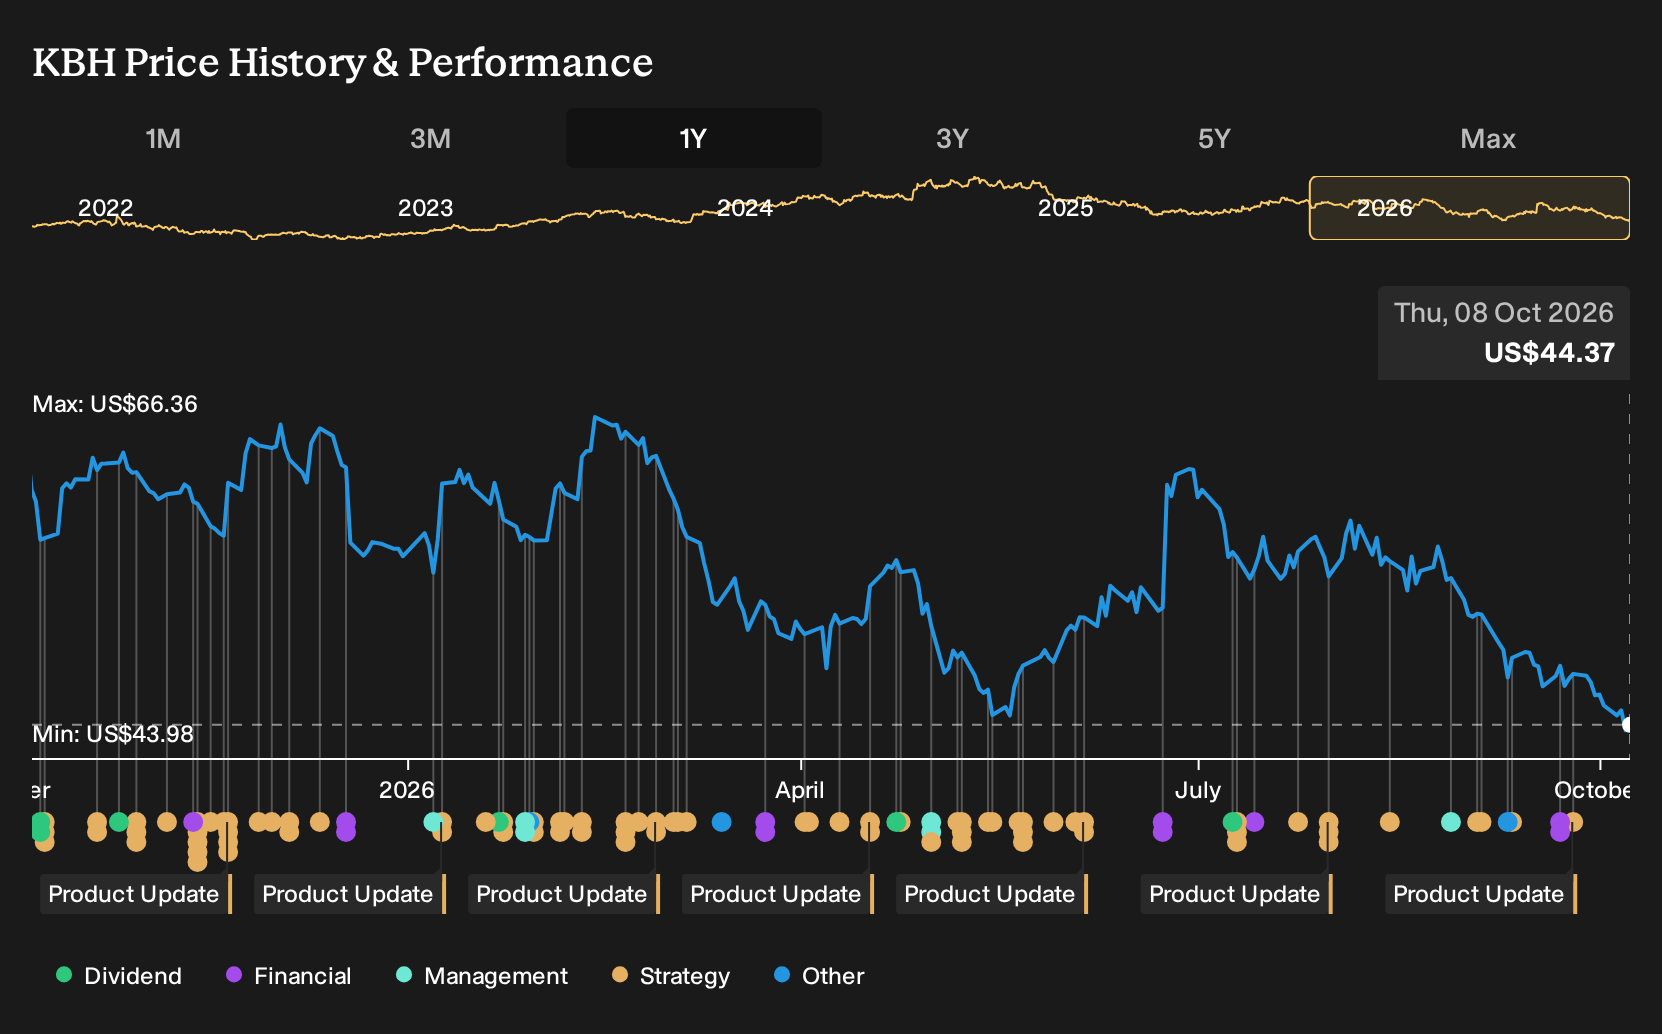
The more immediate swing factor still looks like order trends and pricing power, as consumer confidence and affordability pressures weigh on volumes. The biggest risk remains margin pressure if incentives rise or regional weakness persists, especially with debt not well covered by operating cash flow and profit margins already below last year.
The City Vista launch is the most relevant operational update here because it shows KB Home leaning into differentiated product, not just more communities. ENERGY STAR certification combined with IBHS wildfire standards gives the builder a way to talk about utility bills and physical risk in the same breath, which can matter in markets like Southern California.
For catalysts, execution on projects like City Vista links directly to build times, pricing discipline, and inventory turns. If these communities convert backlog efficiently, that supports the existing story of improved construction cycle times and cost management. If demand in these higher priced, risk sensitive areas softens, it could amplify the existing concerns around softer net orders and the need for price adjustments.
KB Home's narrative projects US$5.5b revenue and US$299.5 million earnings by 2029. This assumes 1.9% yearly revenue growth and an earnings increase of about US$74.6 million from US$224.9 million today.
Learn why KB Home's fair value suggests a 23% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
City Vista puts KB Home’s higher priced West Coast exposure front and center, yet the most bearish analysts still focus on margin pressure. They were penciling in roughly flat revenue at about US$5.3b and earnings of US$274.9 million by 2029. That is a more cautious story. Use this launch as a cue to compare those pre news estimates with other viewpoints.
Explore 2 other KB Home fair value estimates, including one that suggests it could be worth just $53.07.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your KB Home research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for KB Home. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KB Home's overall financial health at a glance.
Looking for more KB Home style investment ideas?
If the KB Home story has you thinking about where else quality, risk management, and balance sheet strength intersect, it can help to line up a wider watchlist using the Simply Wall St Screener.
- For investors who want strong financial footing with room for upside, review a curated 20 high quality undiscovered gems that combine solid fundamentals with room to grow.
- If income is a priority and you care about consistent cash returns, scan a focused selection of 8 dividend fortresses that aim to pair yield with resilience.
- When capital preservation matters just as much as returns, filter for 31 resilient stocks with low risk scores that score well on financial strength and downside protection.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com