


In recent times, Asian markets have experienced a mix of volatility and opportunity, driven by factors such as fluctuating oil prices and evolving monetary policies. As investors navigate these complex conditions, identifying stocks that may be undervalued could offer potential for growth; a good stock in this context is one that demonstrates strong fundamentals despite broader market uncertainties.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Woori Financial Group (KOSE:A316140) | ₩32350.00 | ₩64525.41 | 49.9% |
| TOKAI (TSE:9729) | ¥2535.00 | ¥5037.09 | 49.7% |
| Shinhan Financial Group (KOSE:A055550) | ₩99500.00 | ₩195820.97 | 49.2% |
| Nissui (TSE:1332) | ¥1082.50 | ¥2151.90 | 49.7% |
| Mitsubishi Research Institute (TSE:3636) | ¥4840.00 | ¥9627.05 | 49.7% |
| Marco Polo Marine (SGX:5LY) | SGD0.118 | SGD0.23 | 49.4% |
| Kumagai GumiLtd (TSE:1861) | ¥1193.00 | ¥2362.31 | 49.5% |
| Innocean Worldwide (KOSE:A214320) | ₩17980.00 | ₩35599.11 | 49.5% |
| ENN Energy Holdings (SEHK:2688) | HK$49.14 | HK$96.85 | 49.3% |
| Double Medical Technology (SZSE:002901) | CN¥39.60 | CN¥79.04 | 49.9% |
Here's a peek at a few of the choices from the screener.
Shanghai Flyco Electrical Appliance (SHSE:603868)
Overview: Shanghai Flyco Electrical Appliance Co., Ltd. (SHSE:603868) operates in the home appliance sector, focusing on the design and manufacture of personal care electrical products, with a market cap of CN¥13.85 billion.
Operations: The company's revenue from home appliances totals CN¥3.76 billion.
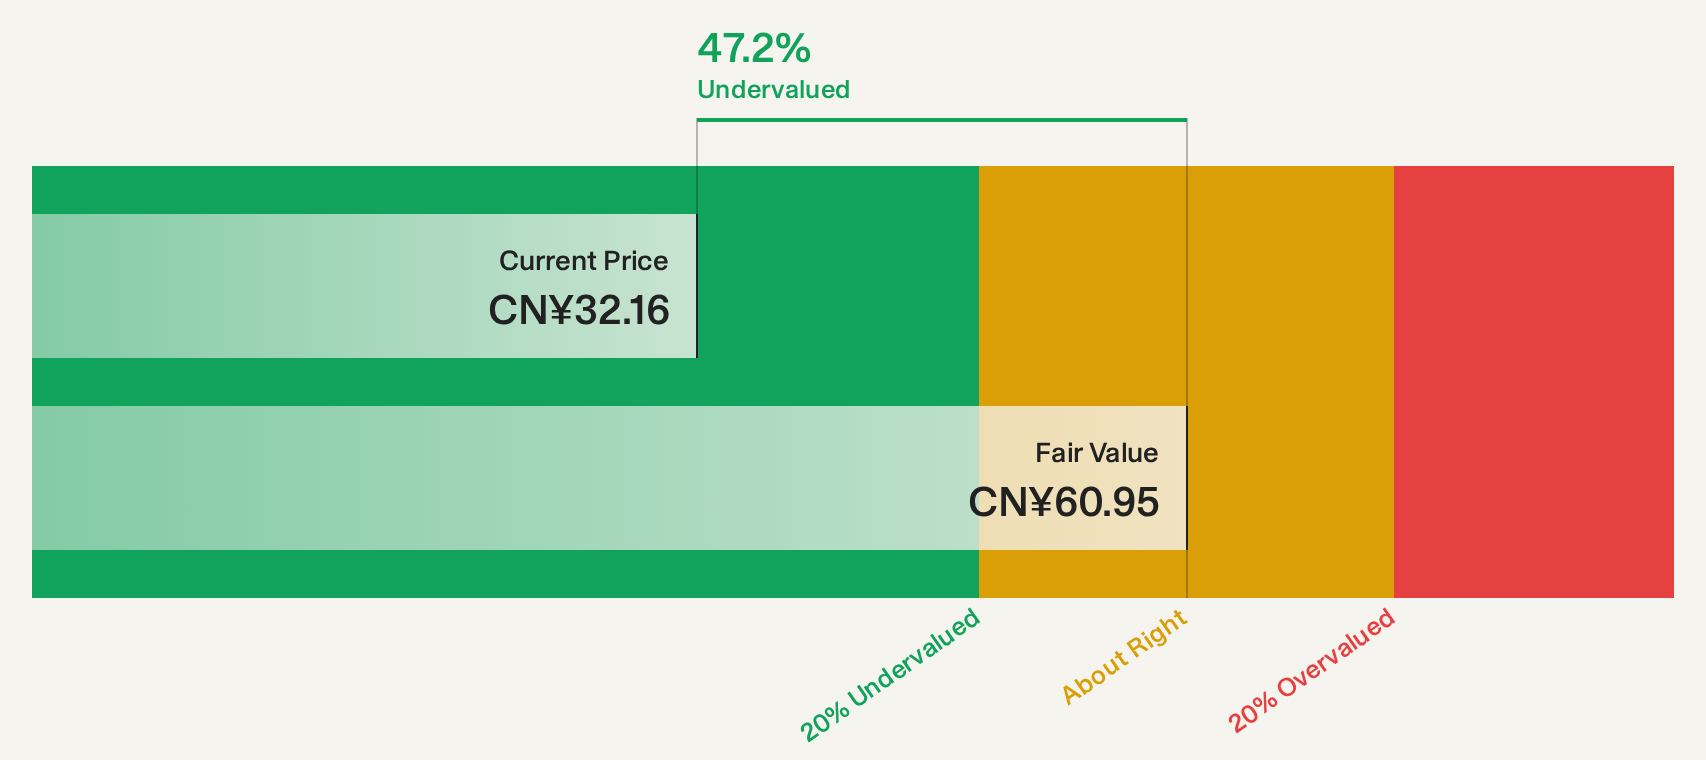
Estimated Discount To Fair Value: 47.8%
Shanghai Flyco Electrical Appliance is trading at a significant discount to its estimated future cash flow value, with shares priced at CN¥31.79 compared to a fair value of CN¥60.91. Despite stable earnings growth of 11.89% annually, this falls short of the broader Chinese market's pace. The company's recent net income increase and positive earnings per share highlight potential undervaluation, though its dividend track record remains unstable and revenue growth lags behind market expectations.
- According our earnings growth report, there's an indication that Shanghai Flyco Electrical Appliance might be ready to expand.
- Click here to discover the nuances of Shanghai Flyco Electrical Appliance with our detailed financial health report.
STO ExpressLtd (SZSE:002468)
Overview: STO Express Co., Ltd offers express delivery services both within China and internationally, with a market capitalization of CN¥22.46 billion.
Operations: The company generates revenue primarily from its express service segment, which accounts for CN¥62.23 billion.
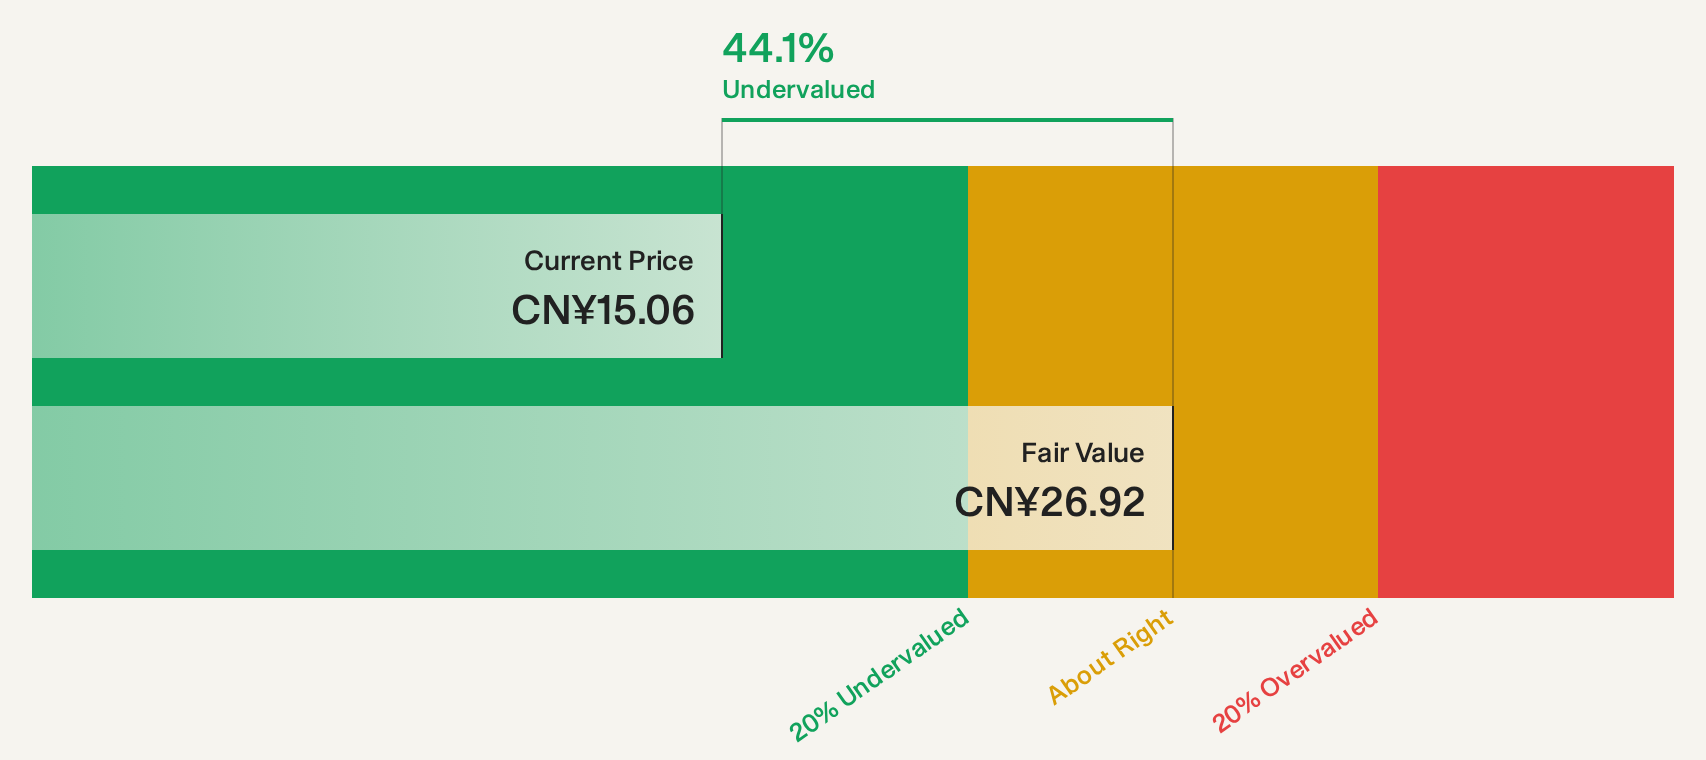
Estimated Discount To Fair Value: 44.8%
STO Express Ltd. is trading at a discount to its estimated future cash flow value, with shares priced at CN¥14.86 against a fair value of CN¥26.91. Despite earnings growth of 9.1% annually, this trails the broader Chinese market's rate. Recent earnings results show significant profit increases, yet revenue growth remains below market expectations and the dividend track record is unstable, amid recent changes in company bylaws and capital structure adjustments.
- Insights from our recent growth report point to a promising forecast for STO ExpressLtd's business outlook.
- Take a closer look at STO ExpressLtd's balance sheet health here in our report.
Beijing Career International (SZSE:300662)
Overview: Beijing Career International Co., Ltd. offers human resource and talent solutions with a market cap of CN¥4.12 billion.
Operations: The company generates revenue from the Human Resource Industry, amounting to CN¥15.58 billion.
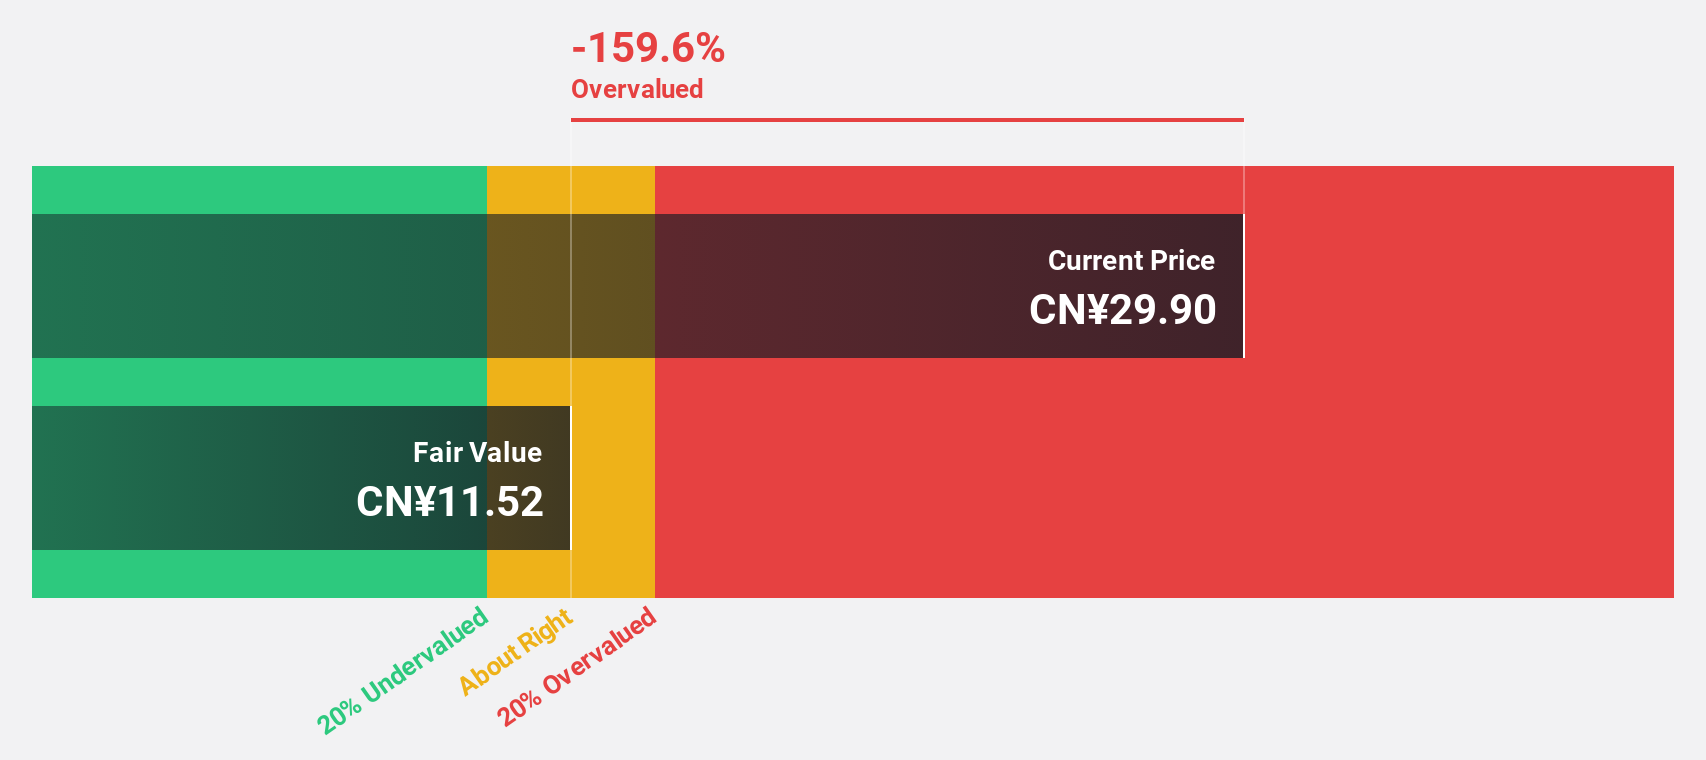
Estimated Discount To Fair Value: 26.1%
Beijing Career International is trading at CN¥20.91, significantly below its estimated future cash flow value of CN¥28.28, suggesting undervaluation. Analysts project a 33.9% price rise, though revenue and earnings growth forecasts lag behind the broader Chinese market. Recent half-year earnings show improved sales (CN¥8.12 billion) and net income (CN¥151.46 million), but the company faces challenges with unstable dividends and large one-off items affecting financial results.
- The growth report we've compiled suggests that Beijing Career International's future prospects could be on the up.
- Click here and access our complete balance sheet health report to understand the dynamics of Beijing Career International.
Where To Now?
- Click through to start exploring the rest of the 167 Undervalued Asian Stocks Based On Cash Flows now.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com