


NETSTREIT has delivered a 36.2% gain over the past 3 years, even though shorter term returns have been softer. With the stock recently closing at US$17.43, the key issue for investors is how firmly that price rests on the real estate investment trust's earnings power.
- A 36.2% return over 3 years puts meaningful weight on whether NETSTREIT's current earnings profile can support the value the market is assigning today.
- The business model, built around single tenant net lease properties and contracted rent, can shape how reliably earnings convert into cash that supports the current equity value.
- There is a second opinion on NETSTREIT worth weighing. See what analysts think NETSTREIT's shares could be worth.
For investors, the debate is whether NETSTREIT's present share price is fully justified by the earnings it generates today and is expected to produce over time.
If you are weighing NETSTREIT on its earnings today, it can help to set it alongside other businesses that pass similar filters by scanning through 27 high quality undervalued stocks.
Does NETSTREIT Look Pricey on Earnings?
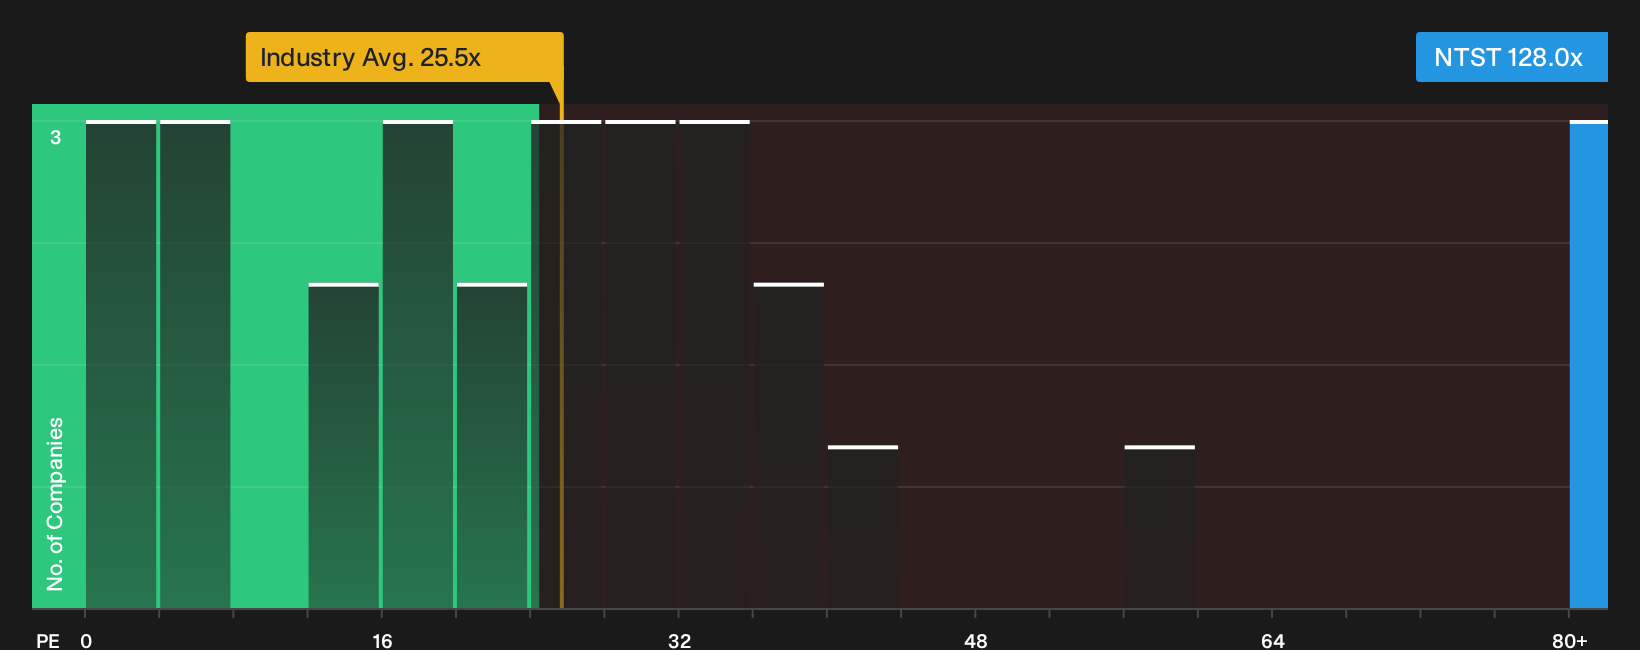
The P/E ratio fits NETSTREIT well because earnings are a key reference point for a real estate investment trust that leans on contracted rent. On this lens, the stock trades on a P/E of about 128.0x, which is more than double both the Retail REITs industry average of roughly 25.5x and the peer group average around 58.1x. That is a rich headline number for a business where cash flows are tied to leases rather than high growth optionality.
The tailored fair multiple that folds in NETSTREIT’s size, sector, margins and risk profile points to a lower P/E than the one the market is currently paying. That gap indicates the shares screen overvalued on this earnings yardstick and that a lot of confidence is already embedded in the US$17.43 price. Investors weighing an entry or adding to a position may want to check how that premium lines up with their own expectations for the trust’s rental income, balance sheet and acquisition pipeline before acting. Explore the numbers behind NETSTREIT's P/E valuation.
The NETSTREIT Narrative: What Would Justify Today's Price?
Narratives on NETSTREIT sit on Simply Wall St's Community page and connect the valuation question above with the specific assumptions on future growth, profitability and rental earnings that would need to play out for the stock to be worth materially more or materially less than it is today. Each view ties its number to a clear stance on how NETSTREIT's growth, margins and risk profile might evolve, which you can then revisit as fresh information comes through.
One of the top community narratives on NETSTREIT: 24% undervalued
Conservative use of NETSTREIT’s balance sheet, including adjusted net debt to annualized adjusted EBITDA of 3.2x and access to about US$1.1b of liquidity...
Discover why this Narrative puts NETSTREIT at 24% undervalued.
NETSTREIT’s valuation still hinges on who is steering the ship
Hard numbers only go so far when you do not yet know how the people in charge think, what they prioritize, and how their pay packets shape those choices. See who runs NETSTREIT and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com