


Parker-Hannifin (PH) just reported record fiscal 2026 fourth quarter sales of US$5.8b, with adjusted earnings per share up 21%, along with fresh fiscal 2027 guidance that highlights expectations for steadier earnings and cash flow.
The share price tells a different story to the recent earnings headlines. Parker-Hannifin is up 5.93% on a year to date share price basis, while the 1-year total shareholder return of 29.25% and very large 3-year and 5-year total shareholder returns suggest longer term momentum is still strong, even after a softer few months of trading.
Scan for other Parker-Hannifin style industrials with strong cash generation and perceived valuation gaps by reviewing the hand picked 27 high quality undervalued stocks.
The question now is simple. Is Parker-Hannifin’s softer recent share move simply sentiment cooling after a strong multi year run, or does it indicate a mismatch between the share price and the underlying business value?
Most Popular Narrative: 19% Undervalued
The most followed narrative on Parker-Hannifin pegs fair value at about $1,163 per share, compared with the last close of $946.96, which frames the recent share price softness as a potential gap between fundamentals and sentiment.
The enlarged portfolio of longer-cycle, higher-margin businesses, including Aerospace, Engineered Materials and Filtration, now represents about 65% of pro forma sales and includes recently added filtration assets. This can increase the share of recurring and aftermarket revenue and support more stable earnings and cash generation across economic cycles.
See why 46 investors see Parker-Hannifin as 19% undervalued.
Result: Fair Value of $1,163 (UNDERVALUED)
Still, slower organic revenue growth of 3.2% and a premium P/E versus US machinery peers leave Parker-Hannifin exposed if industrial demand or margin progress disappoints.
Find out about the key risks to this Parker-Hannifin narrative.
Another Way To Look At Parker-Hannifin
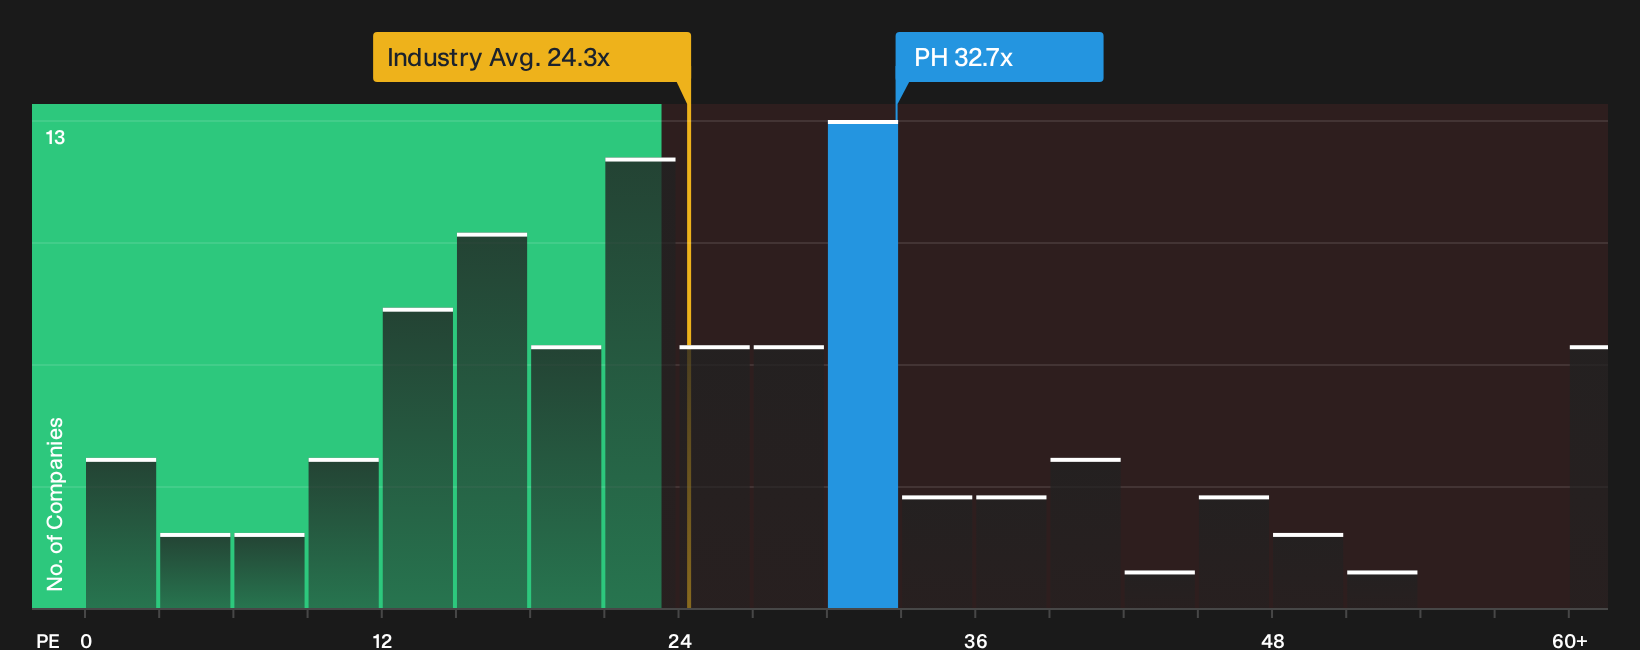
The popular fair value story paints Parker-Hannifin as roughly 19% undervalued, yet the market is already paying a rich P/E of 32.7x. That compares with 24.3x for the wider US Machinery group, 23.6x for peers, and a fair ratio of 28.8x that the market could gravitate toward.
If sentiment cools and the multiple drifts closer to that fair ratio, investors face valuation pressure even if earnings keep progressing. The question is whether you think Parker-Hannifin has earned this premium or if today’s pricing leaves less room for error.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in the article may sound mixed, with both enthusiasm and caution circling Parker-Hannifin, so weigh the numbers yourself and decide where you stand. To balance the optimism around the story with the concerns being raised, review the 3 key rewards and 2 important warning signs.
Looking for more Parker-Hannifin style investment ideas?
If Parker-Hannifin has sharpened your focus on quality and pricing, broaden your watchlist now with a few targeted screens so you are not relying on one story alone.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities that echo Parker-Hannifin’s valuation talking points by scanning the 27 high quality undervalued stocks.
- Unearth lesser known businesses with strong underpinnings before they gain wide attention by checking the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com