


- B2Gold reported positive 2026 exploration results at the Back River Gold District in Nunavut, with high grade intercepts at Llama and Nuvuyak and a new Tattuk discovery. These results were supported by a $51 million program covering over 35,000 m of drilling and extensive regional sampling work.
- The focus on infill drilling at Goose Mine and resource definition at regional targets like Locale 1 and Dragon South suggests B2Gold is working to convert more of its resource base into mine plans. This could influence future production optionality and cost structure.
- We will now explore how B2Gold's investment narrative could shift as the Back River Tattuk discovery sharpens the Goose Mine resource story.
Compare B2Gold's Back River momentum with other potential gold producers by scanning our hand picked list of 35 elite gold producer stocks that could reshape your watchlist.
B2Gold Investment Narrative Recap
To own B2Gold, you need to be comfortable with a mid tier producer that leans heavily on existing mines while trying to turn Goose and the broader Back River district into a long life Canadian hub. The short term swing factor remains how smoothly Goose ramps and how much of the inferred material around Llama and Nuvuyak can move into mine plans.
The biggest operational risk still sits in execution and capital discipline, especially with higher risk jurisdictions and rising spend at Goose. The latest Back River results look supportive rather than transformational on that front. They refine the resource picture and timing of mine plans more than they change the near term thesis.
The current Back River exploration update is the key announcement to focus on. B2Gold has already completed 27,493 m of a planned 35,000 m drilling program backed by a $51 million budget, which is a sizeable commitment to shoring up future feed for Goose and testing new zones that could matter for mine life.
High grade intercepts at Llama, confirmation work at Nuvuyak and the Tattuk discovery give the team more data to design pits, underground access and sequencing. For investors, the link runs straight through to capital allocation, potential future cost structure and how much Back River can offset geopolitical and permitting risk in Mali and Colombia over time.
B2Gold's current analyst narrative points to revenues of $3.7b and earnings of $1.8b by 2028, built on an assumed 19.2% yearly revenue growth rate and a move from a loss of $433.6m today to that profit level, which represents an earnings swing of about $2.2b.
Uncover why B2Gold's fair value indicates an 18% potential upside to its current price that could narrow quickly.
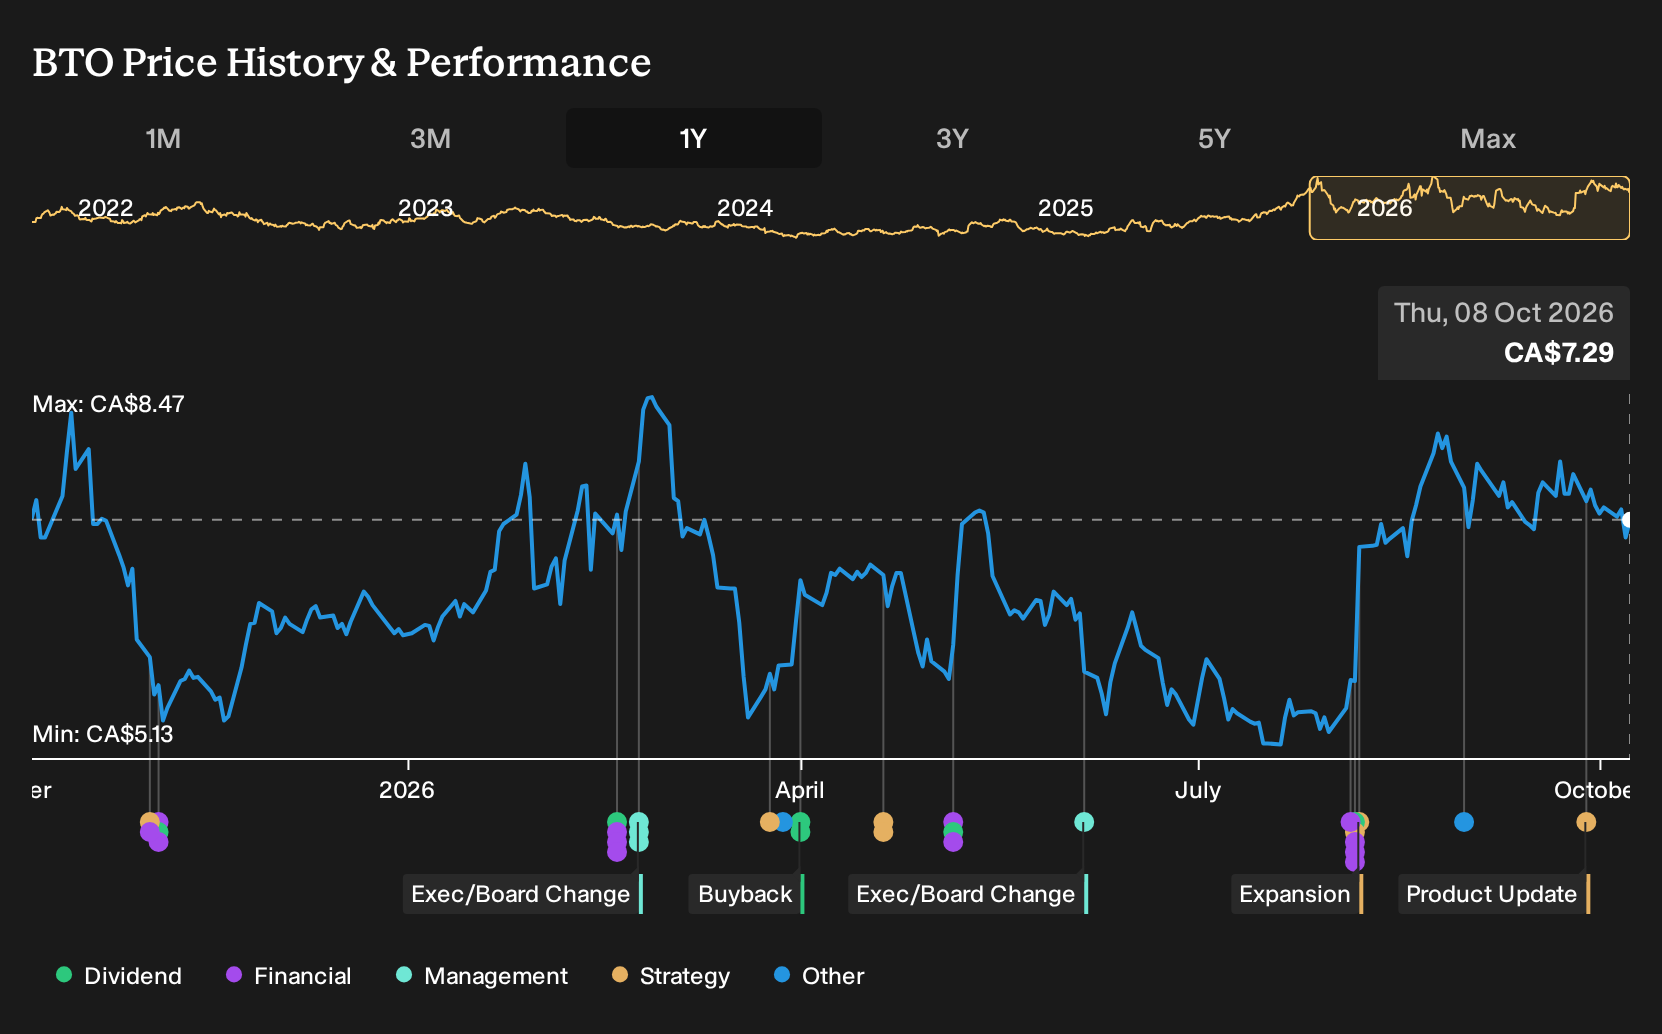
Exploring Other Perspectives
One alternative view on B2Gold leans heavily on Goose Mine as a potential upside catalyst. The most optimistic analysts were already penciling in about $7.0b of revenue and $2.0b of earnings by 2029. Those figures came before this Back River update, so you may see those projections and the underlying story shift as fresh data filters through.
Explore 4 other B2Gold fair value estimates, including one that suggests potential upside of up to 749% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your B2Gold research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for B2Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate B2Gold's overall financial health at a glance.
Looking For More Investment Ideas Beyond B2Gold?
If the B2Gold story has sharpened your thinking about risk, balance sheets and upside, it can help to line it up against a wider watchlist. The Simply Wall St Screener lets you quickly filter for other companies that fit the kind of profile you want to research next.
- For investors hunting for quality at a reasonable entry point, start with a curated set of 7 high quality undervalued stocks that already combine solid fundamentals with appealing pricing signals.
- If capital preservation and steadier profiles matter most to you, focus on a 8 resilient stocks with low risk scores that screens for businesses with more resilient characteristics.
- When you want to concentrate on financial strength, zero in on a list of solid balance sheet and fundamentals (7 results) that highlights companies with cleaner leverage and healthier funding structures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com