


The Zhitong Finance App learned that as the US refining industry is about to enter the financial reporting season for the third quarter of 2026, Goldman Sachs has updated its profit forecast for the US refining industry. Prior to the announcement of the results, Goldman Sachs focused on three core issues based on discussions with investors: (a) the prospects for mid-cycle profit margins after the fundamentals of the global refining industry were tightened and supply was disrupted; (b) the price spread trend between light crude oil and heavy crude oil as the supply of heavy crude oil increased in Canada and Venezuela; and (c) capital allocation priorities, that is, how to maintain a steady balance sheet, promote internal growth projects, and return to shareholders.
Despite these problems, Goldman Sachs is optimistic about the overall environment in the refining industry, and emphasized that the bank is relatively more fond of “buy” stocks, including Valero Energy (VLO.US), Marathon Crude Oil (MPC.US), and HF Sinclair (DINO.US).
Goldman Sachs said that for Valero Energy, the bank continues to believe that the company will be an important beneficiary of the tightening fundamentals of the refining industry, considering the company's location advantages on the US Gulf coast, high-quality asset portfolio, and the management's consistent outstanding execution capabilities.
When it comes to marathon crude oil, Goldman Sachs is optimistic about its shareholders' capital return prospects. The company's ability to return on capital is strongly supported by MPLX LP (MPLX.US) dividends, and also benefits from its scale advantage, strong ability to achieve profit margins, and a sound balance sheet.
Finally, for investors who focus on small to medium cap stocks, Goldman Sachs reiterated its positive view of HF Sinclair. Considering the company's business layout in the refining market segment, the profit contribution of the lubricants business, and the potential opportunities brought about by the Small Refinery Exemption (SRE), the bank believes that its current share price level has an attractive risk-reward ratio.
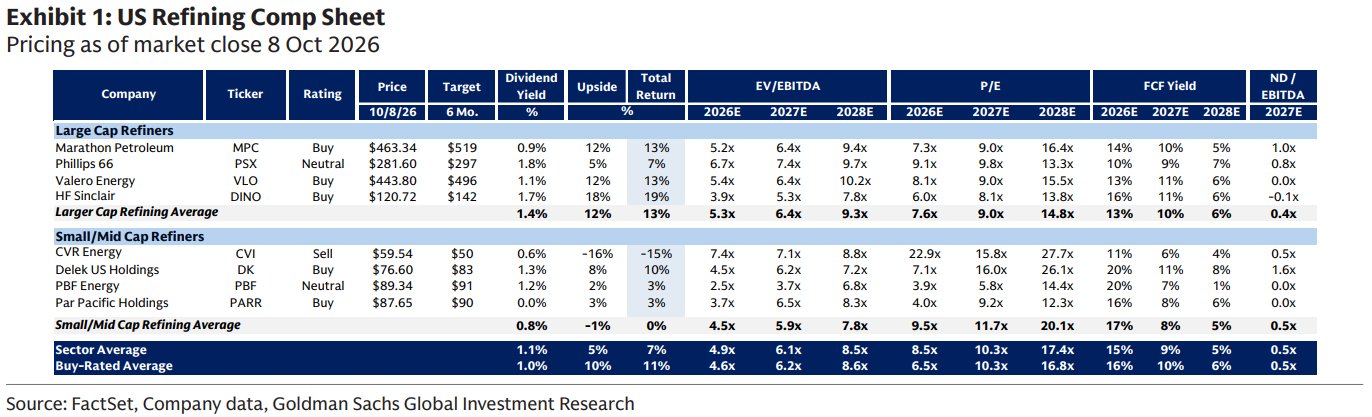
Key analysis of individual stocks
Valero Energy
Goldman Sachs gave Valero Energy a “buy” rating, with a target price of $496. The bank continues to emphasize that Valero Energy has an excellent asset layout along the US Gulf Coast, can flexibly adjust the crude oil processing structure, and has the advantage of low cost operation. The bank believes that these factors will support the company to achieve significant free cash flow in the short and medium term.
According to Goldman Sachs's updated forecast, the company's 2027 and 2028 free cash flow returns are expected to be around 11% and 6%, respectively. Furthermore, Goldman Sachs is optimistic about management's prudent capital allocation approach. Valero Energy prioritizes safe, reliable operations, a sound balance sheet, and shareholder returns. Notably, the company still promises to use 40% to 50% of the adjusted operating cash flow for shareholder returns through share repurchases and dividends.
In the upcoming earnings call, Goldman Sachs expects investors to focus on the following issues: (a) comments on the refining industry's macro environment; (b) prospects for light crude oil and heavy crude oil price differences; and (c) renewable diesel profit margins for the DGD business.
Marathon crude oil
Goldman Sachs gave Marathon crude oil a “buy” rating, and the target price was $519. Goldman Sachs continues to be optimistic about Marathon Crude Oil because the company has scale advantages, a complete industrial value chain, and a high-quality business layout on the US Gulf Coast and West Coast. Goldman Sachs also continues to be optimistic about the value of the company's refining business, mainly due to its commercial optimization capabilities, low cost operating advantages, and past performance in continuously achieving strong profit margins.
Finally, Goldman Sachs believes that Marathon Crude Oil's capital return prospects are very attractive because shareholder returns throughout the industry cycle can be strongly supported by midstream business dividends. MPLX allocations can cover the maintenance capital expenses and dividend expenses of Marathon Crude Oil.
Before the financial report is announced, Goldman Sachs will pay attention to management's comments on the following issues: (a) refining profit margin prospects for each region of the company's operations; (b) MPLX's future dividend prospects; and (c) capital allocation priorities.
HF Sinclair
Goldman Sachs gave HF Sinclair a “buy” rating, and the target price was $142. For investors interested in small to medium capitalization stocks, Goldman Sachs strongly recommends HF Sinclair. The bank believes that the stock is expected to achieve a total return of about 19% compared to the current stock price. This expectation is mainly supported by the following factors: the company's business layout in the refining market segments such as the Rocky Mountain region and the mid-mainland US region, the ability of business segments outside the refinery business to contribute significant profits, and potential opportunities brought about by the Small Refinery Exemption (SRE).
In addition, Goldman Sachs emphasized that management is working to improve the operational performance of the refining business. Specific measures include optimizing the crude oil processing structure, increasing the share of aviation fuel production, and enhancing operational reliability.
Looking ahead, Goldman Sachs expects that HF Sinclair's discussions during the third quarter of 2026 earnings conference call will focus on: (a) supply and demand dynamics in the refinery industry; (b) the monetization of renewable fuel identification numbers (RIN) and future expectations for small refinery exemptions (SRE); (c) the latest developments in the company's midstream business growth projects; (d) capital allocation priorities; and (e) the latest developments in the planned spin-off of the lubricants business.
Phillips 66
Goldman Sachs gave Phillips 66 (PSX.US) a “neutral” rating, and the target price was $297. Goldman Sachs noticed that in exchanges with investors, the core controversy surrounding the company mainly focused on three aspects: the deleveraging process, the improvement in the operating performance of the refining business, and whether the midstream business can achieve the annual EBITDA target of 4.5 billion US dollars by 2027 as planned.
Despite this, Goldman Sachs believes that after a recent field visit to the Wood River refinery, the stock showed a more attractive risk-reward ratio. The bank believes that the company is gradually improving the profitability of the refining business. The main driving factors include improving crude oil procurement, improving asset utilization, and reducing operating costs.
Goldman Sachs is also optimistic that management will continue to be committed to rewarding shareholders while strengthening the overall balance sheet strength. According to the bank's updated model, the company is expected to achieve its total debt target of 17 billion US dollars this year, while returning at least 50% of the adjusted operating cash flow to shareholders.
Prior to the announcement of the financial report, Goldman Sachs expects investors to focus on the following issues: (a) the overall fundamentals of the refining industry; (b) opportunities to further advance refining business improvement plans; (c) the latest developments in midstream business growth projects; and (d) capital allocation priorities.
PBF Energy
Goldman Sachs gave PBF Energy (PBF.US) a “neutral” rating, with a target price of $91. As earnings season begins, Goldman Sachs said it wants to know more about the company's capital allocation priorities. The bank specifically emphasized that the company's strong ability to generate cash flow is expected to significantly accelerate the deleveraging process.
In addition to the strong refining profit margin environment, investors' discussions surrounding the stock largely focused on the company's exposure to the price difference between light crude oil and heavy crude oil. Goldman Sachs notes that as the market expects oil production in Canada and Latin America to continue to grow, the widening spread of light and heavy crude oil prices has become the focus of market attention. The bank also wants management to further explain the company's strategy for dealing with renewable fuel obligations (RVO), particularly in an environment where RIN prices are high, how the company will manage related obligations.
CVR Energy
Goldman Sachs gave CVR Energy (CVI.US) a “sell” rating, and the target price was $50. Regarding CVI, Goldman Sachs notes that investors' discussions mainly focused on the stock's relative performance and the company's likely performance in the upcoming third-quarter results.
Although the fourth quarter is usually a period of weak seasonality, especially in the midmainland US, Goldman Sachs believes that profit forecasts are likely to remain at a high level. Factors supporting this judgment include low inventory levels, continued disruptions in global supply, and relatively resilient demand. Furthermore, discussions surrounding CVR Energy also focused on capital allocation priorities, particularly how companies arrange the pace of capital allocation between dividend payments, deleveraging, mergers and acquisitions, and capital expenditure.
Additionally, Goldman Sachs gave Delek US (DK.US) a “buy” rating with a target price of $83; it gave Par Pacific (PARR.US) a “buy” rating, with a target price of $90.