


IBM’s launch of IBM Ready for SAP Solutions puts SAP (XTRA:SAP) back in focus for investors, as the partnership showcases how SAP Cloud ERP is being used to modernize operations and prepare for wider AI use.
Despite a flurry of AI and cloud ERP announcements from SAP, the share price is around €184.62, with a 90-day share price return of 34.19% but a year-to-date share price decline of 8.58%. The 1-year total shareholder return is down 21.04%, compared with a much stronger 3-year total shareholder return of 52.70% and 5-year total shareholder return of 60.44%. This suggests long-term holders have seen gains even as recent momentum has cooled.
Scan SAP’s peers that are also leaning into AI-driven ERP and data platforms by running the hand-picked 91 AI infrastructure stocks as the next step in your research.
Recent weakness after a strong 90 day climb has left SAP appearing caught between a business leaning harder into AI driven ERP and a market that is questioning how much of that story is already in the price.
Most Popular Narrative: 15% Overvalued
Against a last close of €184.62, the most followed narrative anchors SAP’s fair value at €160. This implies the current price already bakes in richer expectations than that bearish camp is willing to underwrite, even with solid cloud demand in the background.
The numbers now imply a share price that assumes SAP turns strong cloud backlog and current cloud revenue into sustained value creation despite near term operating profit guidance reductions and AI driven cost headwinds.
See why 19 investors see SAP as 15% overvalued.
Result: Fair Value of €160 (OVERVALUED)
Still, if SAP’s AI assistants and Autonomous Suite agents deliver real productivity gains that support richer contracts, or recent data acquisitions integrate smoothly, this bearish margin story could appear too harsh.
Find out about the key risks to this SAP narrative.
Another View: SAP Through The P/E Lens
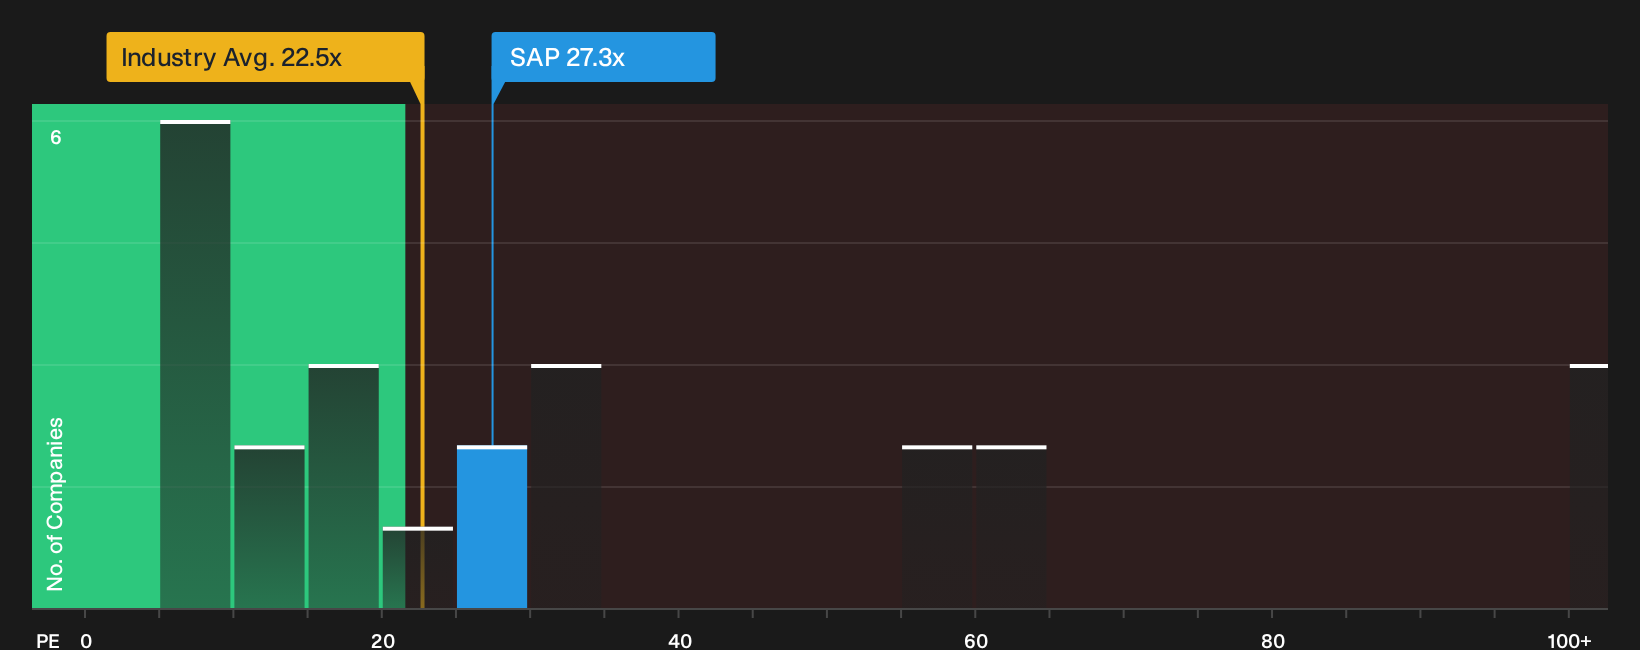
That €160 fair value comes from bearish analyst assumptions. A different lens uses SAP’s current P/E of 27.3x against a fair ratio of 35.3x. The business trades above European software peers at 22.5x and a peer set at 20.9x, yet below that fair ratio. Is this a valuation gap or a warning sign?
To pressure test what that richer P/E could mean for future upside or downside, it helps to see how the numbers stack up in a full breakdown, including peers, sector and the fair ratio trend, via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on SAP’s valuation story so far. If you want your own take, move fast and stress test the positives that investors are watching through the 3 key rewards.
Looking for more ideas beyond SAP?
If SAP has sharpened your thinking on valuation and risk, do not stop here. Broaden your watchlist now so you are not chasing the next move late.
- Target dependable income streams by scanning companies with strong yields and payout profiles through the 227 dividend fortresses.
- Hunt for quality at a discount by reviewing companies screened for solid fundamentals and attractive pricing via the 179 high quality undervalued stocks.
- Prioritize sleep-at-night holdings by focusing on businesses flagged for resilience and lower risk scores using the 225 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com