


Saia (SAIA) is back on investors’ radar after recent commentary highlighted two years of declining shipment volumes along with falling earnings per share and returns on capital, raising fresh questions about the freight carrier’s profit engine.
Recent trading shows that Saia’s 1-day share price return of 1.95% has not reversed the 30-day share price decline of 3.83% and the 90-day share price drop of 18.91%. The 1-year total shareholder return of 8.21% contrasts with a 3-year total shareholder return that is down 17.77%, suggesting shorter term momentum has softened as investors reassess the risks highlighted by weaker volumes and earnings.
Compare Saia’s recent stumbles in freight volumes with peers that still combine resilient demand and healthier balance sheets by scanning our curated list of list of solid balance sheet and fundamentals (25 results).
Saia’s weaker volumes and shrinking returns on capital point to real pressure in the freight operation, while the share price slide hints at a sentiment reset. How much of today’s valuation now reflects that tension between fundamentals and mood?
Most Popular Narrative: 21% Undervalued
At a last close of $341.26 versus a narrative fair value of $434.38, Saia is framed as underpriced by that widely followed thesis. The gap hinges on whether its heavier cost base can be worked harder through network maturity and pricing discipline.
The ongoing expansion and maturation of Saia's national terminal network, combined with densification of the 218 plus facilities added or upgraded since 2022, is still early in its ramp and is beginning to show operating ratio improvement at newer sites. This could support higher shipment volumes, revenue growth and better net margins as more terminals move from the low 90s operating ratio toward mature system levels.
See why 4 investors see Saia as 21% undervalued.
Result: Fair Value of $434.38 (UNDERVALUED)
Still, Saia’s higher wage and benefits bill, along with rising fuel and insurance costs, could squeeze margins if pricing and efficiency improvements fall short.
Find out about the key risks to this Saia narrative.
Another View: Saia Valuation Through Earnings Multiples
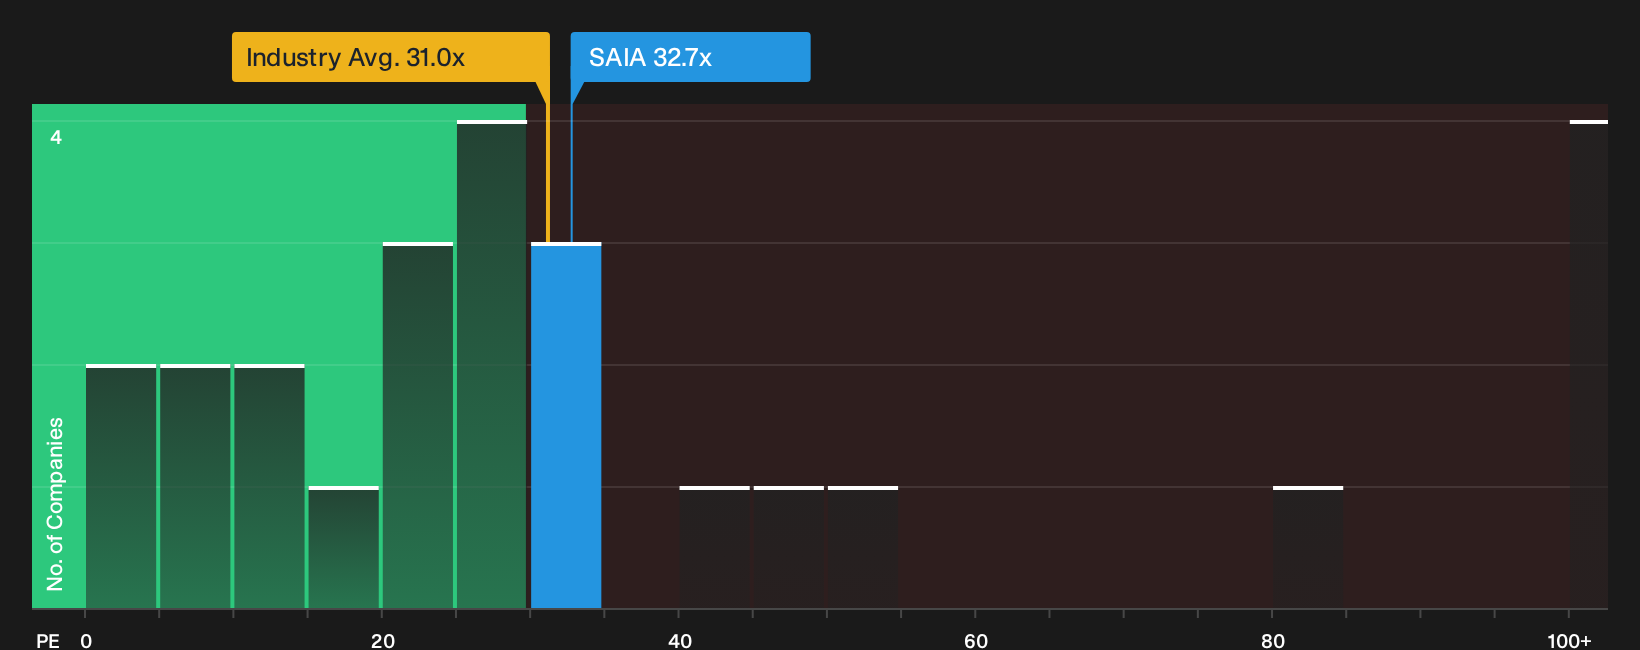
Saia may look underpriced against the $434.38 narrative fair value, yet the P/E ratio of 32.7x tells a tougher story. It sits slightly above the US Transportation industry on 31x and well above a fair ratio of 18.1x. That gap points to meaningful valuation risk if sentiment cools.
For a closer look at how earnings multiples stack up against fundamentals, and how that gap might close over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the current mood on Saia feels too cautious or too optimistic? Move quickly, review the underlying numbers yourself, then weigh them against the 2 key rewards.
Looking for more Saia investment ideas?
If Saia has you rethinking your watchlist, do not stop at one ticker. Broaden your options and stress test your thesis against other opportunities.
- Target potential mispricing by scanning a focused pool of quality ideas built to appear under fair value through the 27 high quality undervalued stocks.
- Prioritise resilience first and hunt for companies with sturdier finances and cleaner leverage profiles using the 31 resilient stocks with low risk scores.
- Get ahead of the crowd by reviewing financially sound businesses that receive less attention through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com