


Why Live Nation’s New Notes Matter For Equity Investors
Live Nation Entertainment (LYV) has just priced $730 million of 7.125% senior notes and €600 million of 6.125% senior notes due 2032, aimed at refinancing 2027 debt and supporting broader corporate uses.
For you as a shareholder, this kind of refinancing shapes the future interest bill, the maturity ladder, and the cash that stays available for running the live entertainment business rather than servicing older obligations.
Live Nation Entertainment shares trade at US$171.34, with the 7 day share price return of 2.69% pointing to some short term momentum. This is despite the 90 day share price return declining 4.7%, while the 3 year total shareholder return of 98.68% and 5 year total shareholder return of 70.64% keep the longer term picture positive.
Compare Live Nation Entertainment’s refinancing playbook with other companies reshaping their balance sheets by scanning our hand picked list of solid balance sheet and fundamentals (25 results) for your next idea.
Bulls see Live Nation Entertainment using this refinancing to extend its runway, while bears focus on the higher coupons and current loss making status. Which story does the valuation suggest you are really paying for?
Most Popular Narrative: 15% Undervalued
Live Nation Entertainment closed at $171.34, while the most followed narrative pegs fair value at $201.96 using a 9.76% discount rate. That gap only really makes sense if you think the venue and ticketing build out can turn current losses into meaningful earnings over time.
Ongoing buildout of Venue Nation arenas, including over 20 projects in construction or fully permitted and a planned 15 million fan capacity addition across 2026 and 2027, is set to increase owned infrastructure exposure and on site spending opportunities that can support higher revenue and improved net margins once these venues are fully contributing.
See why 20 investors see Live Nation Entertainment as 15% undervalued.
Result: Fair Value of $201.96 (UNDERVALUED)
Still, Live Nation Entertainment carries active antitrust and regulatory cases that could reshape Ticketmaster contracts and add legal costs if outcomes turn less favourable.
Find out about the key risks to this Live Nation Entertainment narrative.
Another View On Live Nation’s Valuation
The analyst narrative points to a fair value of $201.96 and calls Live Nation Entertainment undervalued. Our DCF work paints a more muted picture. The SWS DCF model estimates future cash flows at $169.99 per share, which is slightly below the current $171.34 price, so on this view LYV screens as mildly overvalued. Which lens do you trust more, the story tied to long term growth or the spreadsheet tied to modeled cash flows?
Look into how the SWS DCF model arrives at its fair value.
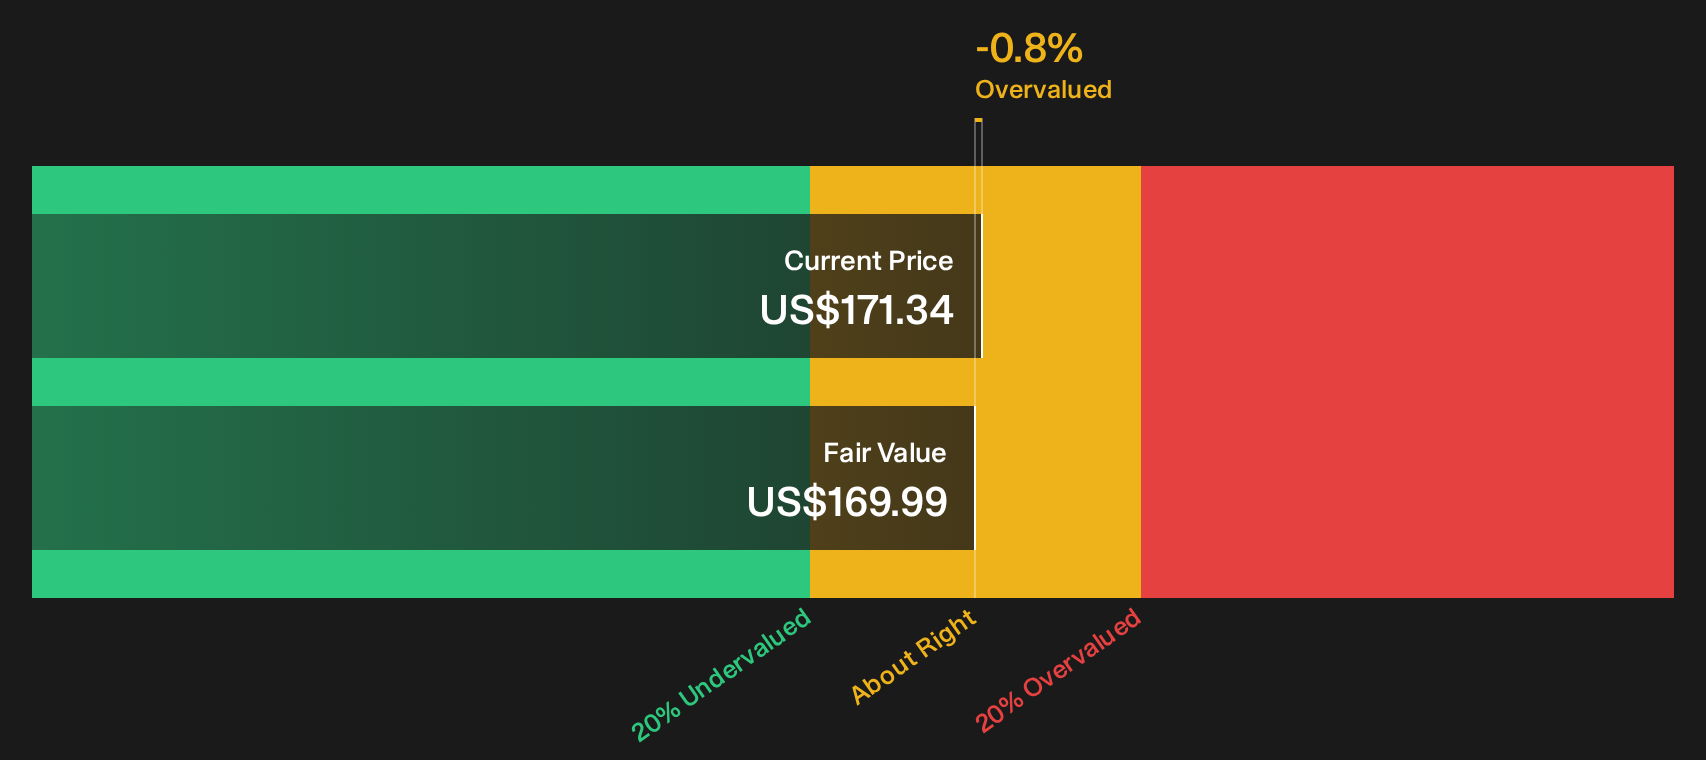
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Live Nation Entertainment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Live Nation Entertainment story so far. Act quickly, review the valuation work, and then weigh those positives yourself by checking the 1 key reward.
Looking for more investment ideas beyond Live Nation Entertainment?
If Live Nation Entertainment has you thinking harder about valuation and risk, do not stop at a single ticker. Broaden your watchlist and give yourself more options.
- Target steadier journeys by scanning 31 resilient stocks with low risk scores that aim to limit drawdowns while keeping your capital working.
- Hunt for mispriced potential by checking 20 high quality undiscovered gems with strong fundamentals that many investors may not be watching yet.
- Strengthen your core holdings by reviewing the 8 dividend fortresses that combine income potential with resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com