


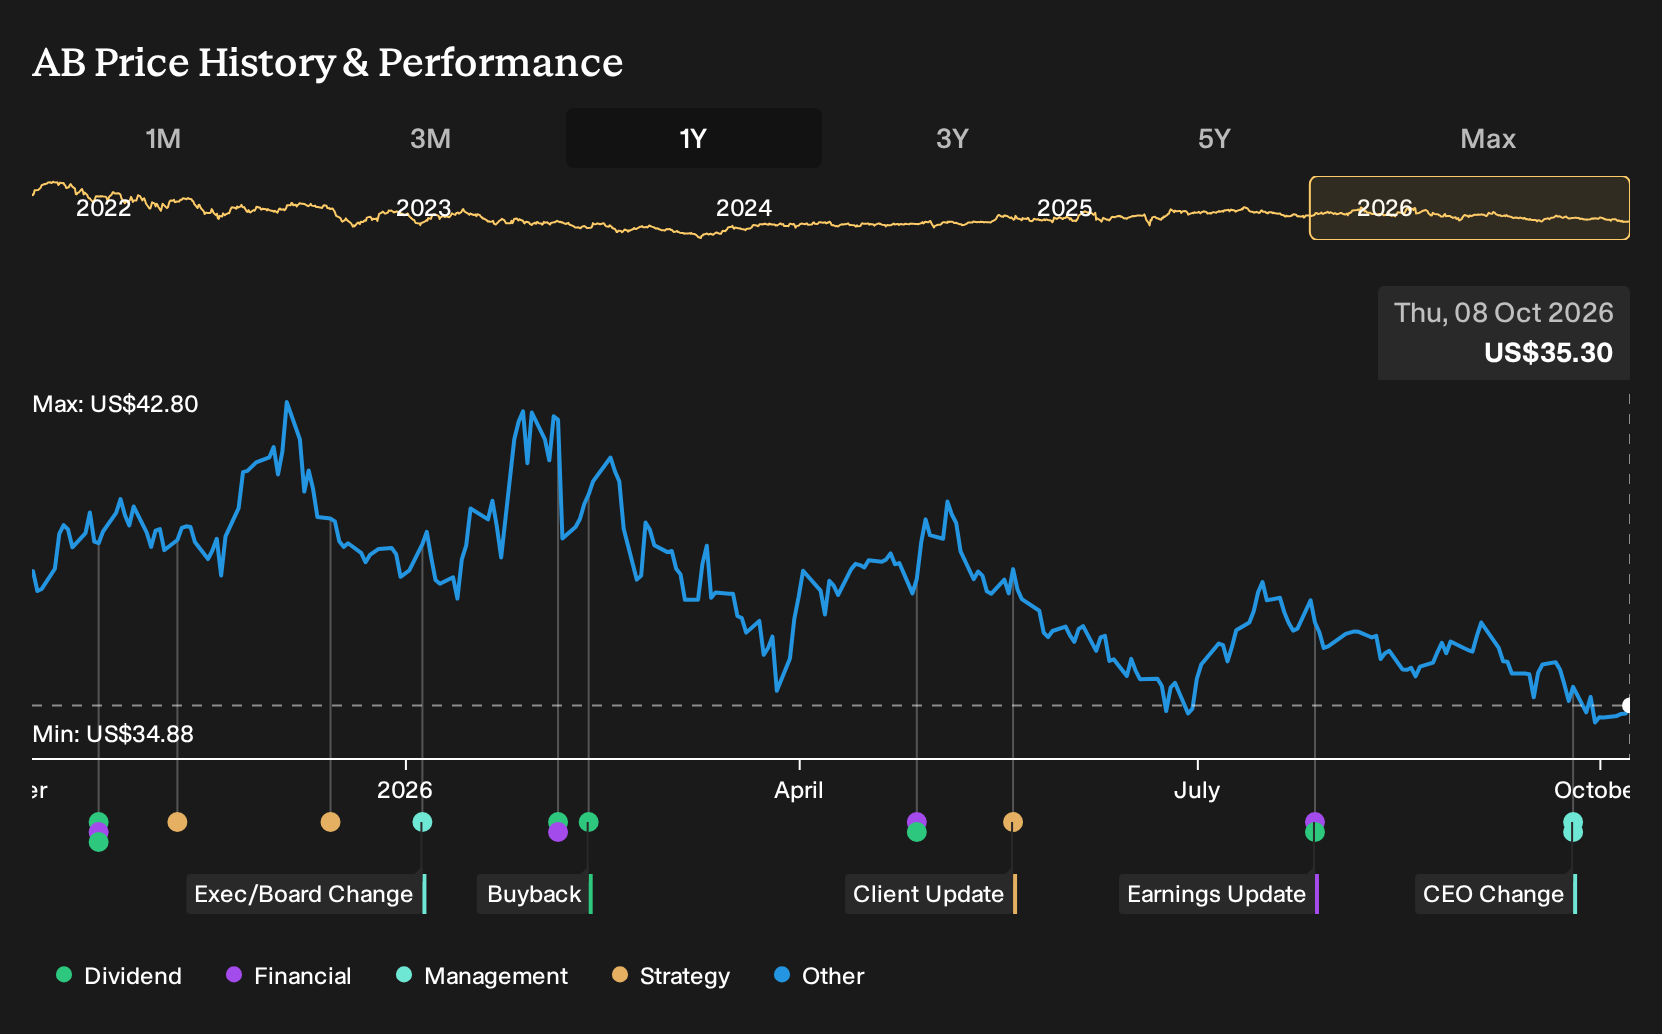
- AllianceBernstein Holding announced that Seth Bernstein plans to retire as CEO on March 31, 2027. Current President Onur Erzan is set to become chief executive and join the AB Board on April 1, 2027, extending his responsibilities across wealth, alternatives and distribution.
- Erzan’s track record inside AllianceBernstein Holding spans active ETF launches, growth in private credit and retirement solutions, and broader private wealth capabilities that reshape how the partnership serves ultra-high-net-worth families and institutional clients.
- We will now look at how AllianceBernstein Holding's investment narrative could shift with Onur Erzan’s planned move into the CEO role.
What Is AllianceBernstein Holding's Investment Narrative?
To own AllianceBernstein Holding, you need to believe this partnership can keep attracting sticky client assets across public markets, private credit, insurance mandates and ultra high net worth families, while running that platform with disciplined costs and capital light execution. The story leans on fee based revenue, relatively low capital intensity and an experienced bench that already manages US$919b of assets as of August 31, 2026.
The CEO handoff to Onur Erzan sits right in the middle of that thesis. He already runs private wealth, global private alternatives and distribution, which are key areas for future fee pools and pricing power. In the short term, the announcement itself does not change the biggest swing factors, such as pressure on earnings, a high dividend that is not well covered and the reliance on higher risk funding instead of deposits.
Even so, there is a less comfortable angle to this transition that hinges on...
There's only one way to know the right time to buy, sell or hold AllianceBernstein Holding. Head to Simply Wall St's company report for the latest analysis of AllianceBernstein Holding's Fair Value.
Exploring Other Perspectives
Fair value estimates for AllianceBernstein Holding from three members of the Simply Wall St Community cluster tightly between US$37.90 and US$38.29, so you are not seeing any extreme bargain or bubble calls here. These views also predate the CEO transition news, which could shift how some investors frame long term execution risk and opportunity.
Explore 2 other AllianceBernstein Holding fair value estimates, including one that suggests up to 8% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AllianceBernstein Holding research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AllianceBernstein Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AllianceBernstein Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond AllianceBernstein Holding?
Once you have a handle on AllianceBernstein Holding, it can help to compare it with a few other listed businesses that share similar qualities or offer very different risk profiles. The Simply Wall St Screener curates several focused sets of stocks that you can use to stress test your portfolio and spot fresh ideas that match your own return and risk preferences.
- For investors who care most about valuation support and quality fundamentals, scan through 27 high quality undervalued stocks that combine solid balance sheets with strong cash generation.
- If capital preservation and smoother drawdowns matter more to you than seeking very high returns, review a curated group of 31 resilient stocks with low risk scores and see which ones fit your comfort level.
- When you want a fresher angle away from widely followed giants, broaden your watchlist with a 20 high quality undiscovered gems that pair resilient financials with quieter market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com