


Atrium Ljungberg (OM:ATRLJ B) has drawn attention after a weaker recent share performance, with the stock down over the past month and past 3 months. This has prompted investors to reassess the Swedish property group.
The recent slide in Atrium Ljungberg’s share price, with the stock down 13.3% over the past month and 18.1% over 3 months, sits on top of a year to date share price return of down 32.9% and a 1 year total shareholder return of down 26.3%. Investors appear to be reassessing risk around the Swedish property sector, and that shift in sentiment has fed into weaker momentum for the shares, even as management continues to run a sizeable portfolio at a last close of SEK22.2.
Broaden your watchlist by comparing Atrium Ljungberg’s recent slide with a curated set of resilient real estate and infrastructure players using list of solid balance sheet and fundamentals (206 results).
Atrium Ljungberg now trades well below the average analyst target, yet the share price has fallen hard as sector worries build. Is that discount compensation for real risk, or a mispriced opportunity on Swedish bricks and mortar?
Most Popular Narrative: 24% Undervalued
On the most followed view of Atrium Ljungberg, a fair value of about SEK29.33 is set against a last close of SEK22.20, so the story hinges on whether that gap is backed by the underlying projects and balance sheet choices.
The completion and leasing of significant projects, such as the deal with Stockholm University of the Arts and the creation of a new block with a rentable area of 27,000 square meters, are expected to drive future rental income growth. This is due to securing long-term leases that provide stable cash flows and contribute to increased earnings.
See why 2 investors see Atrium Ljungberg as 24% undervalued.
Result: Fair Value of SEK29.33 (UNDERVALUED)
Still, the narrative around Atrium Ljungberg could crack if higher interest costs continue to affect earnings or if rising office vacancies drag rental income lower.
Find out about the key risks to this Atrium Ljungberg narrative.
Another View: Multiples Paint A Less Generous Picture For Atrium Ljungberg
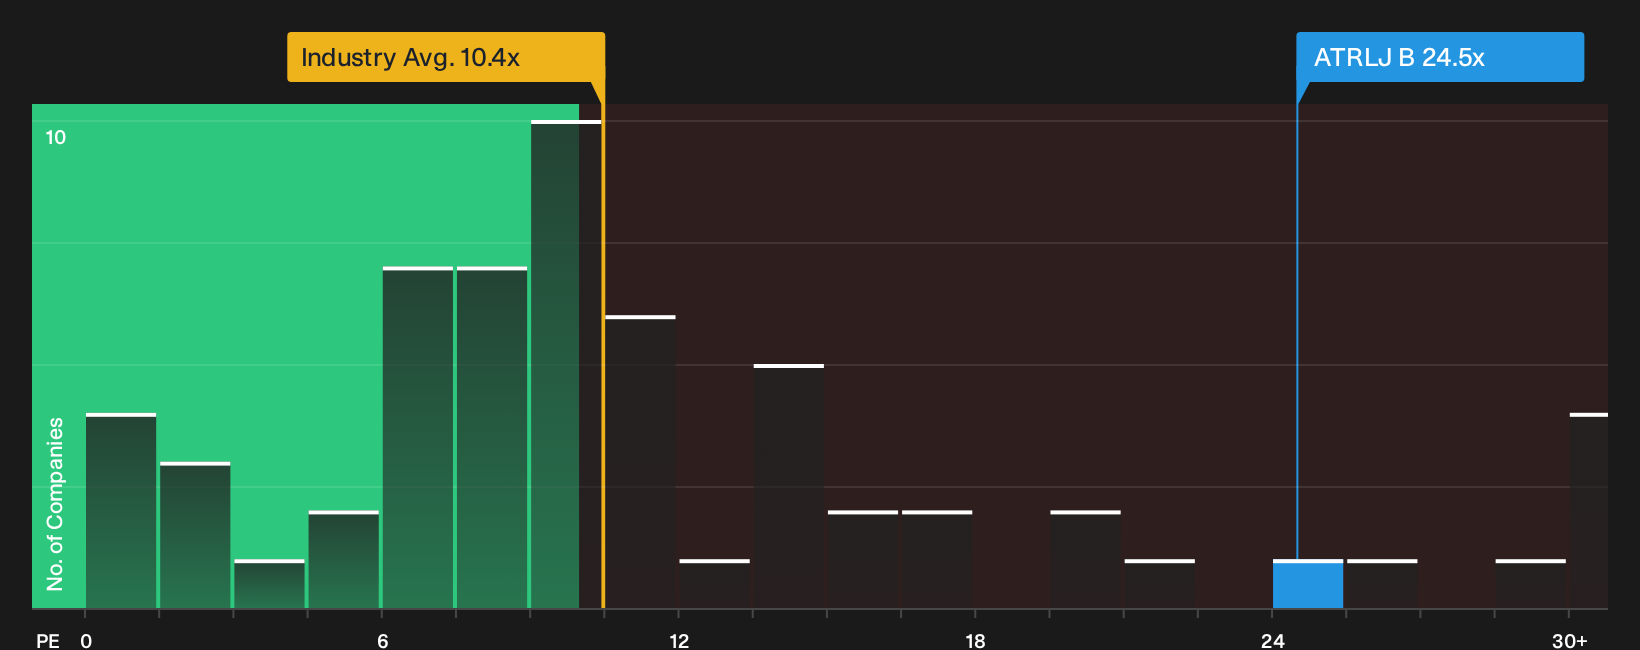
The analyst narrative frames Atrium Ljungberg as around 24% undervalued at SEK22.20 versus a SEK29.33 fair value. On simple earnings multiples, the picture is colder. The current P/E of 24.5x is higher than the Swedish real estate sector at 10.5x and above a fair ratio of 22.9x, which leans toward valuation risk rather than a clear bargain. Which signal do you trust more when real cash flows and sector pressure collide?
To pressure test that richer P/E against detailed earnings, margin and balance sheet work, it is worth going through our full valuation breakdown before taking a view on the gap to the analyst target. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Atrium Ljungberg is clearly tense, so move quickly, interrogate the numbers yourself, and weigh both the upside and the risk signals. To see the full picture before deciding how you feel about the stock, review the 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Atrium Ljungberg?
If Atrium Ljungberg has you rethinking your portfolio, now is the right time to widen your opportunity set using focused screeners built around clear fundamentals.
- Target potential mispricing by scanning a curated pool of quality candidates through the 180 high quality undervalued stocks.
- Strengthen your income stream by focusing on reliable payers using the 227 dividend fortresses.
- Dial back portfolio risk by concentrating on sturdier businesses with the 225 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com