


- SpaceX agreed to acquire a nationwide low band 800 MHz spectrum portfolio for Starlink Mobile. This could enable a hybrid satellite terrestrial network that competes more directly with established U.S. wireless carriers such as T-Mobile US across coverage, especially in rural and emergency focused segments.
- The planned build out of Starlink using low band spectrum raises fresh questions for T-Mobile US about how to defend higher margin enterprise, roaming and rural connectivity revenue, where satellite based service may appeal to governments, corporates and remote consumers that value near universal coverage.
- We will look at how T-Mobile US's investment narrative holds up as SpaceX's new low band spectrum position reshapes competitive coverage.
T-Mobile US Investment Narrative Recap
To own T-Mobile US today, you need to believe the firm can keep turning its 5G reach, broadband push and AI projects into higher value postpaid and home internet relationships, while keeping churn under control as legacy plans are retired. The SpaceX spectrum move does not alter that near term execution test; it still centers on customer retention through price changes.
The biggest short term swing factor remains whether plan modernization and any bill pressure trigger more disconnects or heavier promotions. The largest risk is now compounded by fresh satellite competition from Starlink in rural and emergency use cases, which may gradually pressure roaming, rural and enterprise economics if adoption scales.
Against that backdrop, the joint venture between T-Mobile US, AT&T and Verizon to expand satellite supported coverage in underserved areas looks directly relevant. It gives T-Mobile a way to answer investor questions about coverage gaps that Starlink Mobile is targeting, while keeping existing carrier satellite deals intact and focused on direct to device access.
For catalysts, execution inside this JV will sit alongside T-Mobile US broadband and fiber goals, AI driven cost savings and spectrum plans. Results could support the case that T-Mobile maintains competitive network performance and rural reach even as SpaceX expands its offerings, while slower progress could leave more of the coverage narrative with Starlink.
T-Mobile US' current analyst narrative points to revenue of US$104.8b and earnings of US$17.9b by 2029. This projection is based on 4.4% yearly revenue growth and an earnings increase of about US$7.3b from US$10.6b today.
Uncover why T-Mobile US' fair value indicates a 42% potential upside to its current price, which could close faster than many investors expect.
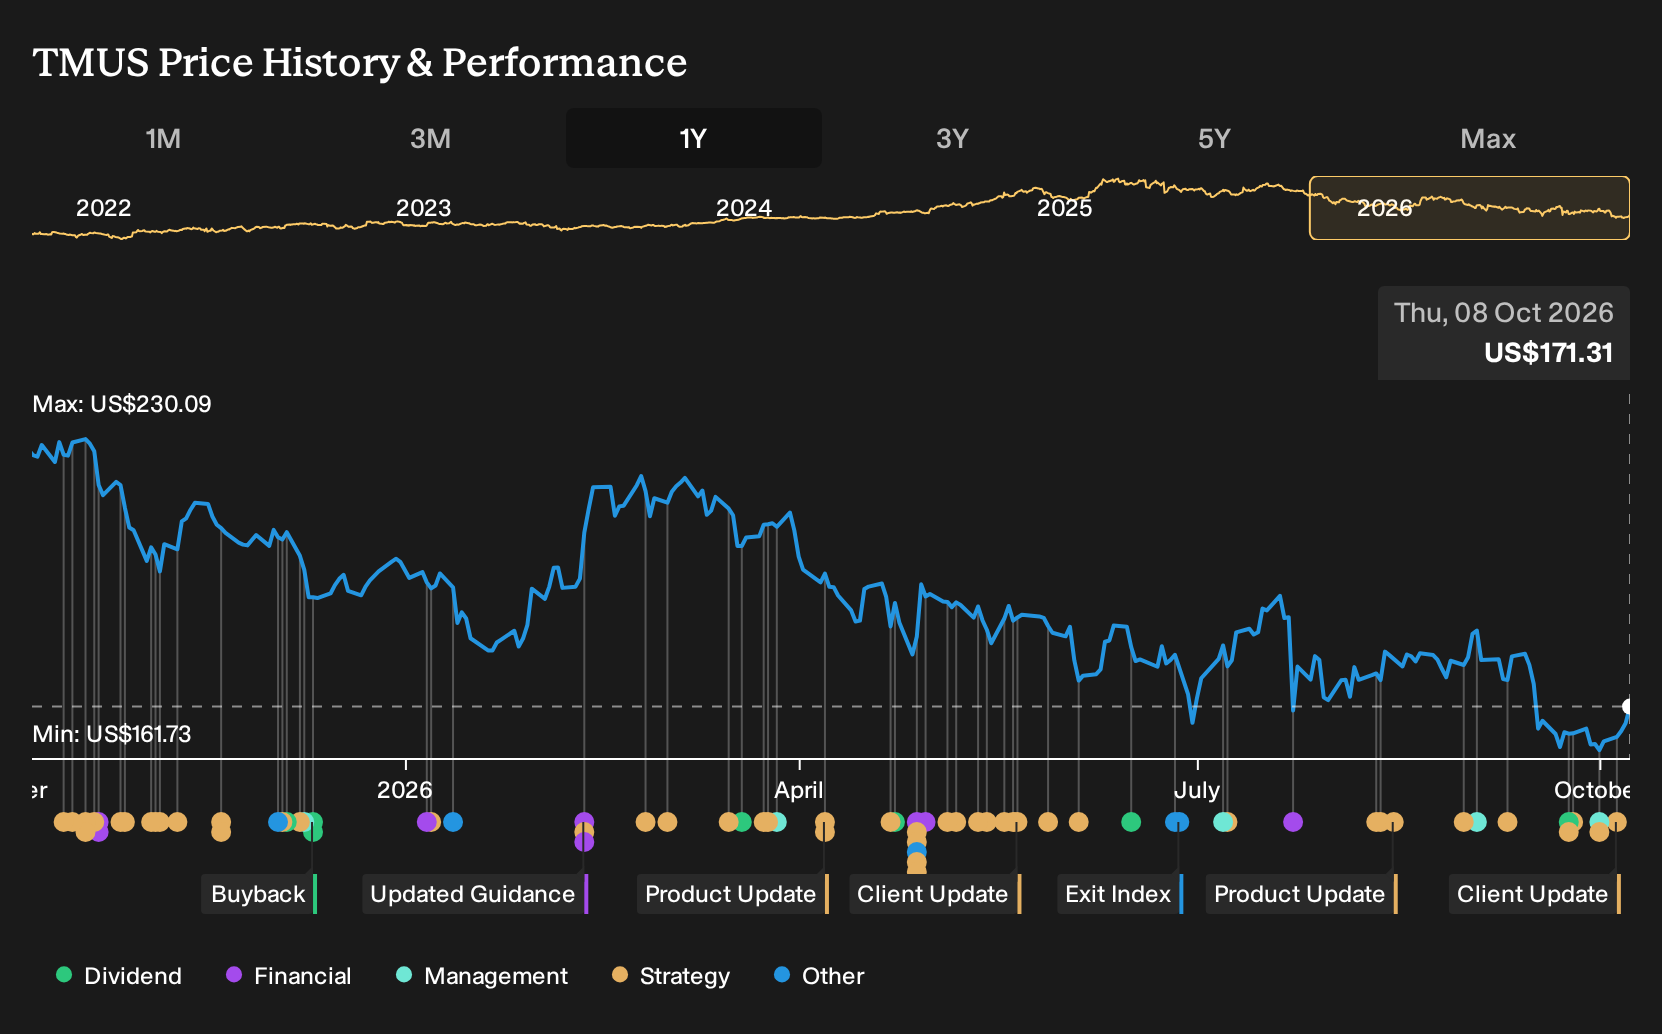
Exploring Other Perspectives
One alternate angle focuses on T-Mobile US adjacencies such as T-Ads and data partnerships. Some analysts viewed these as meaningful, with forecasts of about US$106.4b in revenue and US$21.5b in earnings by 2029. Fresh deals like the Vistar DOOH partnership might support that optimistic narrative, or prompt analysts to reconsider it entirely.
Explore 2 other T-Mobile US fair value estimates, including one that suggests as much as 242% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your T-Mobile US research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for T-Mobile US. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate T-Mobile US' overall financial health at a glance.
Looking for more T-Mobile US investment ideas?
If you want to pressure test your view on T-Mobile US, it helps to line it up against other opportunities with different risk and earnings profiles. The Simply Wall St Screener lets you scan the market quickly and focus on companies that match what you care about most, whether that is stability, income or underappreciated potential.
- If capital protection ranks high for you, start with a basket of companies that score well on balance sheet strength and resilience using our 31 resilient stocks with low risk scores.
- For investors hunting for mispriced opportunities backed by solid fundamentals, compare T-Mobile US with a curated 20 high quality undiscovered gems that might not yet be on everyone's radar.
- If consistent financial footing is your priority, scan a list of solid balance sheet and fundamentals (25 results) and see which businesses combine healthy finances with fundamentals that match your checklist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com