


- RTX, through its Raytheon segment, recently secured a five year U.S. Navy contract valued up to US$24.4b for Standard Missile 6 interceptors, alongside an US$11.6m contract modification for Rolling Airframe Missile components and continued investment in missile propulsion capacity.
- The cluster of long duration munitions awards and capacity build out gives RTX unusually strong visibility on future defense production workload, as well as related cost, staffing and supply chain planning needs.
- This article examines how RTX's long term SM 6 production agreement may influence the investment narrative around backlog quality and execution.
RTX Investment Narrative Recap
To own RTX, you need to be comfortable with a story driven by large, long duration defense and aerospace contracts and heavy upfront investment in capacity. The recent multi year SM 6 award and RAM contract tweak mainly reinforce what is already central to the thesis: multi year backlog conversion and a fuller missile production pipeline.
The key near term swing factor remains RTX execution on supply chain relief and factory throughput, so that its record US$289b backlog and higher 2026 guidance translate into cash on time. The biggest risk still sits in defense budget timing and potential reprioritisation, combined with high capital and engineering spend that may weigh on free cash flow if programs slip.
The SM 6 agreement up to US$24.4b looks like the cleanest link to this story. It ties directly into earlier commentary about five long term munitions frameworks where volumes may step up, and it strengthens the case that Raytheon’s missile franchise has years of contracted work to work through as capacity ramps.
For you as a shareholder, the operational question is straightforward. Can RTX qualify enough suppliers, expand in house propulsion and electronics output, and keep unit costs under control so these bigger missile lots and Tomahawk and AMRAAM deals show up as higher margins rather than just higher working capital and capex?
RTX’s current analyst script points to US$112.3b in revenue and US$10.9b in earnings by 2029, based on forecast top line expansion of 6.3% a year and an increase from US$7.7b in earnings today to that higher consensus level, which is an increase of about US$3.2b from current earnings.
Uncover why RTX's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
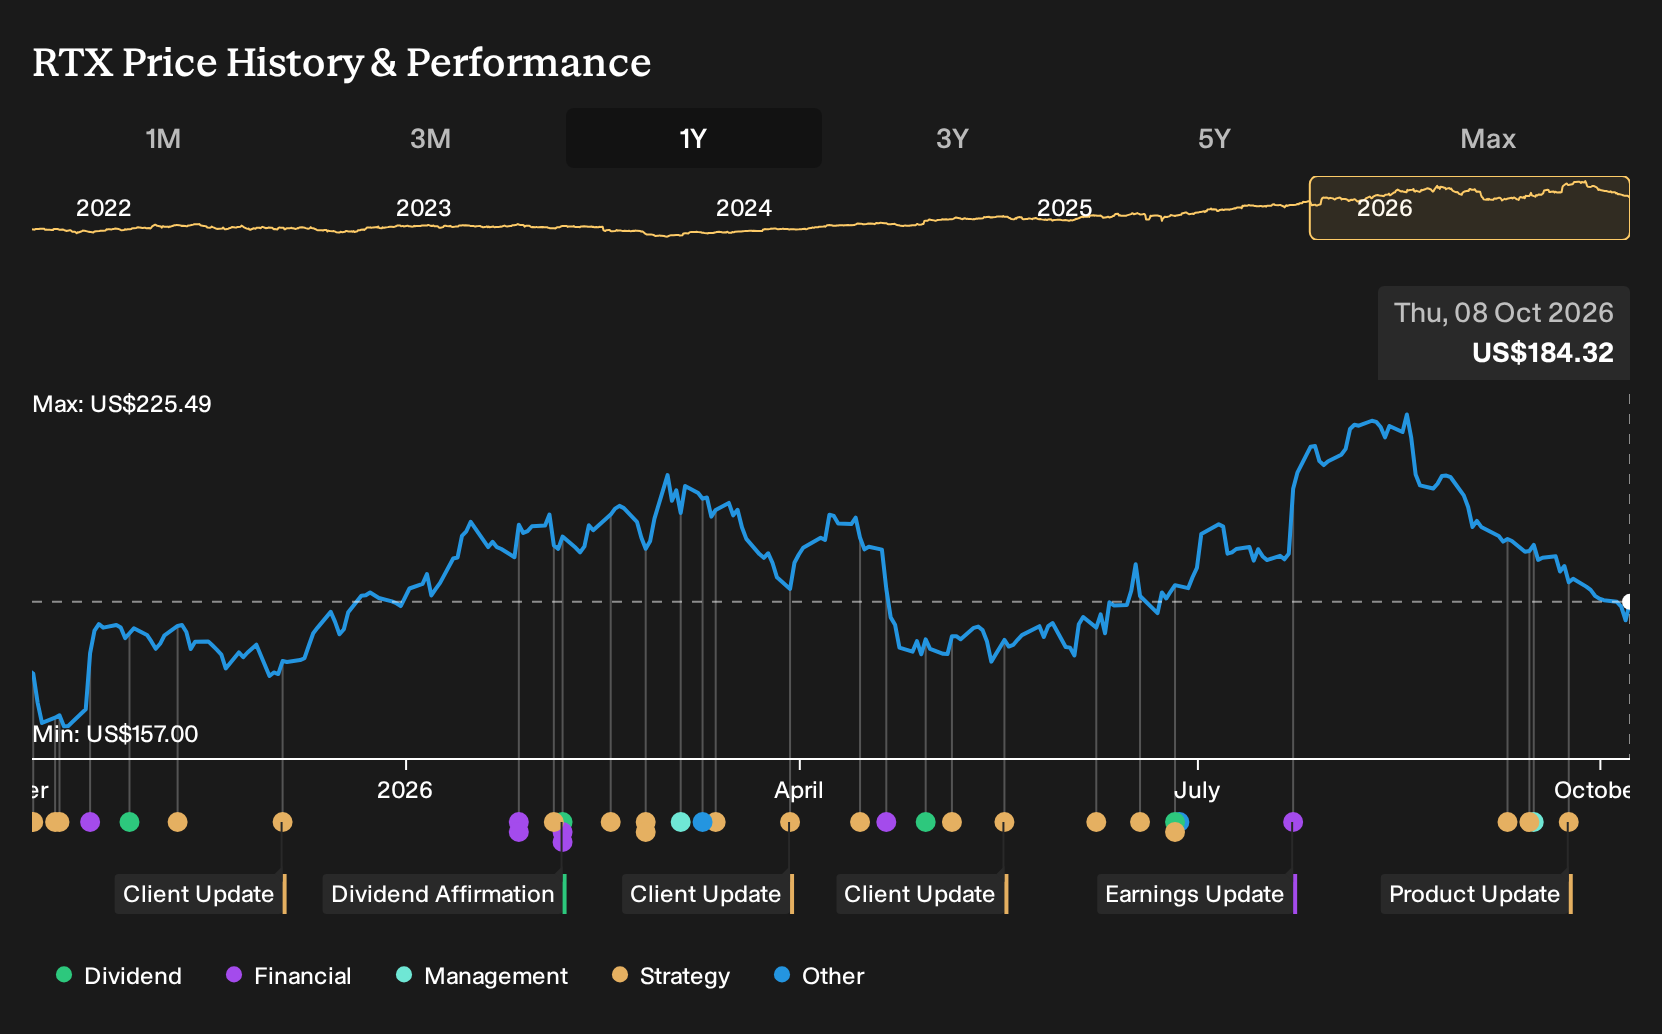
Across three fair value estimates from the Simply Wall St Community, RTX screens in a tight US$215.8b to US$234.8b band, which still sits above a share price that recently closed at US$180.26. Those private investor models sit beside real risks around tariffs, defense budget shifts and heavy 2026 capex, so you should weigh multiple viewpoints.
Explore 2 other RTX fair value estimates, including one that suggests up to 27% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and forming your own view.
- A great starting point for your RTX research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for RTX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RTX's overall financial health at a glance.
Looking For More Investment Ideas Beyond RTX?
Once you have a view on RTX, it often helps to compare it with other opportunities that share some of the same qualities, whether that is balance sheet resilience, cash flow support or potential mispricing. The Simply Wall St Screener can help you quickly filter for stocks that fit the kind of profile you are looking for.
- If you want a shortlist of potential mispriced opportunities with stronger fundamentals, start with a focused set of 27 high quality undervalued stocks that already clear basic quality checks.
- For investors who care about income and payout stability, use the screener to zero in on 8 dividend fortresses that put cash returns front and centre.
- If capital preservation matters most to you, filter for sturdier balance sheets and steadier metrics with a curated list of solid balance sheet and fundamentals (25 results) that can anchor a more defensive watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com