


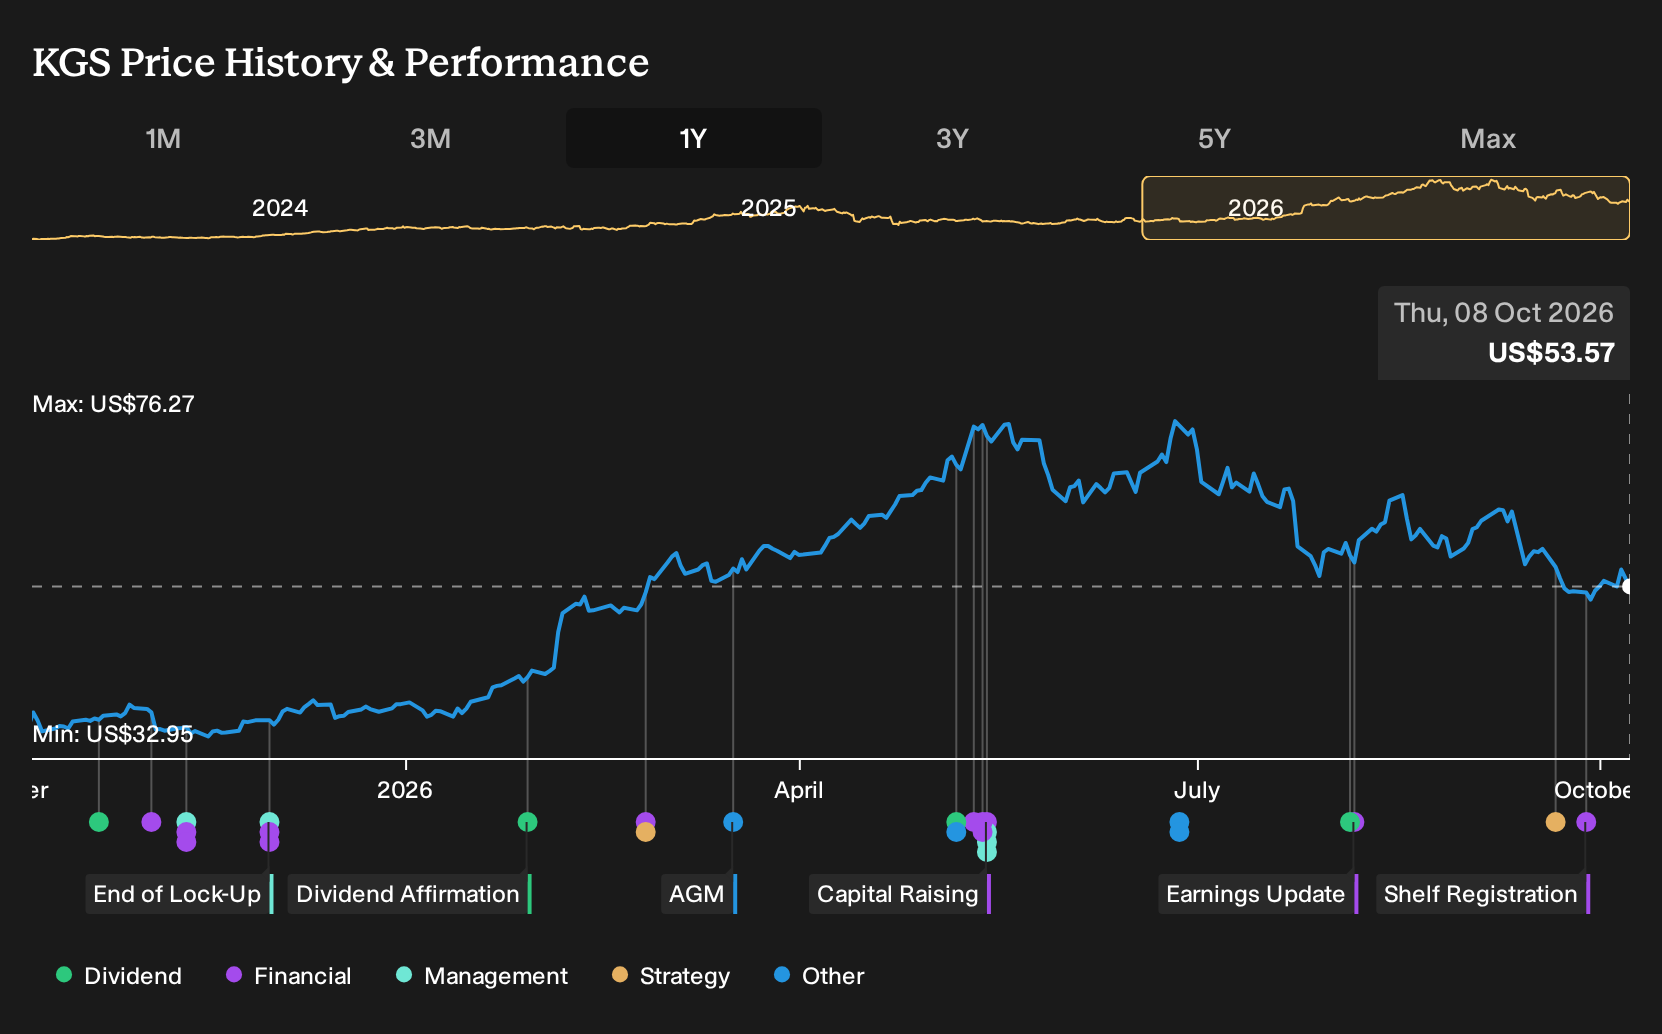
- Kodiak Gas Services recently filed a US$127.1 million shelf registration for up to 2,401,278 common shares and secured a six year, 76 megawatt power supply agreement with a West Texas data center operator.
- The data center power contract gives Kodiak Gas Services another long term, contracted revenue source that directly supports management’s plan to scale a 2 gigawatt power fleet alongside its compression business.
- We will now examine how Kodiak Gas Services' investment narrative is influenced by the new six year West Texas data center contract.
Compare Kodiak Gas Services' data center power push with other potential infrastructure beneficiaries by scanning our curated list of 43 power grid technology and infrastructure stocks for your watchlist.
Kodiak Gas Services Investment Narrative Recap
To own Kodiak Gas Services, you need to believe it can turn a compression focused operation into a larger power and gas infrastructure platform without letting costs outrun contract growth. The six year, 76 megawatt data center deal supports that story by adding contracted power volume, but it does not change the near term reality of tight labor markets and lube oil cost pressure.
The most important short term catalyst is execution on high margin compression and early power projects that can support earnings and free cash flow after a Q2 2026 miss. The biggest risk remains that higher operating expenses and labor constraints in the Permian dilute margins enough to slow reinvestment into both the compression and power fleets.
The shelf registration for roughly US$127.1 million in common stock matters here because Kodiak Gas Services has an ambitious plan for compression horsepower additions and a 2 gigawatt power fleet. Extra equity capacity can give the business another funding option as it works to secure more long duration data center and midstream power contracts.
Access to potential equity capital does not remove the core execution tests. Management still has to show it can deploy capital into compression and behind the meter power projects at returns that justify dilution, while keeping dividends and interest obligations manageable. For you, the link between that shelf, future contract wins, and progress on margins will likely be the key thing to watch.
Kodiak Gas Services is modeled to reach about US$2.2b in revenue and US$513.3m in earnings by 2029, which reflects analyst assumptions of roughly 17.2% yearly top line growth and an earnings increase of about US$435m from roughly US$78.3m today.
Uncover why Kodiak Gas Services' fair value indicates a 54% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses less on cost pressure and more on how Kodiak Gas Services could lean into long duration contracts. Bullish analysts were already modeling revenue of about US$2.4b and earnings near US$643.7m by 2029 before this shelf and data center deal. If you think differently, compare your view with those expectations and consider how fresh contracts might reset those assumptions.
Explore 3 other Kodiak Gas Services fair value estimates, including one that suggests up to 332% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kodiak Gas Services research is our analysis highlighting 3 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Kodiak Gas Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kodiak Gas Services' overall financial health at a glance.
Looking For More Ideas Beyond Kodiak Gas Services?
If you want to stress test your thesis on Kodiak Gas Services, compare it with other potential opportunities using the Simply Wall St screener. Lining up different types of businesses side by side can help you see whether this stock still earns a place in your watchlist or whether other setups look more compelling for your goals and risk tolerance.
- For investors who care most about valuation support and quality, scan through 27 high quality undervalued stocks that combine solid fundamentals with more conservative pricing.
- If capital preservation and steadier profiles matter more to you, filter the market using our 31 resilient stocks with low risk scores and see which companies score better on resilience.
- When you want to focus on balance sheet strength and underlying business durability, shortlist candidates from the list of solid balance sheet and fundamentals (25 results) to round out your research list.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com