


Mirum Pharmaceuticals has seen its share price swing sharply in recent years, which puts a spotlight on a basic question for investors who care about fundamentals: Do Mirum Pharmaceuticals' current sales and revenue prospects justify where the stock trades today?
- Over the past 5 years the stock has returned about 3.8x, which raises the question of how much of that move is supported by its sales base rather than changing sentiment alone.
- Regulatory progress for Atebrioz in fibrodysplasia ossificans progressiva and positive late stage data for brelovitug in chronic hepatitis delta virus can influence how quickly Mirum converts its pipeline into commercial revenue and cash generation.
- The analysts covering Mirum Pharmaceuticals have run their own numbers. See what analysts think Mirum Pharmaceuticals's shares could be worth.
The issue now is whether Mirum Pharmaceuticals' current share price is adequately explained by the level and trajectory of its sales.
If you are weighing Mirum Pharmaceuticals after the Atebrioz approval and brelovitug data, it can help to compare it against a wider set of 27 high quality undervalued stocks.
Does Mirum Pharmaceuticals Look Fairly Valued on Sales?
P/S fits Mirum Pharmaceuticals because investors are paying more attention to current and potential sales than to earnings or book value right now.
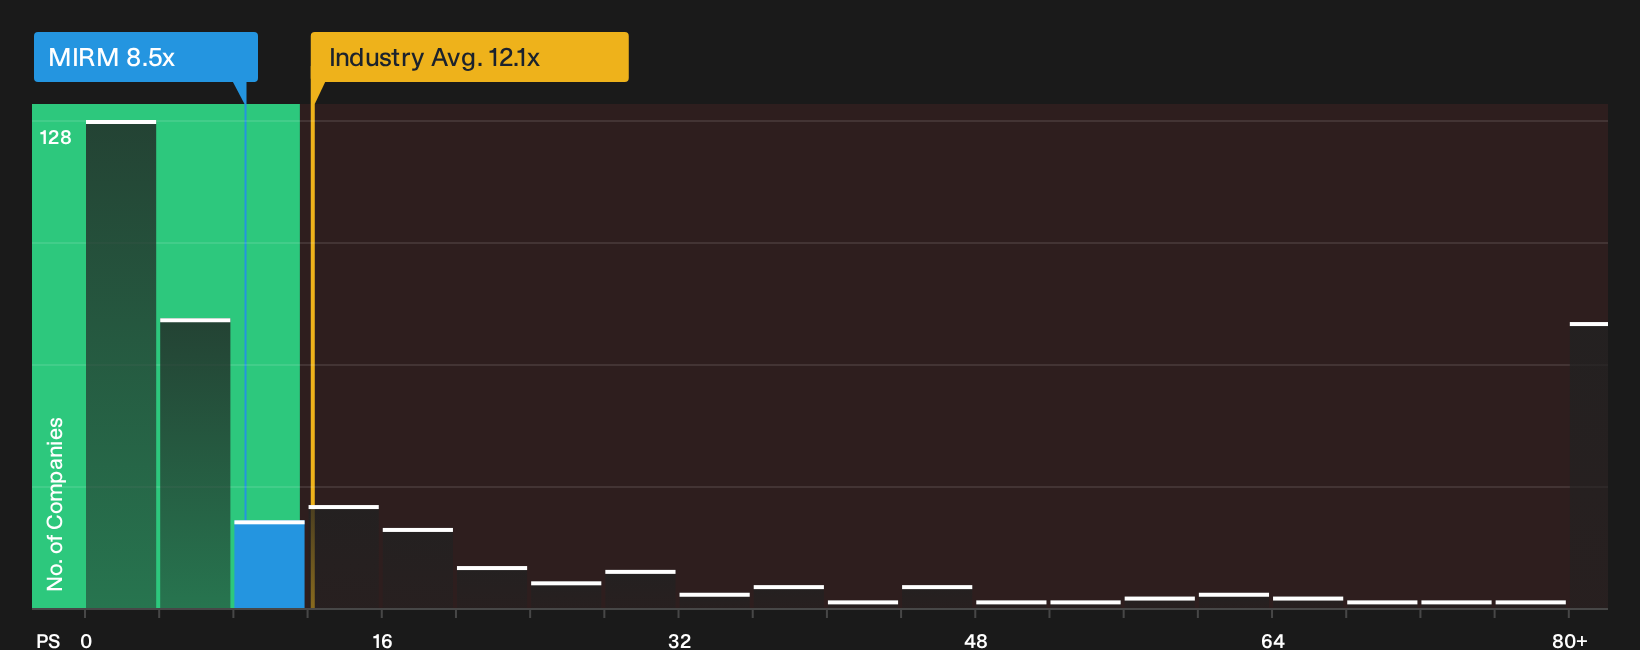
The stock trades on a P/S of about 8.5x, which is below the Biotechs industry average of roughly 12.1x and the peer group on about 12.7x. When compared with a tailored fair multiple that reflects Mirum's risk profile and revenue outlook, the current ratio lands close to where that model would expect. As a result, the absolute discount to sector averages appears less clear cut.
Because Atebrioz just secured FDA approval and brelovitug produced positive late stage data, this P/S level suggests the market already prices in a meaningful portion of those assets without pushing Mirum Pharmaceuticals to a clear premium over peers. Explore the numbers behind Mirum Pharmaceuticals's P/S valuation.
The Mirum Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Mirum Pharmaceuticals valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the current P/S to look too low or too high. Instead of giving a single output from a ratio or model, Narratives describe the future business conditions that number implies so you can later judge whether Mirum Pharmaceuticals' progress is tracking that path. They sit on Simply Wall St's Community page for investors who want that extra layer of context.
One of the top community narratives on Mirum Pharmaceuticals: 44% undervalued
"Broader patient identification, international expansion, and supportive reimbursement environments are driving sustained revenue growth and improving margins for Mirum's portfolio..."
Discover why this Narrative puts Mirum Pharmaceuticals at 44% undervalued.
One more Mirum Pharmaceuticals question that valuation alone cannot answer
Price to sales, pipelines and peer comparisons only tell part of the story, because Mirum Pharmaceuticals also has a set of risk checks that could change how you view everything discussed so far. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com