


SK hynix (NasdaqGS:SKHY) moved into focus after its US flash memory arm Solidigm chose Goldman Sachs and Morgan Stanley to lead a planned IPO that could raise about US$10b and value the unit near US$100b.
Short term momentum for SK hynix has cooled, with the share price falling 4.35% over the last day and 11.89% over the past week. The 90 day share price return of 1.48% indicates only modest progress after earlier gains tied to rising expectations for memory demand and the Solidigm IPO story.
Scan how SK hynix compares with other chip makers reacting to the same memory and IPO story by reviewing our hand picked 91 AI infrastructure stocks.
SK hynix now trades well below both analyst targets and intrinsic value estimates. The real puzzle is where fair value actually clusters across that spread.
Preferred P/E of 7.6x: Is it justified?
Valuation screens flag SK hynix as inexpensive on earnings, with a P/E of 7.6x against a US Semiconductor industry average of 50.3x and a peer group near 61x. That gap sits alongside a last close of $170.50 and keeps the stock in the conversation for investors watching the Solidigm IPO and the broader memory cycle.
The P/E ratio compares what you pay today for each dollar of current profit. For a chip maker like SK hynix, this metric links the share price directly to earnings power from DRAM, NAND and related products, which is often how investors frame value in semiconductor cycles.
SK hynix pairs that low P/E with very high reported profitability and strong forecasts. Return on equity is described as outstanding at 61.7%, net profit margins are currently 85.6% compared with 37.4% last year, and earnings have grown very rapidly over the past year relative to both its own 5 year average and the broader Semiconductor industry. Forecasts also point to revenue growth of 30.5% per year and earnings growth of about 26.9% per year, both ahead of US market expectations, which suggests the earnings base the P/E rests on is not static in analysts’ models.
Compared with the sector, the compression is stark. A P/E of 7.6x versus a 50.3x industry average and a 61x peer average signals that the market is pricing SK hynix far more cautiously than many US listed chip companies despite stronger recent earnings growth than the Semiconductor industry and a forecast return on equity of 54% in three years. That contrast raises the question of whether investors are giving enough credit to its recent profitability and growth profile.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 7.6x (UNDERVALUED).
Still, the story can break if Solidigm’s IPO pricing or timing disappoints, or if memory demand softens and puts current earnings power under pressure.
Find out about the key risks to this SK hynix narrative.
Another view of SK hynix value
The earnings based valuation paints SK hynix as cheap, yet the SWS DCF model goes further and values future cash flows at $545.07 per share against a current price of $170.50. That is a very wide gap. The question is whether the cash flow story or the earnings snapshot proves closer to reality for long term holders.
Look into how the SWS DCF model arrives at its fair value.
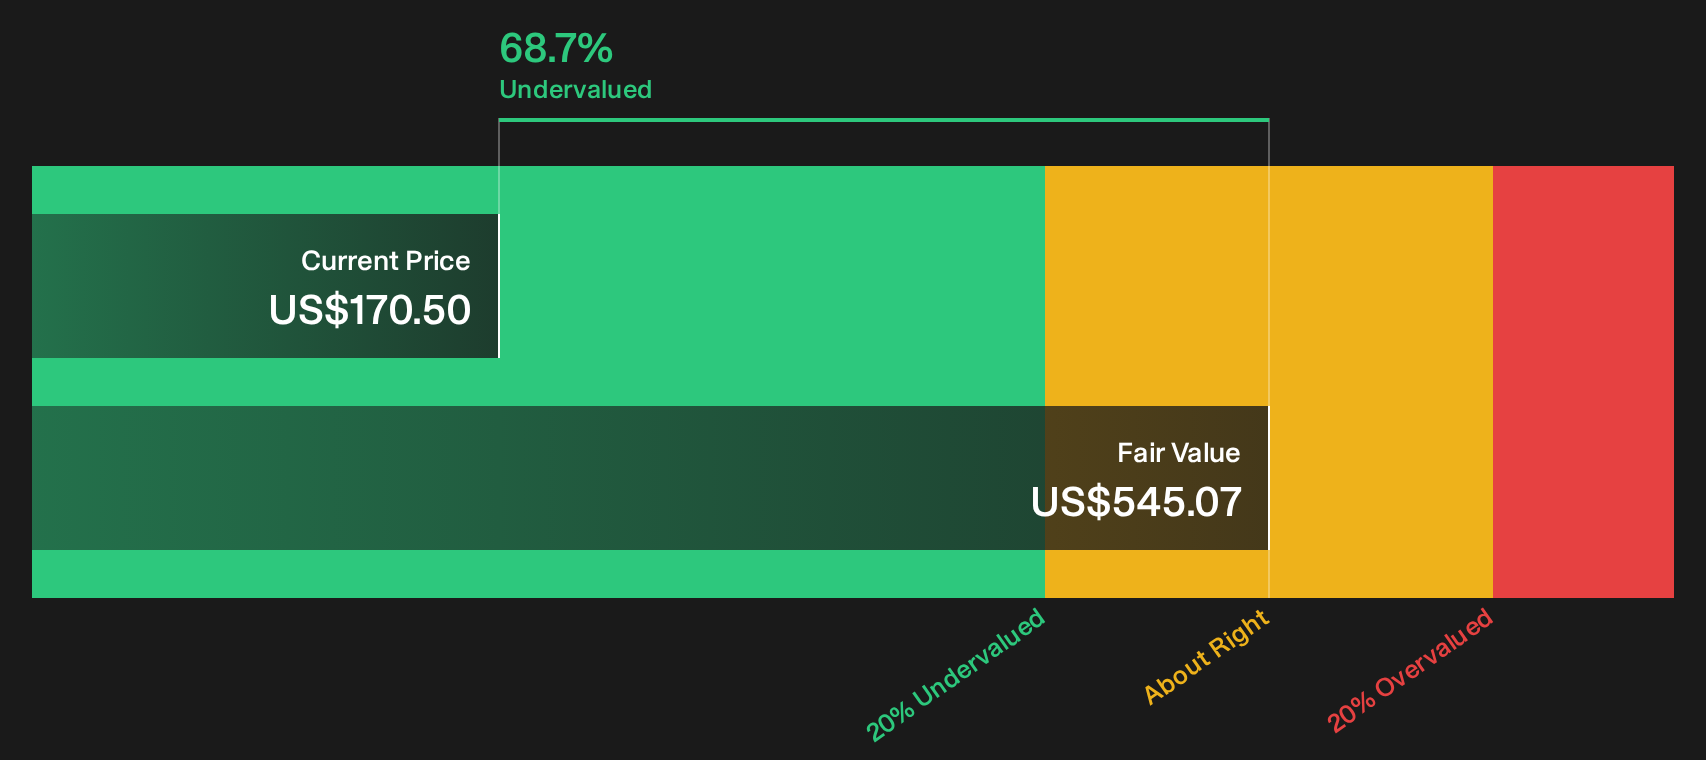
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SK hynix for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around SK hynix is mixed, with sharp valuation signals on one side and uncertainty around Solidigm and memory demand on the other. Review the full picture for yourself through 3 key rewards and 2 important warning signs
Ready for more SK hynix style ideas?
If SK hynix has sharpened your focus on valuation and quality, do not stop here. Broaden your watchlist with fresh opportunities that match your own risk and income goals.
- Explore resilient compounding potential by scanning our high quality value opportunities through the 27 high quality undervalued stocks.
- Build steadier income streams by focusing on reliable payout candidates using the 8 dividend fortresses.
- Reduce portfolio stress by concentrating on financially robust businesses with the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com