


Analog Devices has experienced a strong multi year share price run, and with earnings now in sharper focus, the question is whether today’s valuation still lines up with what the business is actually earning. With fresh headlines around AI focused acquisitions and record profitability, the stock’s earnings power has become the key reference point for anyone trying to judge the current price.
- Over the past 5 years the stock has returned 162.4%, which puts real pressure on the earnings profile to support a much higher equity value than in the past.
- The planned US$1.35b cash acquisition of Alif Semiconductor, plus a possible US$200m earn out, can reshape expectations for AI related earnings and may influence how investors weigh Analog Devices' ability to convert revenue into durable profits.
- Your read on Analog Devices is one view; the desks covering it have another. See what analysts think Analog Devices's shares could be worth.
The stock's next move may depend on whether Analog Devices' current earnings are strong and resilient enough to justify the price implied by that recent performance and deal activity.
If you are weighing whether Analog Devices' earnings justify its current share price, it can help to compare that question across 91 AI infrastructure stocks.
Has Analog Devices Run Too Far on Earnings?
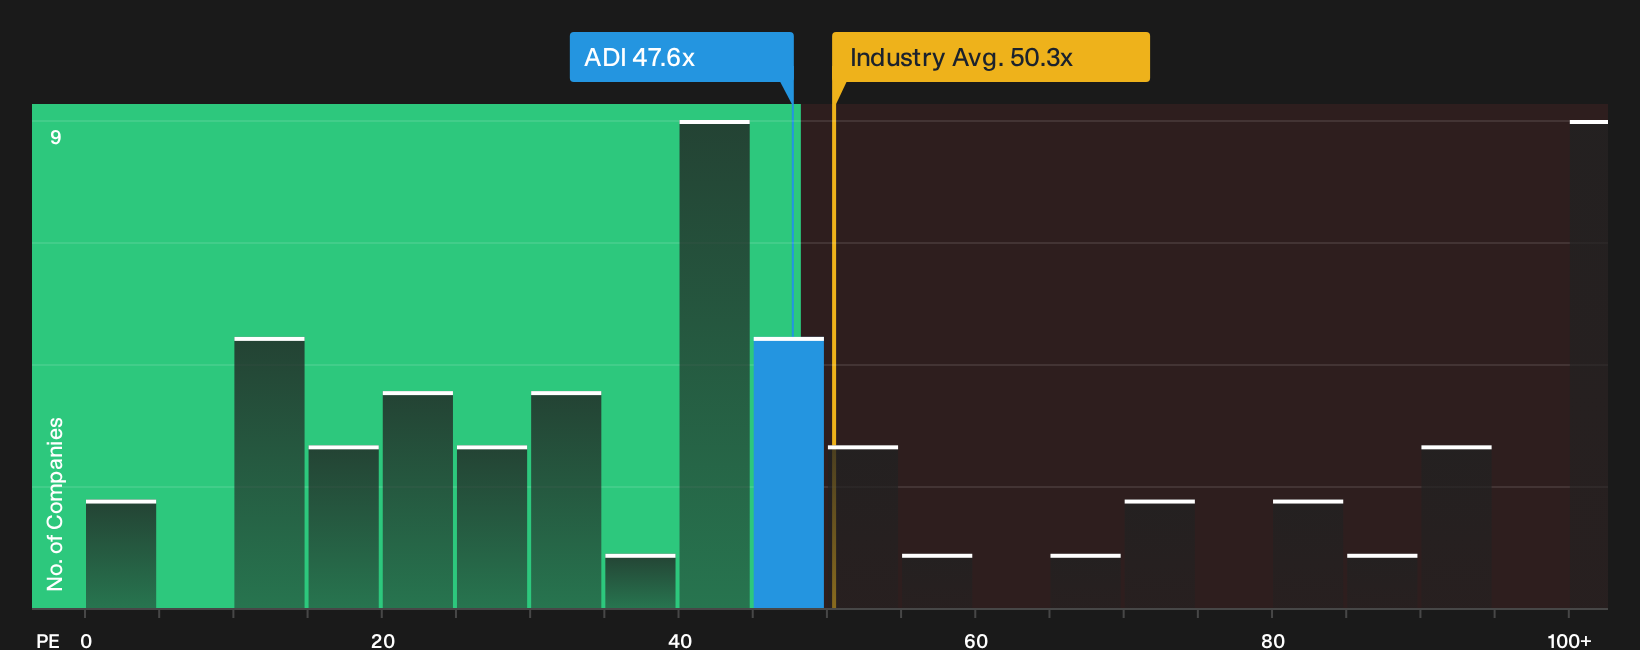
The P/E ratio fits Analog Devices because earnings are front and center for how investors value established chip designers with meaningful profit streams. At roughly 47.6x earnings, Analog Devices trades slightly below the broader semiconductor sector’s P/E of about 50.3x, yet well under the peer group average near 79.6x. That mix indicates the stock is priced at a premium to many profitable businesses in the market overall, but not at the very top of the sector’s range.
The in house fair multiple model, which incorporates Analog Devices' growth profile, margins, size and risk, points to a lower P/E than where the shares currently trade, so the stock screens as overvalued on this yardstick. Because the company has recently reported record quarterly results and AI focused demand remains a key talking point, some of that premium likely reflects confidence that current earnings quality holds up. The key consideration for investors is whether those fundamentals and the Alif Semiconductor deal eventually justify paying materially more than what that tailored fair multiple suggests. Explore the numbers behind Analog Devices's P/E valuation.
The Analog Devices Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Analog Devices pick up where this valuation puzzle leaves off. They spell out which future paths for growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does today on the Community page. Each one links its number to a clear view of how Analog Devices' expansion prospects, profitability and risk profile might evolve, giving you something concrete to revisit as fresh information lands.
Community views on Analog Devices are split between those who think AI and industrial momentum leave more upside on the table and those who see expectations already running hot.
Bull case: 14% undervalued
"Rising automotive content and edge AI adoption, reflected in automotive reaching 25% of revenue with faster growth than vehicle units over five years..."
Discover why this Narrative puts Analog Devices at 14% undervalued.
Bear case: 10% overvalued
"At least one external analysis that values Analog Devices around US$228 per share on a discounted cash flow basis, compared with a market price near US$389..."
Explore why this Narrative puts Analog Devices at 10% overvalued.
One more piece of the Analog Devices story that deserves a closer look
Before you lean too heavily on the valuation work, it is worth knowing that Simply Wall St's checks have flagged potential issues that could change how you judge Analog Devices overall. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com