


Interactive Brokers Group (IBKR) heads into its 15 October third quarter earnings release with attention on two anchors: expectations for higher profit and revenue, and a 6% year-on-year rise in September daily average revenue trades.
Recent trading tells a mixed story for Interactive Brokers Group. The share price has climbed 28.62% year to date but has retreated 4.95% over the past month and 8.10% over the last quarter, while the 1 year total shareholder return of 19.57% and the very large 5 year total shareholder return above 4x highlight a longer term trend that differs from the latest pullback.
Compare Interactive Brokers Group with other brokers experiencing increased trading activity by reviewing our curated 27 high quality undervalued stocks that pair solid fundamentals with potential mispricing.
Bulls point to Interactive Brokers Group’s long term return record and recent trading activity. Bears focus on the recent pullback and valuation risk. Which side do today’s numbers lean toward as you price IBKR now?
Most Popular Narrative: 18% Undervalued
On the most followed narrative, Interactive Brokers Group screens as undervalued, with a fair value of $105.74 against the recent $86.47 close. This puts the focus squarely on whether its business engine can justify that gap.
Record client equity of about $930b and uninvested cash balances of about $182b, combined with higher margin lending and securities lending activity, create a larger base of client funds that can be monetised through interest and lending spreads, which can support future net interest income and earnings.
See why 64 investors see Interactive Brokers Group as 18% undervalued.
Result: Fair Value of $105.74 (UNDERVALUED)
Still, the Interactive Brokers Group narrative could be knocked off course if fee pressure intensifies in online brokerage or if lower interest rates hit cash yield and lending income.
Find out about the key risks to this Interactive Brokers Group narrative.
Another View: Interactive Brokers Group Through A P/E Lens
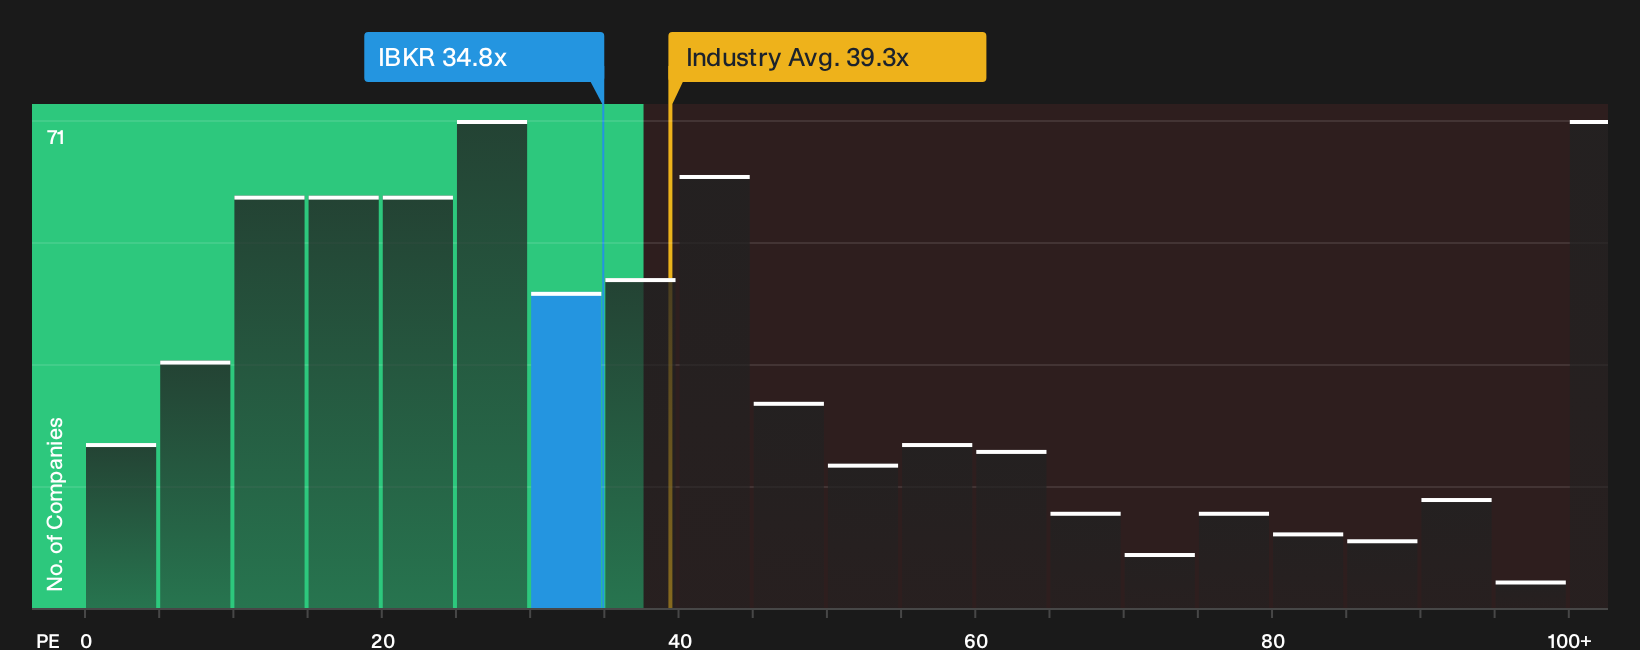
There is a very different read on Interactive Brokers Group once the focus shifts to a simple P/E check instead of fair value estimates. The stock trades on 34.8x earnings. That is cheaper than the US Capital Markets industry on 39.3x, yet materially richer than peers on 23x and the fair ratio of 20.7x.
This gap points to a real trade off. Investors are effectively paying up for quality indicators like high quality earnings and faster recent profit growth, while taking on the risk that the valuation could drift toward that lower fair ratio if expectations cool. Which side of that trade off are you really comfortable with as you value IBKR today?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Interactive Brokers Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the optimism in this Interactive Brokers Group story matches your own view. Consider acting promptly and pressure test the thesis against the 4 key rewards.
Looking for more investment ideas beyond Interactive Brokers Group?
If Interactive Brokers Group is on your radar, do not stop there. Use the Simply Wall Street Screener to hunt for fresh opportunities before the crowd moves.
- Target potential value opportunities early by scanning our 27 high quality undervalued stocks that focus on companies with strong fundamentals trading below their estimated worth.
- Shield your portfolio from shocks by reviewing a 31 resilient stocks with low risk scores that highlights businesses with more resilient financial risk profiles.
- Spot tomorrow’s potential leaders by working through a 20 high quality undiscovered gems that surfaces quality companies with less attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com