


As global markets navigate mixed signals from U.S. job growth, inflation concerns, and geopolitical tensions, investors are seeking opportunities in various market segments. Penny stocks, often associated with smaller or newer companies, remain a relevant investment area despite the term's vintage feel. By focusing on those with strong financials and potential for growth, investors can uncover promising candidates that may offer both stability and upside in these uncertain times.
Let's take a closer look at a couple of our picks from the screened companies.
Dubai Investments PJSC (DFM:DIC)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Dubai Investments PJSC operates in property, investment, manufacturing, contracting, and services sectors both in the United Arab Emirates and internationally, with a market capitalization of AED15.95 billion.
Operations: The company's revenue is primarily derived from property (AED2.00 billion), manufacturing, contracting and services (AED1.55 billion), and investments (AED372.63 million).
Market Cap: AED15.95B
Dubai Investments PJSC, with a market capitalization of AED15.95 billion, shows a mixed financial picture relevant to penny stock discussions. The company reported strong revenue growth for the first half of 2026, reaching AED2.04 billion from diverse sectors like property and manufacturing. Despite high-quality earnings impacted by a significant one-off gain of AED889.5 million, its return on equity remains low at 11.4%. The debt situation is improving with reduced debt-to-equity ratios and satisfactory interest coverage by EBIT (4.2x). However, future earnings are forecasted to decline significantly over the next three years, raising concerns about sustainability amidst dividend coverage issues.
- Unlock comprehensive insights into our analysis of Dubai Investments PJSC stock in this financial health report.
- Explore Dubai Investments PJSC's analyst forecasts in our growth report.
Nickel Asia (PSE:NIKL)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Nickel Asia Corporation is involved in the mining and exploration of nickel saprolite, limonite ore, limestone, and quarry materials in the Philippines with a market cap of ₱53.91 billion.
Operations: The company's revenue is primarily derived from its mining operations, with significant contributions from TMC at ₱14.97 billion, RTN at ₱7.74 billion, HMC at ₱4.08 billion, CMC at ₱4.60 billion, and DMC at ₱771.67 million; it also generates income from power through NEI amounting to ₱1.47 billion and NAC totaling ₱266.61 million, alongside services provided by RTN/TMC/CDTN which contribute an additional ₱983.61 million in revenue.
Market Cap: ₱53.91B
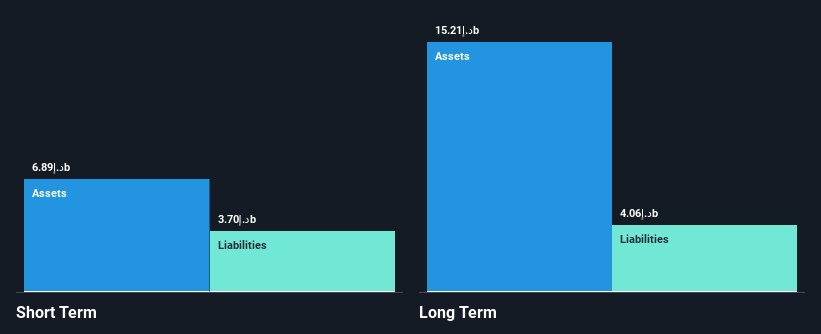
Nickel Asia Corporation, with a market cap of ₱53.91 billion, presents a compelling case in the penny stock arena due to its robust earnings growth and solid financial health. Recent earnings reports show significant revenue growth to ₱13.87 billion for Q2 2026, with net income rising sharply to ₱3.68 billion. The company benefits from an experienced management team and board, while maintaining strong asset coverage over liabilities and adequate interest payment coverage. Despite increased debt levels over five years, Nickel Asia's cash flow comfortably covers its debt obligations; however, its dividend track record remains unstable amidst trading at a considerable discount to estimated fair value.
- Click here and access our complete financial health analysis report to understand the dynamics of Nickel Asia.
- Learn about Nickel Asia's future growth trajectory here.

Quzhou DFP New Material Group (SHSE:601515)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Quzhou DFP New Material Group Co., Ltd. specializes in the research, development, design, manufacture, and sale of printing and paper packaging products both in China and internationally, with a market cap of CN¥6.08 billion.
Operations: No specific revenue segments are reported for Quzhou DFP New Material Group Co., Ltd.
Market Cap: CN¥6.08B
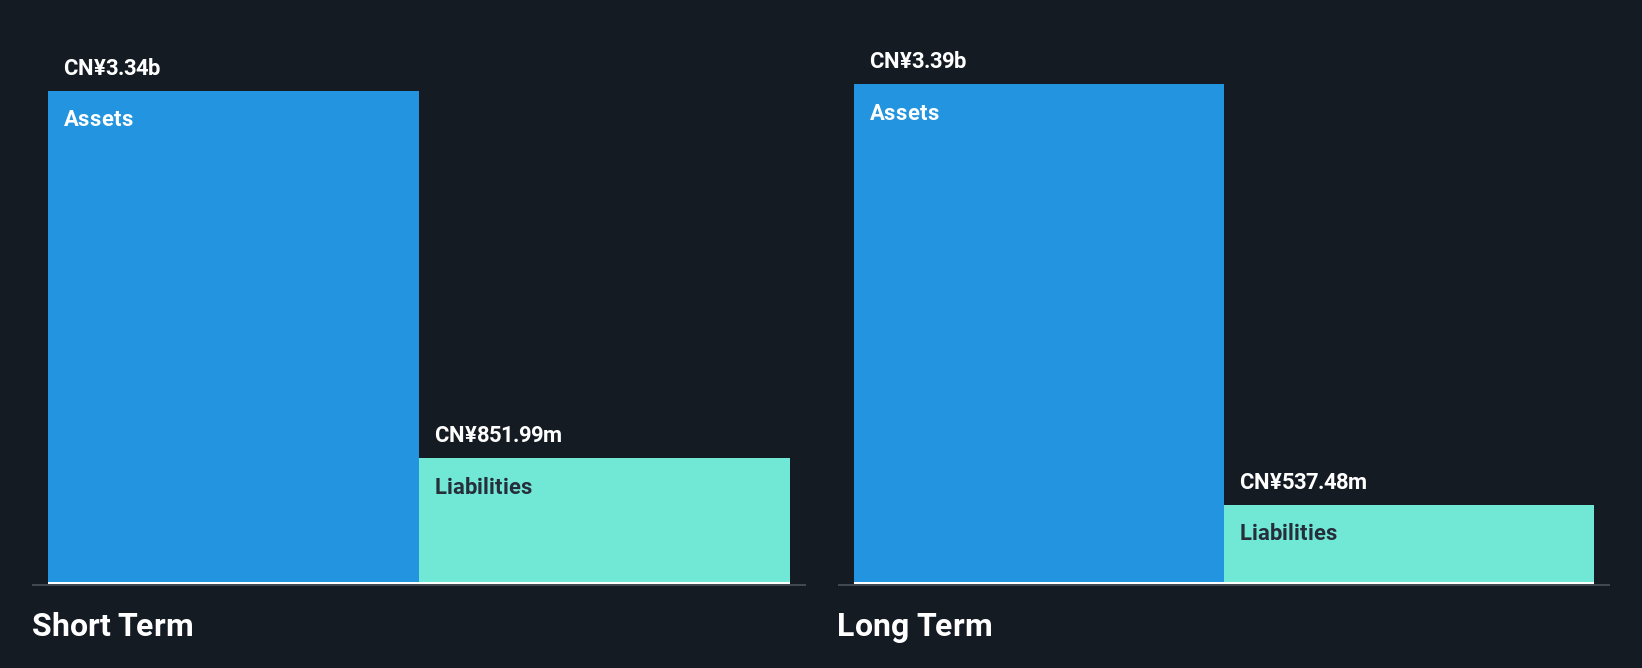
Quzhou DFP New Material Group, with a market cap of CN¥6.08 billion, is navigating challenges typical of penny stocks. Despite reporting revenue growth to CN¥744.87 million for H1 2026 and narrowing net losses slightly to CN¥58.3 million, the company remains unprofitable with a negative return on equity (-11.62%). Its management and board are relatively inexperienced, averaging 1.3 years in tenure. However, Quzhou DFP's financial position shows resilience as short-term assets significantly exceed liabilities and cash surpasses total debt levels, offering some stability despite ongoing operational losses and negative operating cash flow.
- Jump into the full analysis health report here for a deeper understanding of Quzhou DFP New Material Group.
- Explore historical data to track Quzhou DFP New Material Group's performance over time in our past results report.
Seize The Opportunity
- Reveal the 3,515 hidden gems among our Global Penny Stocks screener with a single click here.
- Seeking Other Investments? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com