


- Recent client announcements show Solera linking Verisk’s IVI Total Loss to the Audatex estimating platform and Truepic adding authenticated visual evidence tools into Verisk’s ClaimSearch, both focused on more automated claims handling.
- Together, these integrations point to Verisk Analytics pushing deeper into end to end digital claims workflows, where data flows cleanly between insurers, repairers and fraud teams rather than sitting in disconnected systems.
- We will now look at how Verisk Analytics' investment narrative could shift as ClaimSearch gains integrated authenticated image and video checks.
Scan beyond Verisk Analytics and see how other insurers and data platforms are retooling claims automation by reviewing our hand-picked 31 resilient stocks with low risk scores.
Verisk Analytics Investment Narrative Recap
For a shareholder in Verisk Analytics, the core belief is that insurers keep leaning on its data, AI tools and catastrophe models to run everyday underwriting and claims workflows. The near term swing factor still sits with execution on subscription products like Core Lines Reimagined and AI claims tools, which could matter more to sentiment than the latest point solution integrations.
The biggest risk remains customer spending restraint if inflation, regulation or reconstruction costs push carriers to trim analytics budgets, especially on transactional products. The recent claims integrations look directionally helpful for usage and stickiness, but on their own they do not meaningfully change that risk reward balance in the short term.
The Truepic integration into Verisk’s ClaimSearch platform looks most relevant because it sits directly on top of an existing fraud detection workflow that insurers already rely on. Authenticated images and video, triggered off a ClaimSearch fraud alert, make that product more of a one stop hub for suspicious claims rather than just a signal generator.
For the current catalyst narrative, this kind of deeper workflow integration supports the idea that Verisk Analytics can broaden automation in claims while still monetising its data. The operational question is execution at scale. If carriers embed Truepic Vision widely, it could reinforce ClaimSearch as essential infrastructure, although slower fraud activity or tighter budgets could still weigh on transaction volumes.
Verisk Analytics' current analyst storyline points to revenues of US$3.8b and earnings of US$1.3b by 2029, implying 6.6% yearly revenue growth and an earnings increase of about US$414.5m from US$885.5m today.
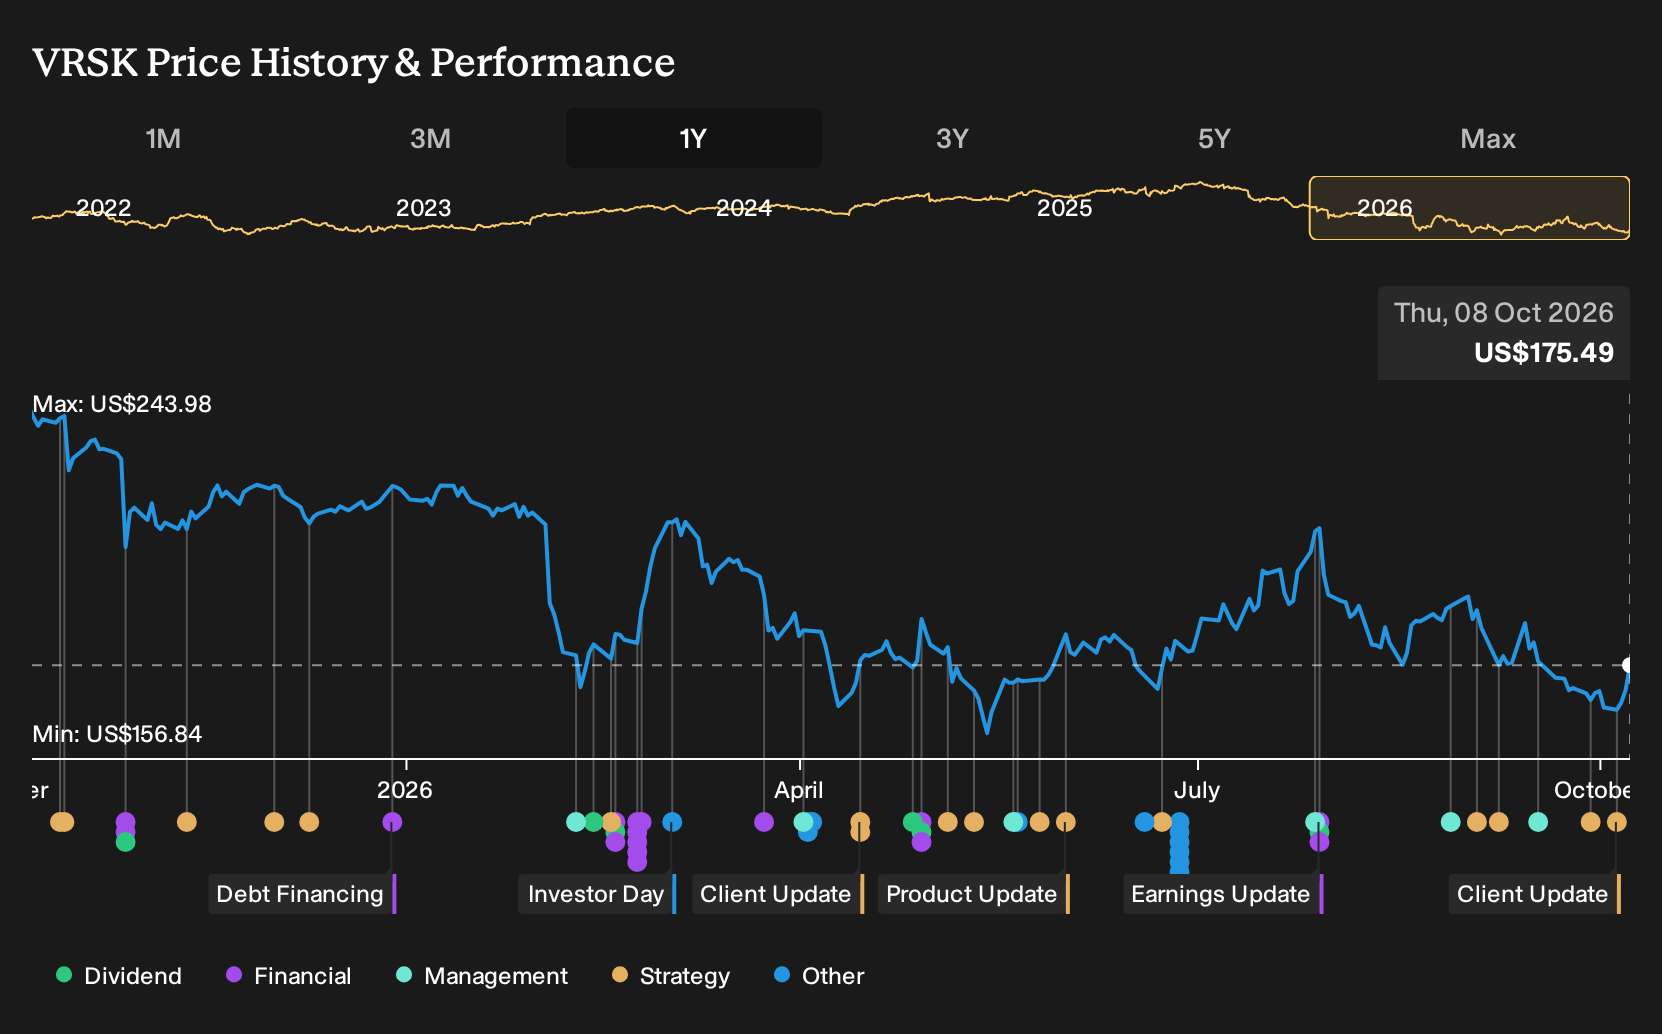
Uncover why Verisk Analytics' fair value indicates a 34% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span roughly US$77 to US$286, so some members see Verisk Analytics as close to fully priced while others model far richer outcomes. When you factor in the push into AI claims tools and catastrophe platforms alongside inflation, regulation and weather-related uncertainty, you get a wide spread of expectations. Use that gap to explore several alternative viewpoints before deciding where you sit.
Explore 4 other Verisk Analytics fair value estimates, including one that suggests as much as 63% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Verisk Analytics research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Verisk Analytics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Verisk Analytics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Verisk Analytics?
Once you have a view on Verisk Analytics, it helps to compare that thesis with opportunities across other sectors and risk profiles. The Simply Wall St Screener lets you scan for different types of companies using the same consistent framework, so you can build a watchlist that fits your approach.
- If capital preservation is your priority, you can start with resilient candidates using our 31 resilient stocks with low risk scores that aim to keep drawdowns in check while still participating in market upside.
- For those focusing on strong balance sheets and solid fundamentals, you can filter the market with a focused list of solid balance sheet and fundamentals (25 results) that surfaces businesses with sturdier financial footing.
- When you want under-covered opportunities, you can widen your search with a curated 20 high quality undiscovered gems that may not yet be on every investor’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com