


Valaris (VAL) just put fresh numbers around future work. The offshore driller reported about $220 million in new contracts and extensions, a key update for anyone tracking its contract coverage.
Recent trading has been strong for Valaris, with the share price up 2.6% on the day and a 7-day share price return of 5.5%. The 90-day move of 8.2% and year-to-date share price return of 61.0% point to building momentum from a much longer run, where the 1-year total shareholder return of 66.0% and 5-year total shareholder return of 140.1% frame these new contracts as part of a broader rerating of both growth prospects and perceived risk.
Scan offshore drillers showing similar contract momentum to Valaris by checking the hand picked 27 high quality undervalued stocks that is now shaping the next leg of this cycle.
Bulls view Valaris as a cash machine in the making, while bears see a hot offshore cycle already priced in after a 61.0% year to date surge. Which story do the current valuation markers actually support?
Most Popular Narrative: 24.5% Overvalued
Valaris last closed at $83.96, while the most followed narrative anchors fair value at $67.43, so the story today is about a stock already pricing in a lot of future execution.
The all stock merger with Transocean is being sold as transformational, with more than US$200 million of annual cost synergies, a pro forma backlog above US$10b and a targeted leverage ratio of about 1.5x within 24 months of closing. However, the stock already prices in substantial value from those integration benefits that are still to be realised in future margins, earnings and cash flow.
See why 30 investors see Valaris as 25% overvalued.
Result: Fair Value of $67.43 (OVERVALUED)
Still, if offshore demand stays firm and the Transocean merger delivers the planned cost savings and backlog scale, the bearish Valaris narrative could look too harsh.
Find out about the key risks to this Valaris narrative.
Another View On Valaris: P/E Ratios Tell A Different Story
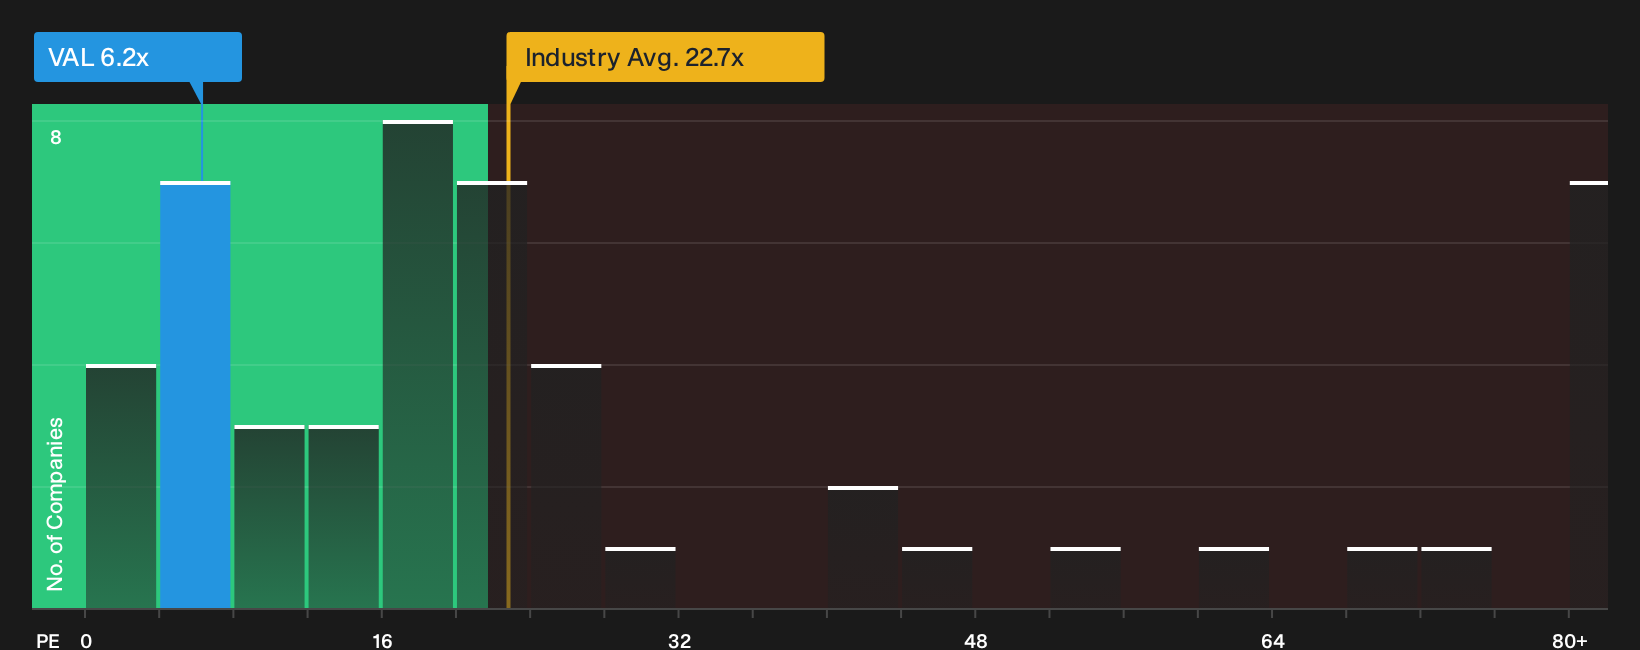
Analyst narratives flag Valaris as about 24.5% overvalued relative to a $67.43 fair value, yet the stock trades on a P/E of 6.2x versus 22.9x for the US Energy Services industry and 30.2x for peers, while the fair ratio sits lower at 4.4x. That mix of discount to sector, premium to fair ratio, and concern about earnings quality leaves a simple question for you: Is the risk here that the share price is too high, or that the profit base is too hard to repeat?
To see how this valuation gap has been framed using earnings multiples rather than cash flow forecasts, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views are all over Valaris right now, so move quickly, look through the data yourself and decide where you land on the risk reward trade off. To see the balance of both concerns and potential upsides that investors are focused on, start with the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Valaris?
You have seen how heated the debate is around Valaris. Do not stop here. Broaden your watchlist now or risk missing the next setup.
- Target stability first by reviewing a 31 resilient stocks with low risk scores that focuses on businesses with more resilient profiles when market sentiment swings.
- Hunt for potential mispricing by scanning a 20 high quality undiscovered gems that highlights companies with strong fundamentals that fewer investors are watching.
- Prioritise financial strength by checking a list of solid balance sheet and fundamentals (25 results) that filters for healthier balance sheets and more robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com