


Google data center deal puts Black Hills in the spotlight
Black Hills (BKH) has moved into focus after signing long-term agreements to supply power to a planned Google data center in Cheyenne, Wyoming, with service scheduled from late 2027 through 2048.
Investors have already reacted to the Google announcement, with Black Hills’ share price delivering a 9.10% 7-day share price return and a 9.86% year-to-date share price return. Long-term holders have seen a 30.23% 1-year total shareholder return and 75.20% over three years, suggesting momentum has been building around the story.
Spot similar long-term infrastructure plays by scanning our hand picked 43 power grid technology and infrastructure stocks. This screener focuses on moving capital toward large data center and grid expansion themes.Black Hills now trades at a discount to analyst targets even after the Google-driven jump. Is that the market mispricing long-term cash flows, or a sober read on project risk and execution timing, as the valuation section lays out next?
Most Popular Narrative: 8% Undervalued
Against the last close at $76.52, the most followed narrative for Black Hills points to a fair value of about $83.17, which is higher than where the stock trades and places more emphasis on long-dated data center and merger themes than the current price appears to reflect.
The current valuation implies the share price does not fully reflect the earnings trajectory implied by reaffirmed 2026 guidance, the reduced near term equity issuance needs, and the expected benefits from the NorthWestern Energy all-stock merger if it closes as planned.
The updated view places more emphasis on visible progress at the Cheyenne data center project, clearer merger timing with NorthWestern Energy, and a defined 5 year capital and financing plan as key drivers of the story from here.
See why 17 investors see Black Hills as 8% undervalued.
Result: Fair Value of $83.17 (UNDERVALUED)
Still, the Black Hills story leans heavily on regulators endorsing its US$4.7b capital plan and on data center clients following through on that 3 GW pipeline.
Find out about the key risks to this Black Hills narrative.
Another View on Black Hills: Cash Flows Point the Other Way
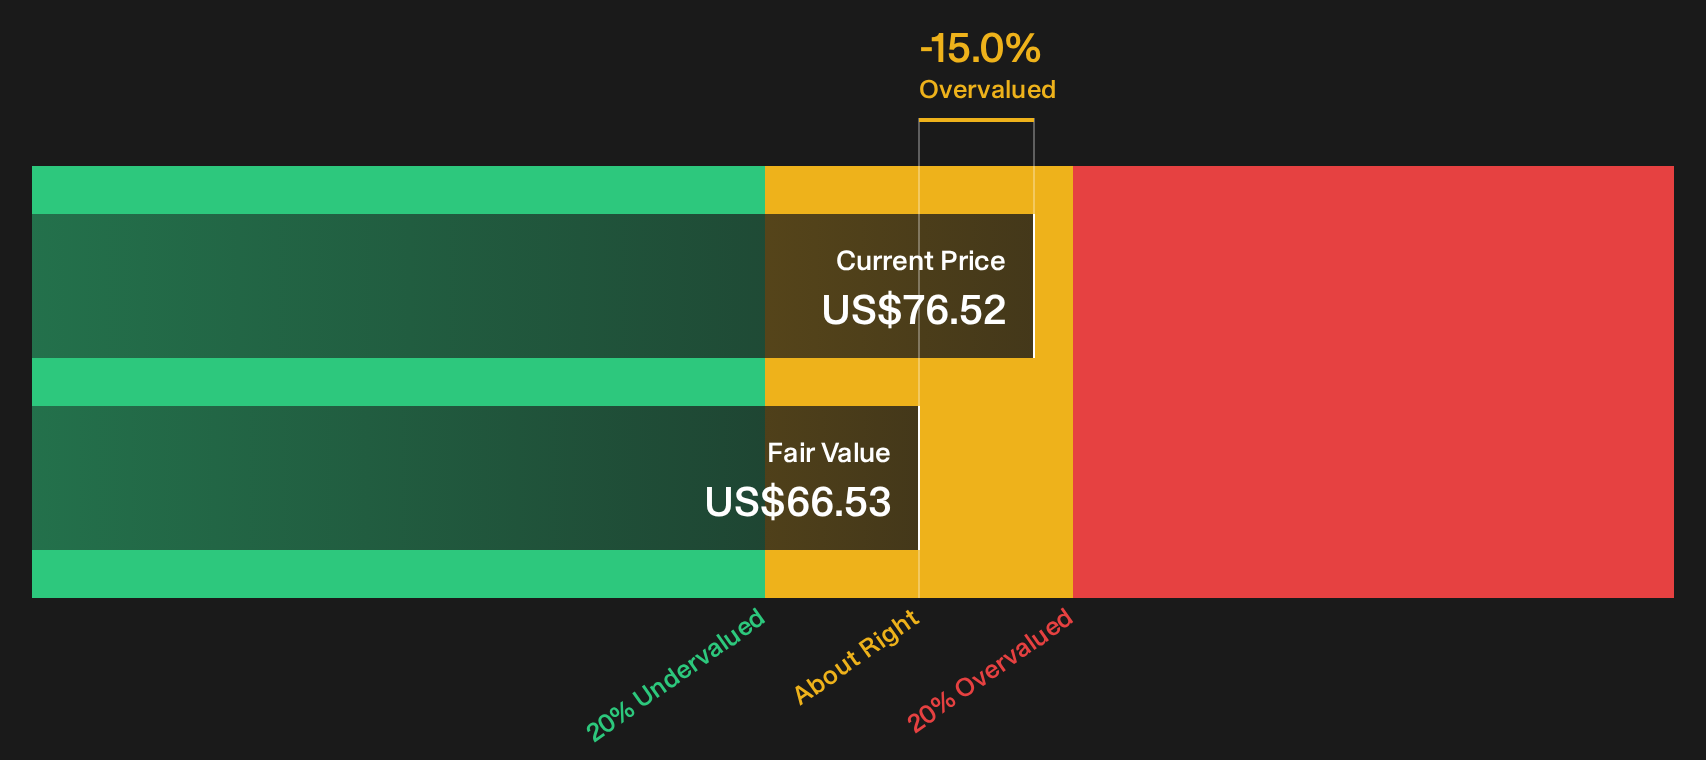
The story so far leans on earnings and analyst targets that put Black Hills at roughly an 8% discount to a fair value of $83.17. A different tool tells a cooler story. The Simply Wall St DCF model points to a future cash flow value of $66.53, which would leave the stock looking overvalued on that lens.
For anyone weighing up those competing signals, it helps to see exactly how the long term cash flow path is being treated in the model, where the discount rate bites hardest, and how sensitive the outcome is to different growth paths, which you can do by stepping through Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Black Hills for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The story so far mixes optimism and caution, with Black Hills pulling in both risk flags and upside signals that investors are debating in real time.
If you want a clear view before sentiment shifts again, step through the details yourself and weigh up 3 key rewards and 2 important warning signs.
Looking for more Black Hills sized investment ideas?
Do not stop with one opportunity. Broaden your watchlist with focused stock ideas built from the same kind of data driven work you have just seen on Black Hills.
- Target potential mispricings by scanning a curated pool of companies with robust fundamentals and appealing valuations through the 27 high quality undervalued stocks.
- Prioritize income and staying power by reviewing a hand picked group of high yield payers screened as 8 dividend fortresses.
- Dial down portfolio stress by focusing on financially resilient businesses filtered as 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com