


BIPROGY (TSE:8056) has drawn fresh attention after partnering with SOLUM to showcase E-Paper Signage retail solutions at RETAIL EXPO Tokyo 2026 and APRCE 2026, highlighting its role in Japan’s digital store infrastructure.
Recent price action tells a mixed story for BIPROGY. The share price has climbed over the past week and month, with a 7 day share price return of 2.06% and a 30 day gain of 3.98%. The latest partnership news arrives as that short term momentum builds, even though the year to date share price return is down 10.85% and the 1 year total shareholder return has declined 17.23%, compared with stronger 3 year and 5 year total shareholder returns of 40.62% and 75.46% respectively.
Scan beyond BIPROGY and this retail tech story by reviewing a hand picked basket of stocks in the same theme through the 91 robotics and automation stocks.
BIPROGY now trades at a discount to both analyst targets and one estimate of fair value, even after the recent bounce. Is that a margin of safety, or a warning sign that the market is reading the risks correctly?
Price-to-Earnings of 15.5x: Is it justified?
BIPROGY shares closed at ¥4,805 while the SWS DCF model estimates fair value at ¥5,309.1, so the stock is priced below that cash flow based figure and its 15.5x P/E suggests the market is not assigning a premium multiple either.
The P/E ratio compares the current share price with earnings per share and gives a quick sense of what investors are paying for each unit of profit. For a software and IT services group like BIPROGY, where profit visibility and contract driven revenue can matter more than sheer top line expansion, the earnings tag often does more of the heavy lifting than sales based measures.
At 15.5x earnings, BIPROGY trades at a lower P/E than both the peer average of 22.5x and the broader JP IT industry on 16.4x. This points to the market assigning a cheaper label to its profit stream. The estimated fair P/E of 21.7x is also well above the current level, suggesting the multiple might reasonably sit higher if pricing moved closer to that regression based reference point.
Explore the SWS fair ratio for BIPROGY.
Result: Price-to-Earnings of 15.5x (UNDERVALUED)
Still, the recent declines in BIPROGY’s 1 year shareholder return and its heavy reliance on Japan for all reported revenue could limit how quickly sentiment shifts.
Find out about the key risks to this BIPROGY narrative.
Another view on BIPROGY valuation
The earlier P/E check points to BIPROGY looking inexpensive, and the SWS DCF model values the shares above the current ¥4,805 price at ¥5,309.1. Both profit based and cash flow based perspectives indicate a similar conclusion. Is the market overlooking something, or simply taking a cautious stance on the outlook?
Look into how the SWS DCF model arrives at its fair value.
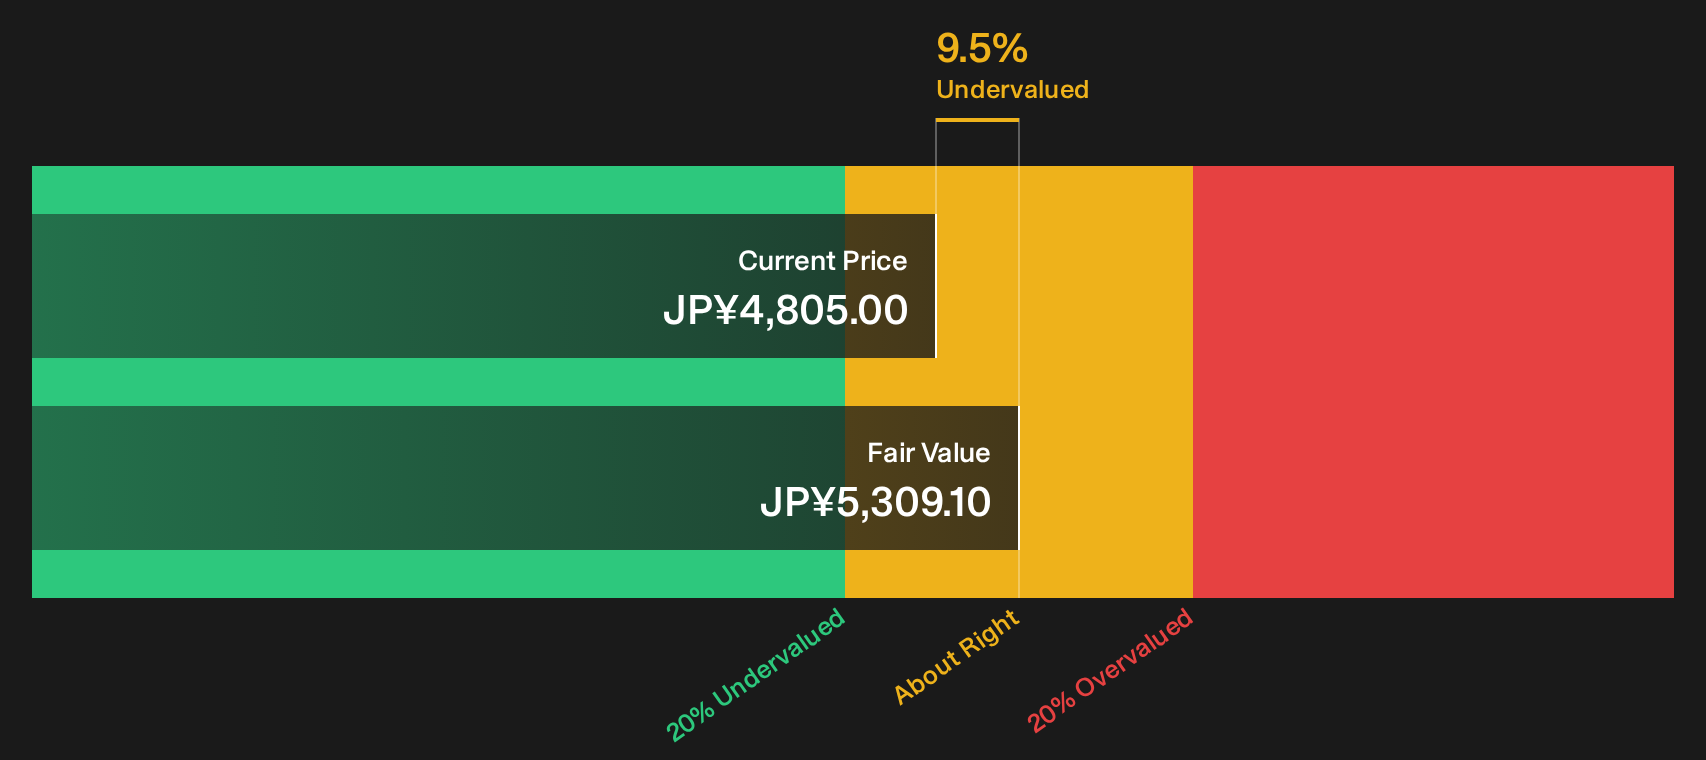
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BIPROGY for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on BIPROGY so far. If you want to move quickly and reach your own verdict, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BIPROGY?
You have done the work on BIPROGY. Now give yourself a wider field of choices by lining it up against other clear, data driven opportunities.
- Target resilience first and stress test your watchlist against 23 resilient stocks with low risk scores so you are not relying on gut feel when volatility picks up.
- Pursue quality at a discount and see which companies pass strict price and fundamentals filters with the 12 high quality undervalued stocks while the market is still hesitant.
- Build a watchlist of tomorrow’s potential leaders early by scanning the 74 high quality undiscovered gems before crowd attention and price catch up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com