


- Pembina Pipeline Corporation reported that the Pacific Link oil pipeline, in which it has a 10% economic interest, was designated a Project of National Interest by the Canadian government, giving the project a clearer and more predictable federal review process.
- The Pacific Link designation highlights Pembina Pipeline’s role in a proposed one million barrel per day export corridor, which could change how the business accesses overseas crude markets if the project reaches commercial operation.
- This article examines how Pembina Pipeline’s investment narrative is affected by the Project of National Interest status for the Pacific Link pipeline.
What Is Pembina Pipeline's Investment Narrative?
To own Pembina Pipeline, you need to be comfortable with a capital intensive midstream model that leans on long lived pipelines and facilities, steady fee based contracts, and meaningful debt on the balance sheet. The Pacific Link Project of National Interest label matters most as a potential future growth avenue rather than an immediate financial swing factor, since Pembina’s current 10% economic interest carries no at risk development capital before a final investment decision. The nearer term story still turns on execution in existing Pipelines and Facilities, hydrocarbon volume trends, and how well the marketing arm manages commodity exposure.
The fresh preferred share dividend declarations reinforce that income remains a core part of Pembina Pipeline’s pitch, even as prior analysis flags that dividends are not well covered by earnings. That mix of income focus and higher leverage keeps funding costs and access to capital near the top of the risk list, especially with options pricing pointing to elevated implied volatility. Pacific Link and the preferred payouts both fit into the same question for shareholders, which is how much balance sheet strain they are willing to accept in exchange for exposure to fee based infrastructure and potential overseas crude access.
That said, there is a less comfortable angle to this story that turns on what happens if...
There's only one way to know the right time to buy, sell or hold Pembina Pipeline. Head to Simply Wall St's company report for the latest analysis of Pembina Pipeline's Fair Value.
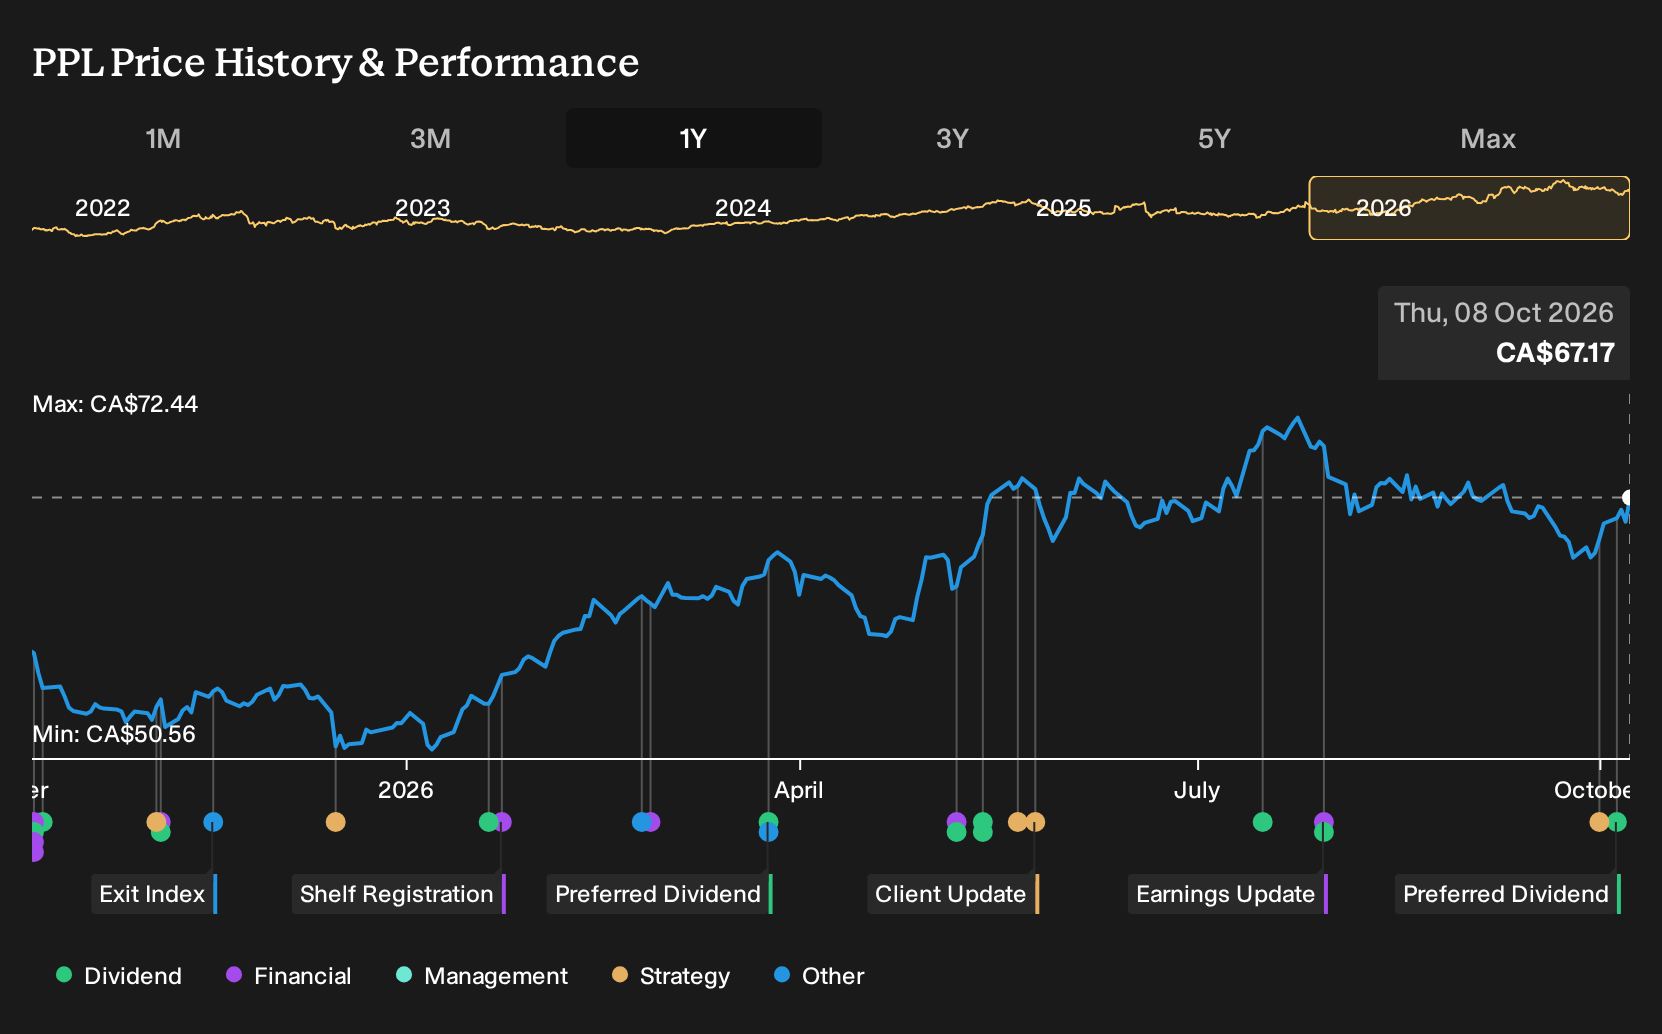
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly $73 to about $239, so private investors are clearly split on Pembina Pipeline. Those estimates were set before the Pacific Link update and the latest preferred dividend declarations. This gives you a reason to revisit the story and compare multiple viewpoints.
Explore 2 other Pembina Pipeline fair value estimates, including one that suggests up to 256% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pembina Pipeline research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Pembina Pipeline. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pembina Pipeline's overall financial health at a glance.
Looking For More Investment Ideas Beyond Pembina Pipeline?
If the Pacific Link story has prompted you to reassess Pembina Pipeline in your portfolio, it can be useful to set it alongside other businesses with different risk and income profiles. The Simply Wall St Screener helps you scan a broad investable universe and narrow it down to stocks that better fit your preferences for cash flow resilience, balance sheet strength, or long term total return potential.
- If reliable payouts and financial resilience are top of mind, focus on companies with strong coverage metrics and sturdy finances using the 3 dividend fortresses.
- For investors hunting for quality at a measured price, compare Pembina Pipeline with a 7 high quality undervalued stocks that blend balance sheet support with solid cash generation.
- If you like finding opportunities before they are widely followed, cast a wider net with a 9 high quality undiscovered gems that already show stronger fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com