


- Selective Insurance Group appointed Vaibhav (Vaib) Kalia as Executive Vice President and Chief Investment Officer on 6 October 2026, formalizing his interim role and placing him in charge of the insurer's investment portfolio, benefit plan assets and Management Investment Committee.
- Kalia's background in fixed income, risk and quantitative analysis means his decisions could be particularly important for how Selective Insurance Group manages its net investment income stream and overall risk profile.
- This article examines how Selective Insurance Group's investment narrative is influenced by Kalia's elevation to the permanent Chief Investment Officer role.
Selective Insurance Group Investment Narrative Recap
To own Selective Insurance Group, you need to be comfortable with a business that leans heavily on underwriting discipline and a large casualty book, while casualty claim severities are assumed around 9% and commercial auto severity around 10%. The short term swing factor remains how fast management can re underwrite weaker cohorts without putting too much pressure on premium volume.
The biggest risk is that higher prices and stricter underwriting continue to coincide with falling Standard Commercial Lines premiums and weaker new business, which already declined in recent quarters. The CIO appointment matters most for how net investment income supports earnings if top line growth in core insurance segments stays under pressure.
The promotion of Vaibhav Kalia to permanent Chief Investment Officer connects directly to the existing earnings narrative around net investment income, which reached about US$119m after tax in 2Q 2026 with full year guidance of US$480m. Selective Insurance Group already leans on an A plus rated fixed income book and management attention now turns to how consistently that income stream can support overall profit.
For catalysts, the CIO change sits alongside efforts in data analytics, digital claims tools and AI, plus expansion in Excess and Surplus and mass affluent personal lines. Your read on the stock will probably hinge on whether this investment leadership, combined with underwriting actions, can offset casualty loss trends and potential ongoing softness in Standard Commercial Lines premiums.
Selective Insurance Group is framed by analyst models that point to revenues of US$5.5b and earnings of US$575.2m by 2029, off a flat top line assumption and current earnings of US$488.4m. This implies an earnings increase of about US$86.8m over that period, while profit margins are expected to move from 8.9% today to 10.4%.
Explore how Selective Insurance Group's fair value suggests a 20% potential upside to its current price before investors eliminate the discount.
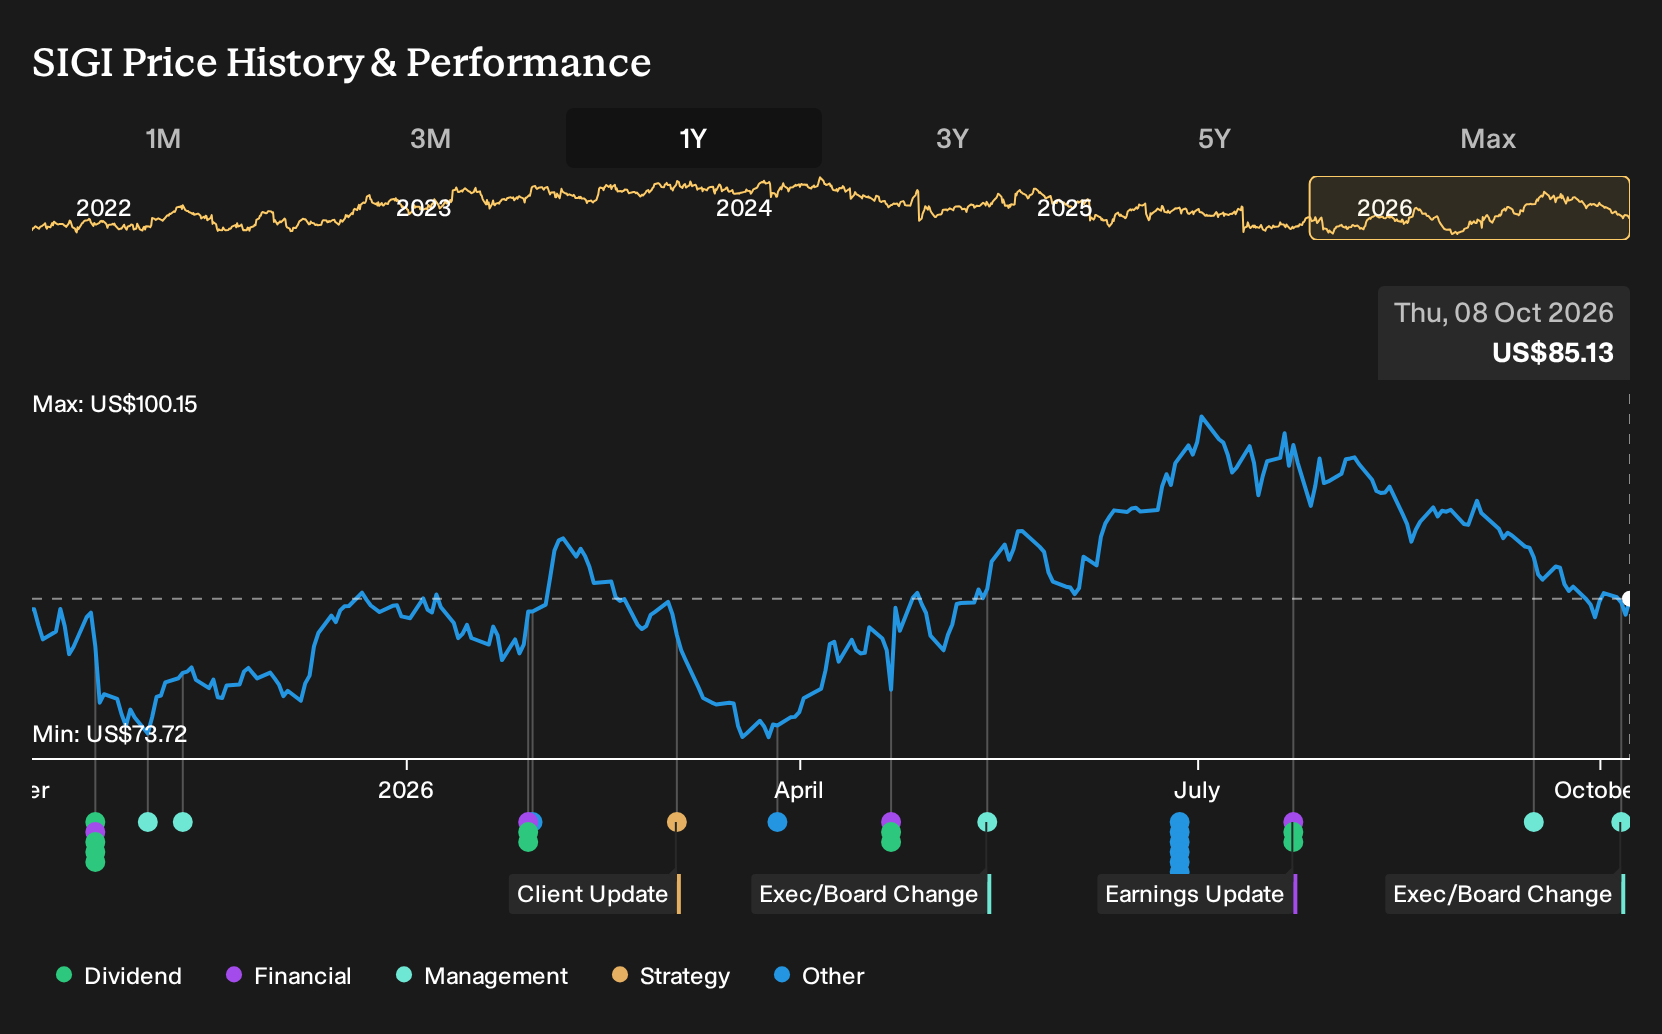
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span roughly US$102 to US$186 per share, so private investors are already treating Selective Insurance Group as anything from mildly discounted to heavily cheap. Those views were formed before Kalia became CIO, so weigh them against casualty severity risks and the potential earnings support from net investment income and expense efficiency.
Explore another Selective Insurance Group fair value estimate, including one that suggests it could be worth just $101.86.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Selective Insurance Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Selective Insurance Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Selective Insurance Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Selective Insurance Group?
If the Selective Insurance Group story has sharpened your thinking about risk, income and balance sheet strength, you can use that same lens across the wider market with the Simply Wall St Screener.
- For investors who care about financial resilience and quality, you can start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching the balance sheet.
- If you want to focus on price versus fundamentals, you can scan a 27 high quality undervalued stocks that may offer a margin of safety based on cash flows and earnings strength.
- Income focused readers can zero in on payout durability by checking a 8 dividend fortresses that combine higher yields with robust underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com