


Pictet Asset Management’s recent engagement with Dynatrace (DT) has put fresh attention on how the Boston based software group runs its business and thinks about long term shareholder value.
Recent price action already reflects some of that optimism. Dynatrace’s share price is at US$61.12 after a 21.54% 30 day share price return and 39.93% 90 day share price return. The 1 year total shareholder return of 24.99% follows a 5 year total shareholder return decline of 20.42%, suggesting momentum has recently picked up from a weaker long term base.
Spot opportunities around Dynatrace’s momentum and governance focus by scanning a curated set of 35 profitable AI stocks that aren't just burning cash that already pair AI exposure with positive earnings.Dynatrace’s rally to US$61.12 now sits almost exactly on the average analyst target, while internal fair value work points to a meaningful discount. Is the market already generous, or is it still leaving room on the table?
Most Popular Narrative: 2% Overvalued
Dynatrace’s most followed narrative pegs fair value at $59.71, a touch below the latest $61.12 close. This raises questions about how much of the AI observability story is already in the price.
The ongoing shift in the industry toward value-based, consumption-driven pricing models, with Dynatrace's DPS contracts now accounting for 65% of ARR and driving higher platform adoption and faster consumption, supports higher long-term revenue growth, improved customer lifetime value, and the potential for margin expansion.
See why 52 investors see Dynatrace as 2% overvalued.
Result: Fair Value of $59.71 (OVERVALUED)
Still, the story can change quickly if competition from hyperscalers bites harder or large enterprise deals slip, which could put the current Dynatrace narrative under pressure.
Find out about the key risks to this Dynatrace narrative.
Another View: Dynatrace Through The Cash Flow Lens
Analysts leaning on earnings multiples see Dynatrace as expensive, with a 116.7x P/E versus 30.9x for the US software group and a 36.2x fair ratio. The SWS DCF model tells a different story, with future cash flows pointing to a fair value of $70.98 and flagging the shares as undervalued. Which lens do you trust more when the growth narrative is this dependent on AI execution?
To see how that cash flow view is built line by line, take a closer look at the SWS DCF model behind this fair value signal: Look into how the SWS DCF model arrives at its fair value..
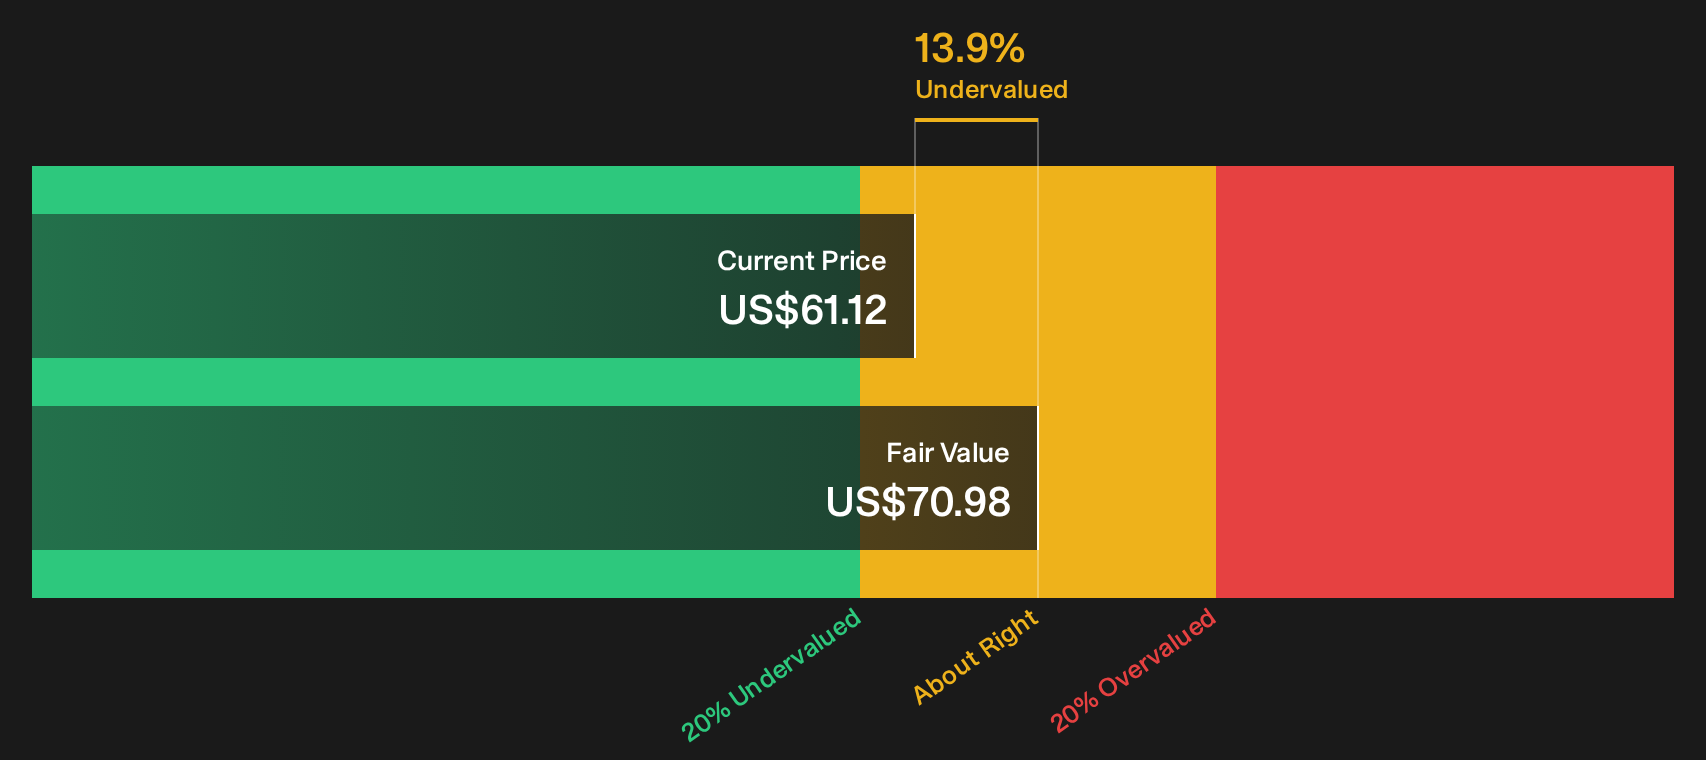
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dynatrace for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Dynatrace’s value, risk, and AI execution make this a nuanced setup, so move fast on the data and shape your own view by weighing the 2 key rewards and 1 important warning sign.
Looking for more Dynatrace style investment ideas?
Do not leave your research anchored to one stock. Use the Simply Wall Street Screener to compare fresh ideas side by side and level up your process.
- Target value with quality by scanning a 27 high quality undervalued stocks that already combines strong fundamentals with pricing that may appeal to patient investors.
- Prioritise resilience by checking a 31 resilient stocks with low risk scores that flags businesses with sturdier financial and risk profiles than the broader market.
- Hunt for underfollowed potential by reviewing a 20 high quality undiscovered gems that highlights companies with strong metrics but limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com