


CSX (CSX) just signed an agreement with the Massachusetts Department of Transportation to fund a new siding and track upgrades near Pittsfield, aimed at easing conflicts between freight and passenger trains and supporting permanent Berkshire Flyer service.
CSX has packed in several headlines lately, from this MassDOT partnership to a fresh US$0.14 quarterly dividend and storm related operational adjustments along the Gulf Coast. Yet the share price tells a mixed story, with strong year to date share price momentum of 30.52% and a 1 year total shareholder return of 33.01% set against a softer 90 day share price return that is down 4.19%. This hints that long term holders have been rewarded while short term enthusiasm has cooled slightly as investors reassess risk and future rail investment payoffs.
Capitalize on CSX's rail momentum story and scan our hand picked list of solid balance sheet and fundamentals (25 results) that could also benefit from long term infrastructure and logistics trends.CSX has delivered strong one-year and year-to-date gains, yet the softer 90-day pullback raises a simple question: Is the better risk-reward now ahead of you, or mostly in the rear-view mirror as valuation tightens?
Most Popular Narrative: 10.9% Undervalued
CSX closed at $47.34, while the most followed narrative pegs fair value at about $53.10 using an 8.62% discount rate. This leaves a modest valuation gap that investors are watching closely.
The industrial development pipeline of roughly 600 active projects, with about 100 expected to enter service in 2026 and provide significantly more volume at full ramp than the prior year cohort, is poised to add new carloads that support merchandise and bulk revenue and help operating leverage.
See why 25 investors see CSX as 11% undervalued.
Result: Fair Value of $53.10 (UNDERVALUED)
Still, the CSX narrative can crack if crew shortages strain service quality again, or if tighter safety rules push operating costs higher than analysts currently assume.
Find out about the key risks to this CSX narrative.
Another View: CSX Through The P/E Lens
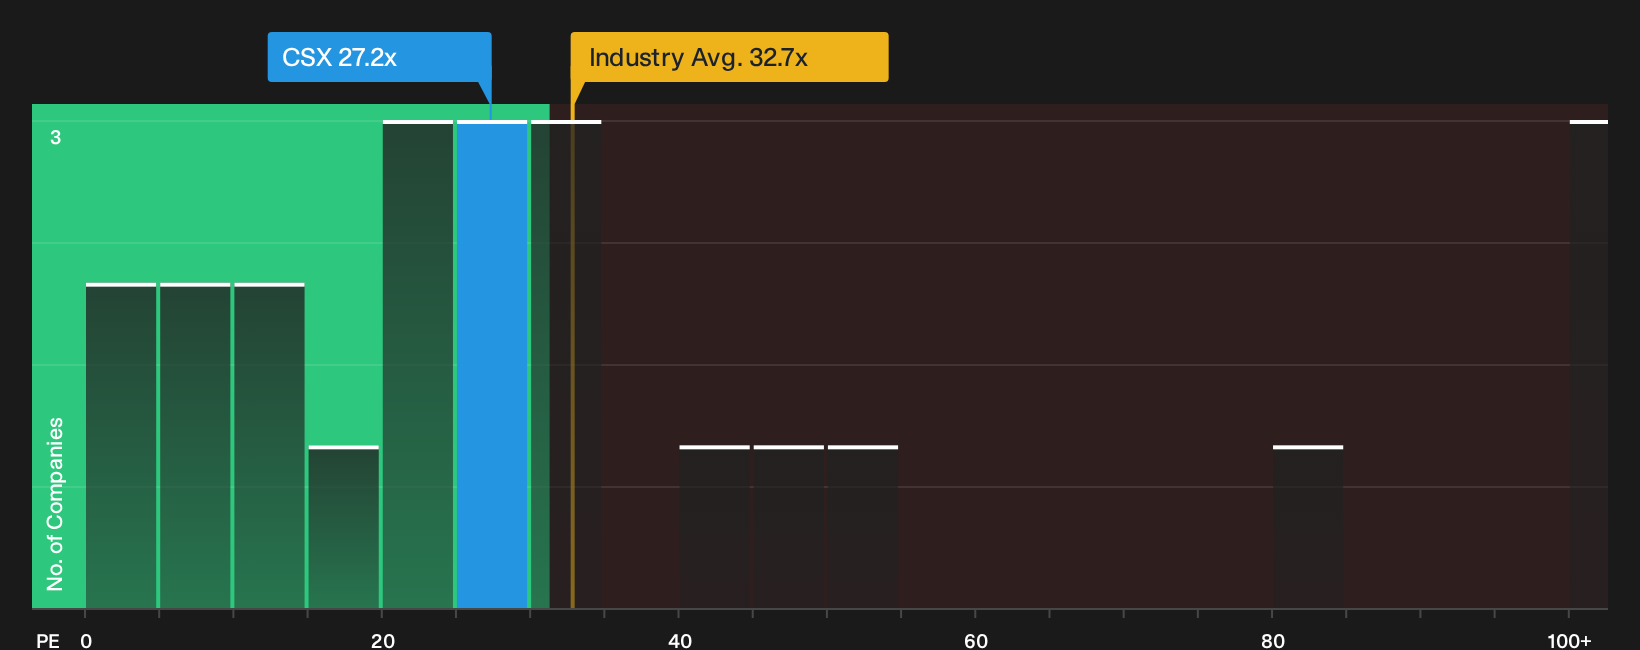
CSX screens differently once you move away from that US$53.10 narrative fair value and look at the P/E. The shares trade on 27.2x earnings, which is below the wider US transportation sector at 32.7x but above both the peer group on 25.4x and the fair ratio of 20.5x. That mix points to a rail operator priced richer than close comparables yet with less room above a level the market could eventually gravitate toward, so investors need to ask whether the story justifies paying up today or whether patience around entry price matters more.
To pressure test that P/E view against the underlying numbers, take a closer look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sensing mixed sentiment around CSX after the recent run and pullback, you can move quickly, test the upside story against the weak spots, and decide where you land by reviewing the 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond CSX?
If CSX has your attention, do not stop there. Broaden your watchlist now and give yourself more ways to benefit from the next wave of market moves.
- Target potential mispricing across quality businesses by scanning a focused list of 27 high quality undervalued stocks that combine fundamentals with room for sentiment to catch up.
- Build a sturdier core for your portfolio by reviewing a curated 31 resilient stocks with low risk scores that aims to keep downside surprises in check.
- Hunt for fresh opportunities off the beaten path by checking a concentrated group of 20 high quality undiscovered gems before everyone else pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com