


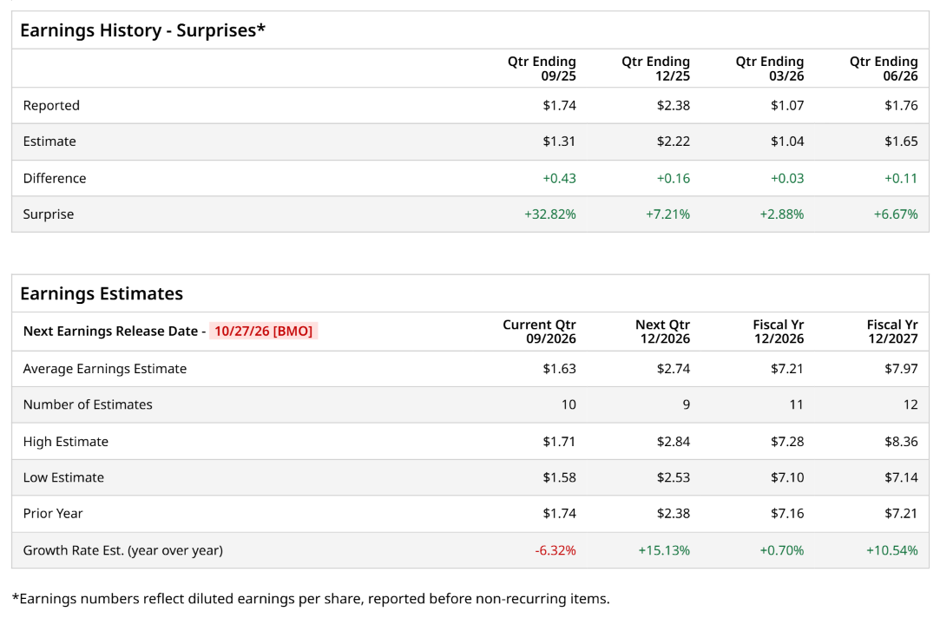
United Parcel Service, Inc. (UPS), headquartered in Atlanta, Georgia, provides transportation and delivery, distribution, contract logistics, ocean freight, airfreight, customs brokerage, and insurance services. Valued at $78.5 billion by market cap, UPS is a leading provider of global supply chain management solutions and delivers packages each business day for 1.6 million shipping customers to 10.2 million delivery customers in over 200 countries and territories. The logistics giant is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Tuesday, Oct. 27.
Ahead of the event, analysts expect United Parcel Service to report a profit of $1.63 per share on a diluted basis, down 6.3% from $1.74 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect United Parcel Service to report EPS of $7.21, up marginally from $7.16 in fiscal 2025. Its EPS is expected to rise 10.5% year over year to $7.97 in fiscal 2027.
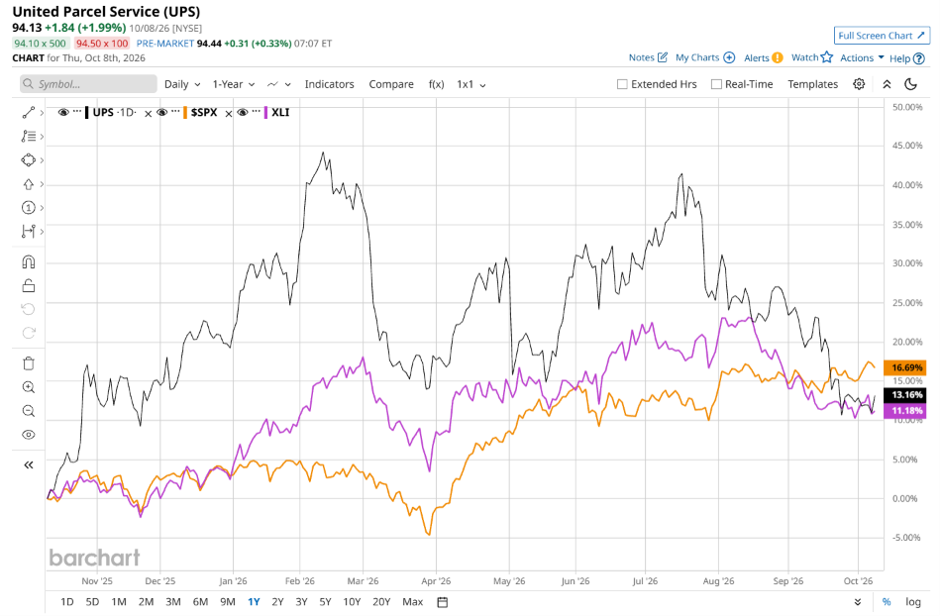
UPS stock has underperformed the S&P 500 Index’s ($SPX) 15% gains over the past 52 weeks, with shares up 9.1% during this period. However, it outperformed the State Street Industrial Select Sector SPDR ETF’s (XLI) 8.2% gains over the same time frame.
UPS reported mixed performance as revenue grew alongside operating profit gains, though overall results were tempered by significant operating margin compression down to 4.1%. The quarter was defined by strategic network adjustments, including the completion of the Amazon.com, Inc. (AMZN) volume glide-down to exit lower-margin business and the closure of 45 facilities in the first half of the year, and an aggressive pivot toward high-yield segments like healthcare logistics (adding 27 temperature-controlled cross-docks), small and medium-sized businesses, and B2B e-commerce. Operationally, efficiency improved as 68.5% of U.S. volume was routed through automated facilities with a 28% lower cost per package, supported by full domestic deployment of RFID and AI digital twins, positioning the company for stronger revenue mix and operating leverage despite ongoing fuel price volatility and competitive headwinds.
Analysts’ consensus opinion on UPS stock is moderately bullish, with a “Moderate Buy” rating overall. Out of 27 analysts covering the stock, 12 advise a “Strong Buy” rating, one suggests a “Moderate Buy,” 11 give a “Hold,” and three advocate a “Strong Sell.” UPS’ average analyst price target is $116.19, indicating a potential upside of 23.4% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.