


With the dollar on its longest winning streak since early 2025, income from UK dividend stocks suddenly matters more. Overseas assets can shift in value quickly when currencies move, but a solid cash payout in pounds can feel like a financial anchor. This article looks at three higher yielding UK shares from a quality focused dividend screen that prioritises cover, consistency and growth, and explains what sets each apart.
The three stocks covered below are only a small sample, and the full Dividend Powerhouses screen surfaced 62 more companies with similar income stories that are not included in this list.
If you want to identify and analyze more potential high conviction dividend ideas straight away, head into the Dividend Powerhouses (3%+ Yield) screener.
Lloyds Banking Group (LSE:LLOY)
Lloyds Banking Group is a UK focused lender. Its dividend appeal in this screener rests on the cash it generates from everyday Retail banking, with the broader Commercial and Insurance arms adding extra income streams around that core.
Lloyds earns about £11.9b from Retail, £5.7b from Commercial Banking, £1.4b from Insurance and £0.8b from Other activities, and has a market value of roughly £57.7b.
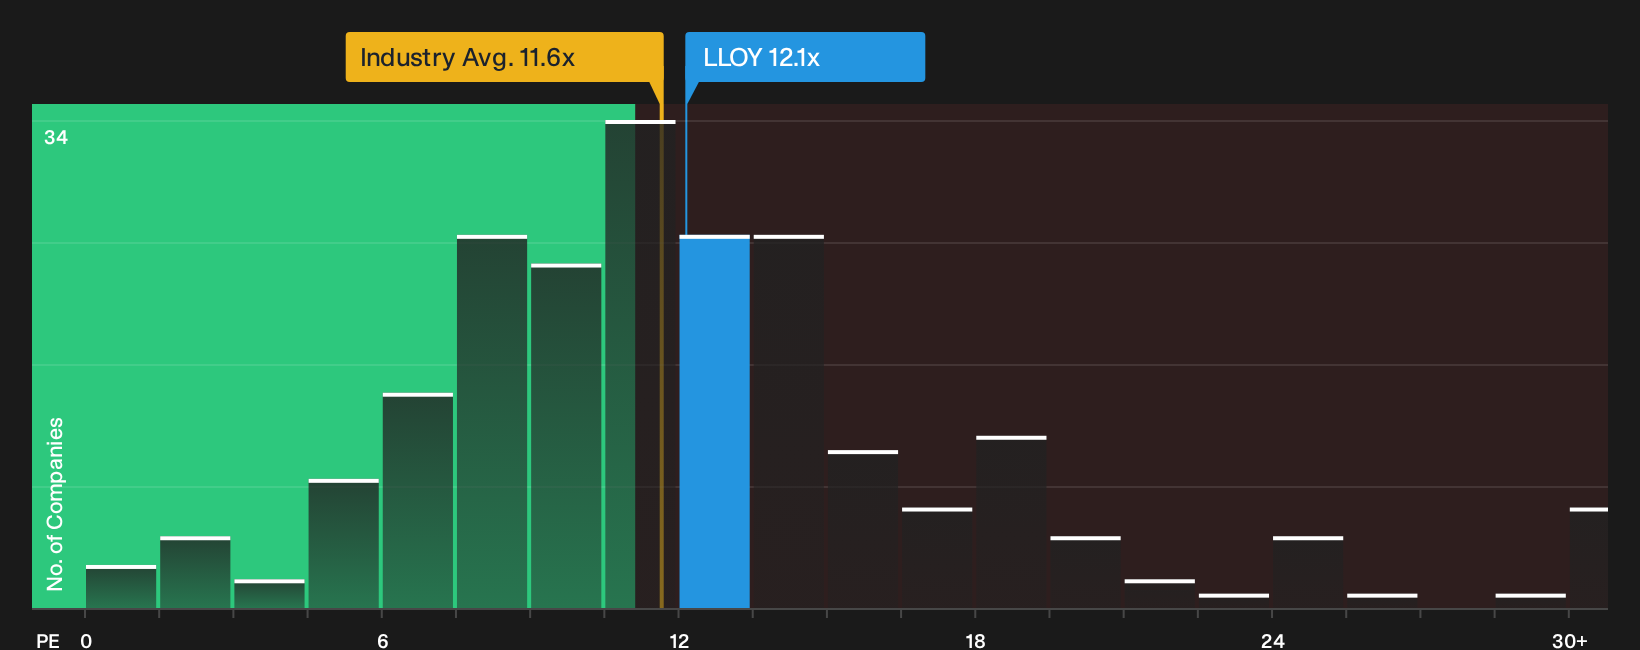
"The new government led by Labour-hopeful Andy Burnham has yet to prove its growth credentials (while making noises that create expectations to the contrary). It is still on the fence as to the introduction of a mooted bank profits surtax, and the banking sector seems to be deflating in general when it comes to P/E multiples."
For income focused investors, what happens if a single key assumption about how much capital Lloyds can return each year quietly shifts?
If that capital return question is on your mind, the full narrative for Lloyds Banking Group shows how Lloyds Banking Group’s income story could be reshaped by shifting payout expectations.
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings turns long term infrastructure and private equity projects into fee income, which in turn underpins its dividend story. Income focused investors often look at how reliably those fees convert into cash that can support payouts and buybacks over time.
Foresight Group Holdings manages real assets such as renewable energy infrastructure and social projects, generating about £114.8 million from Real Assets and £50.1 million from Private Equity, and has a market value of roughly £483 million.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What really matters now is how one less visible pressure shapes the balance between rising costs and those fee rich income streams.
That cost pressure is exactly what the full narrative for Foresight Group Holdings unpacks, showing where Foresight Group Holdings’ fee engine could quietly accelerate returns if conditions line up.

HSBC Holdings (LSE:HSBA)
HSBC Holdings runs a global banking platform, yet its mature UK and Hong Kong consumer franchises are the income engines that tie it to a 3%+ yield screen. This feeds a dividend story that rests on broad fee and interest streams rather than a single region.
HSBC generates about US$27.5b from Corporate & Institutional Banking, US$15.2b from Hong Kong, US$14.4b from International Wealth & Premier Banking, and US$12.6b from the UK, with a market value near £236.3b.
HSBC Holdings illustrates how a global lender can use everyday savings accounts, mortgages, and wealth products in two mature markets to support a dividend that aims to be both sizable and backed by cash, while the wider group remains exposed to trade flows and corporate finance.
"The bank is intensifying investment in Asian wealth management and private banking, leveraging a strong brand and local presence in fast-growing wealth markets like Hong Kong, mainland China, and Southeast Asia; this positions HSBC to capture rising affluence and middle class expansion, fueling future growth in fee income and supporting more resilient earnings and higher margins."
What could significantly influence the story is how a relatively small change in credit quality shapes the gap between healthy earnings and the dividend cheques that are ultimately paid.
If that earnings gap is what you are watching, the full narrative for HSBC Holdings shows how HSBC Holdings’ credit trends, Asia pivot and payout ambitions could be quietly decoupling expectations.

Seeking Alternatives Before The Crowd?
Fresh ideas move first, and the best income and growth stories often start breaking out while most investors are still caught watching old momentum drop away. Consider acting before trends become crowded.
- Identify dividend engines with durable cash flows and let the 4 dividend fortresses guide you toward income plays that could help keep portfolios funded while others focus on headlines.
- Explore potential future infrastructure workhorses by scanning the 43 power grid technology and infrastructure stocks and focus on businesses tied to essential networks that may remain active even when sentiment cools.
- Research the next automation wave early and use the 91 robotics and automation stocks to find companies involved in the hardware and software behind productivity gains in multiple industries.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com