


Icahn Enterprises (IEP) sits in focus for investors after recent trading left the units at $6.64, with the conglomerate’s mix of investment, energy, automotive and other operations drawing fresh scrutiny.
Recent trading fits a longer pattern for Icahn Enterprises, with the 30-day share price return down 3.9% and the 90-day share price return down 11.4%. The 1-year total shareholder return of 4.4% contrasts with a 5-year total shareholder return that is lower by 66.9%, suggesting short term momentum has softened after a long stretch of value erosion.
Compare Icahn Enterprises' recent swings with a hand-picked group of diversified, potentially mispriced companies using the 27 high quality undervalued stocks for fresh ideas beyond a single conglomerate.
Icahn Enterprises now trades at a clear discount to some fair value estimates, yet the recent rebound in 1 year returns muddies the picture. Is the current US$6.64 price too low or already generous?
Preferred Multiple of 0.5x: Is it justified?
Valuation work around Icahn Enterprises currently leans on a low P/S ratio, with the units trading on roughly 0.5x sales. That sits alongside the last close of $6.64 and frames the discount conversation against both peers and the wider Industrials space.
The P/S metric compares the market value of Icahn Enterprises to the revenue it generates. For a complex partnership with energy, automotive, real estate, and other activities under one umbrella, this measure helps strip away short term earnings swings and focuses on how much investors are paying for each dollar of sales.
Based on Simply Wall St’s checks, Icahn Enterprises is described as good value on this yardstick. The 0.5x P/S sits well below a peer average of 2.1x and also below the global Industrials average of 0.8x. This indicates the units change hands at a much lower revenue multiple than comparable businesses.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-sales of 0.5x (UNDERVALUED)
Still, Icahn Enterprises carries clear risks, including recent multiyear total return declines and a reported net loss of US$515m that could pressure sentiment further.
Find out about the key risks to this Icahn Enterprises narrative.
Another view on Icahn Enterprises' value
The low 0.5x P/S ratio sketches Icahn Enterprises as cheap on sales, yet a different lens gives a more cautious twist. Simply Wall St’s DCF model points to a future cash flow value of $9.12 per unit, with the current $6.64 price sitting about 27% below that estimate. Is this a genuine margin of safety or a signal that the cash flow assumptions need a closer look?
Look into how the SWS DCF model arrives at its fair value.
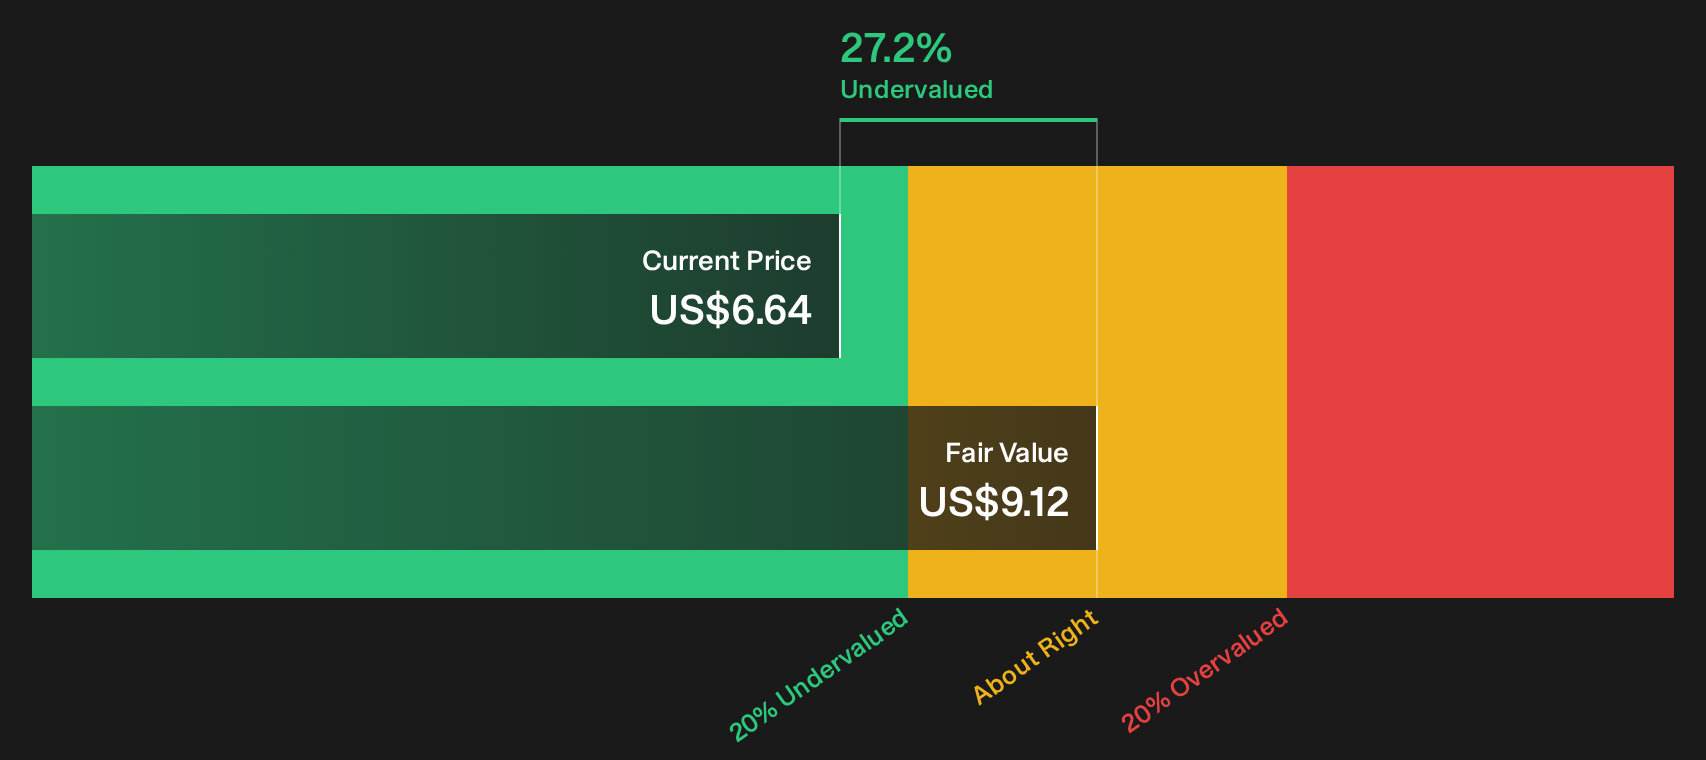
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Icahn Enterprises for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Questions around Icahn Enterprises' valuation and mixed recent performance can stir up strong views, so move quickly, pull up the underlying figures, and stress test the story for yourself. To see the full balance of potential upside and the key issues investors are watching, start with this breakdown of 1 key reward and 3 important warning signs
Looking for more investment ideas beyond Icahn Enterprises?
If Icahn Enterprises has sharpened your focus on value and risk, do not stop here. Broader opportunity sits with other stocks that fit your criteria.
- Target resilient cash generators that still trade below what their financials suggest by scanning the 27 high quality undervalued stocks.
- Lock in potential income streams by screening for consistent payers across the 8 dividend fortresses.
- Hunt for under-the-radar opportunities with strong fundamentals before the crowd arrives by working through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com