


Descartes Systems Group (TSX:DSG) rolled out its new Agent Control Plane at the 2026 Innovation Forum in Chicago, spotlighting AI driven logistics workflows even as broader trade and valuation worries kept investor enthusiasm in check.
Recent trading tells a mixed story for Descartes Systems Group. The share price at CA$115.46 has a 1-month share price return of 10.94% and a 3-month share price return of 13.22%. However, the year to date share price return is down 1.28% and the 1-year total shareholder return has declined 15.23%. This points to recovering but still cautious momentum as new AI driven products arrive against a backdrop of trade and valuation concerns.
Spot 92 AI infrastructure stocks that, like Descartes Systems Group, are leaning into AI driven workflows, even as trade risks and rich pricing keep sentiment on a short leash.Descartes Systems Group now trades at a roughly 28% intrinsic discount, even after the recent rebound. Is that a case of the market being too harsh on trade and valuation worries, or just realistic caution?
Most Popular Narrative: 10% Undervalued
On the most followed view of Descartes Systems Group, a fair value of CA$128.28 sits above the CA$115.46 last close, which frames today’s discount through the lens of growth, margins and trade complexity.
Heightened global trade complexity and rapid regulatory changes, including new tariffs, elimination of de minimis import exceptions in the US, and shifting international trade agreements, are driving sustained demand for Descartes' advanced global trade intelligence, customs, and compliance platforms, which is expected to boost recurring services revenue and underpin organic growth.
See why 24 investors see Descartes Systems Group as 10% undervalued.
Result: Fair Value of CA$128.28 (UNDERVALUED)
Still, the Descartes Systems Group narrative can crack if global trade policy keeps clients cautious or if acquisition led growth stumbles and integrations misfire.
Find out about the key risks to this Descartes Systems Group narrative.
Another View On Descartes Systems Group’s Valuation
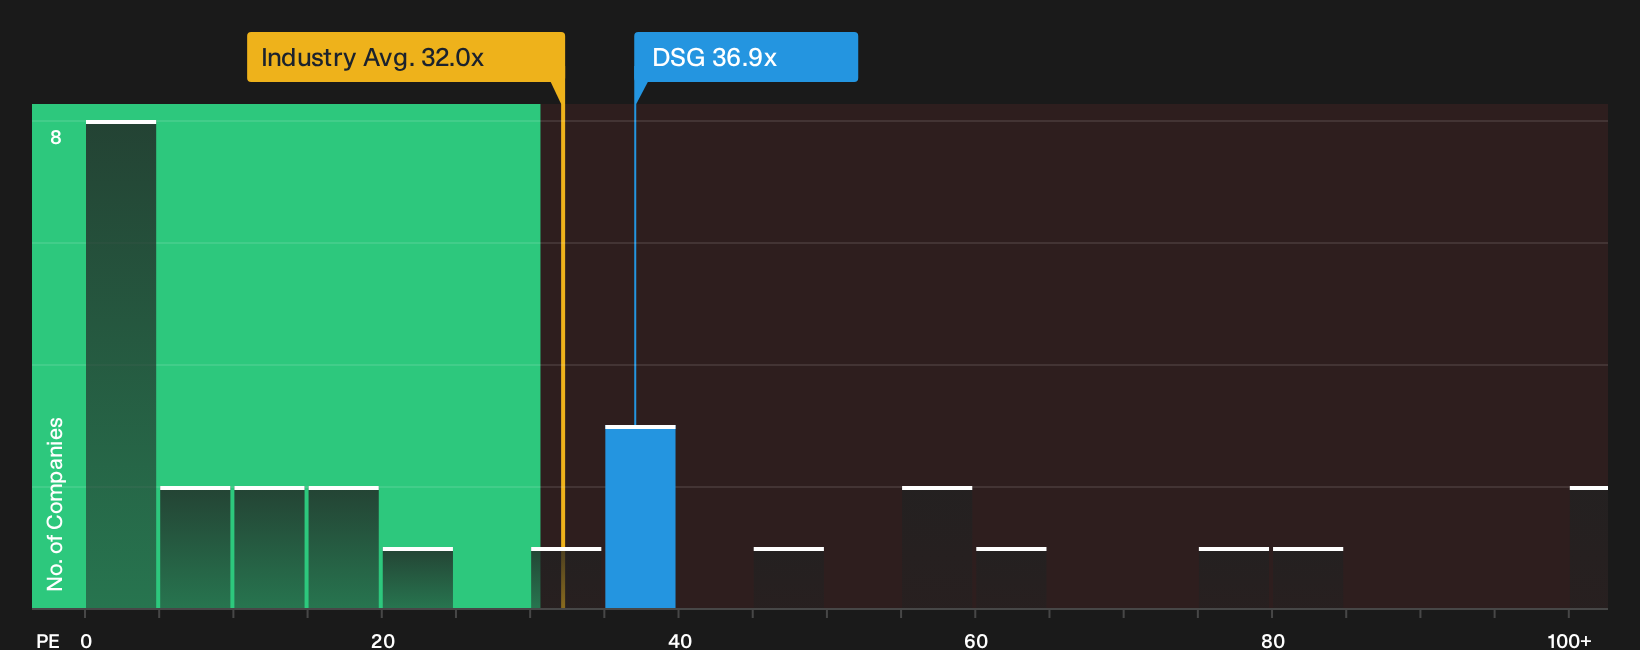
There is a catch. Descartes Systems Group looks undervalued against the CA$128.28 fair value, yet its 36.9x P/E is higher than the North American Software industry at 31.7x and well above a 25x fair ratio. This points to richer expectations if earnings stumble.
That disconnect between discounted fair value and a premium P/E raises a practical question for you as an investor: is this an early entry into a quality compounder, or are you paying up for growth that is already well recognized in the multiples?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Descartes Systems Group can pull you in both directions, so move quickly and test the story against the underlying numbers yourself, starting with 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Descartes Systems Group?
If Descartes Systems Group has you thinking harder about price, quality and risk, take the next step and widen your watchlist using focused screeners on Simply Wall St.
- Target potential bargains by scanning a curated pool of quality companies trading on apparent discounts through the 7 high quality undervalued stocks.
- Prioritise resilience and sleep a little easier at night by filtering for businesses with sturdier finances using the list of solid balance sheet and fundamentals (7 results).
- Hunt for underfollowed opportunities before the crowd catches up by tapping into the 9 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com