


- Capital One Financial drew investor focus after its combination with Discover and its heavy spending on cloud, AI and analytics, aimed at lowering fraud and servicing costs while using a proprietary payments network to support fee and interchange revenue.
- The integration of Discover’s payments rails with Capital One Financial’s technology overhaul creates a scaled data and transaction platform that could influence credit risk management, operating efficiency and how the bank cross sells lending and deposit products.
- The next area of attention is how Capital One Financial’s Discover integration and technology spending may reshape its longer term investment narrative and risk profile.
Capital One Financial Investment Narrative Recap
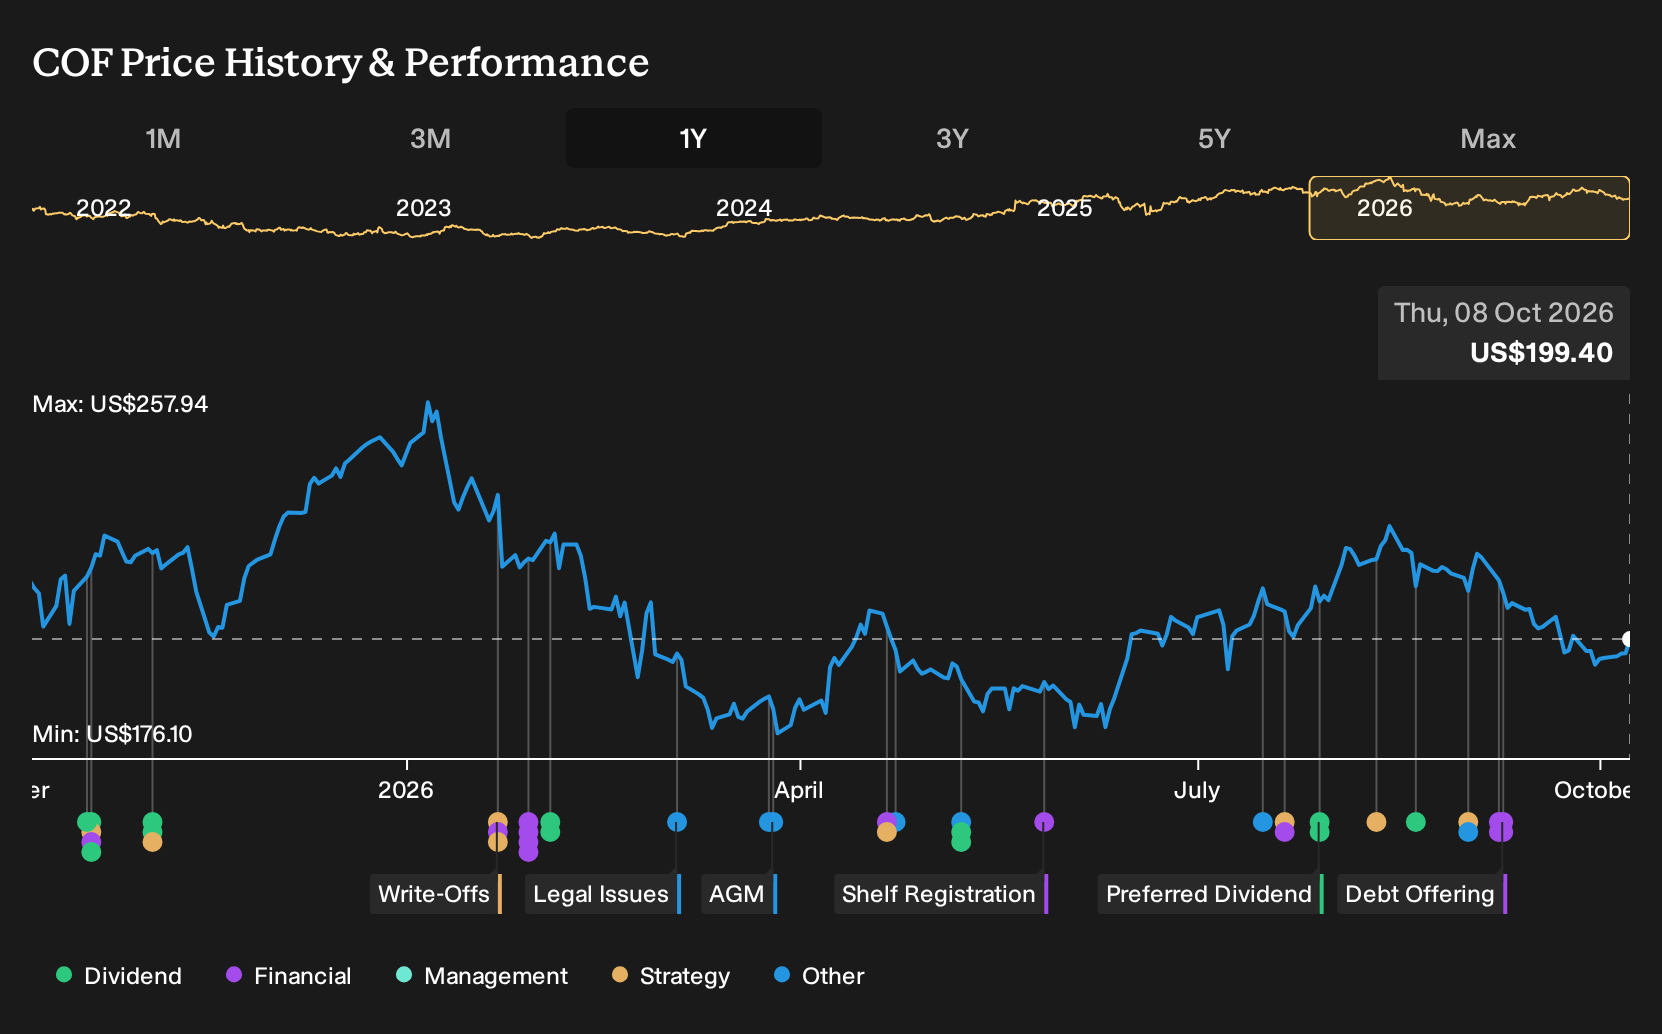
To own Capital One Financial, you need to believe the Discover deal and heavy AI and cloud spending translate into a more efficient, data rich payments and lending platform. The recent move in the share price to US$199.40 on 6 October 2026 does not change that core thesis, but it does sharpen attention on execution.
Right now, the key near term swing factor is whether Discover integration and AI driven fraud controls keep credit outcomes and operating costs stable while the firm is still spending heavily. The biggest risk is that technology, marketing and integration expenses stay high while revenue synergies and cost savings arrive slower than planned.
Against this backdrop, the most relevant recent development is the push to run more Capital One Financial debit and some credit volume over the Discover network. That creates a clear operational test. The bank needs to show that using its own rails can sustain fee and interchange income while supporting the AI and analytics work that is meant to reduce fraud and servicing expense.
If that network migration progresses smoothly, it supports the broader payments ecosystem Capital One Financial is building around consumer cards, small business products and the Brex commercial platform. Any integration delays, fraud issues or regulatory friction around data and network economics would work against the expected synergy targets and could weigh on how investors view those catalysts.
Capital One Financial Consensus Assumptions To Watch
Analysts are effectively betting that Capital One Financial can turn the Discover integration and AI spend into a much larger business by the end of the decade without losing too much profitability along the way. The current blueprint has revenue growing at 18.3% a year for the next three years, while profit margins step down from 20.4% today to 18.0% over that same stretch as technology and marketing outlays stay elevated.
On earnings, the consensus clusters around a move from US$9.8b today to US$14.3b by 2029, helped by that higher top line and supported by an assumed 3.5% yearly reduction in shares outstanding for the next three years. That shift implies earnings rising by about US$4.5b even as margins compress, which puts real weight on the Discover rails, AI driven fraud controls and the broader payments ecosystem to carry more transactions and support fee income.
All of this feeds into how the stock is currently framed. The market is being asked to accept Capital One Financial at a P/E of 12.6x today on current earnings, with analysts effectively penciling in a modest move to 12.7x on those projected 2029 profits, a level above the 9.1x multiple cited for the wider US consumer finance peer group.
Capital One Financial's narrative projects US$79.6b revenue and US$14.3b earnings by 2029. This rests on 18.3% yearly revenue growth and an earnings increase of about US$4.5b from US$9.8b today.
Uncover why Capital One Financial's fair value indicates a 30% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts far more weight on macro risks for Capital One Financial. The most pessimistic analysts were assuming revenue of about US$74.3b and earnings of roughly US$10.5b by 2029 before this news. That lower bar reflects worry about tariffs and a weaker economy, and it shows how wide opinion can run.
Explore 4 other Capital One Financial fair value estimates, including one that suggests it could be worth just $225.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and approach.
- A great starting point for your Capital One Financial research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Capital One Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capital One Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Capital One Financial?
If the Capital One Financial story has you thinking about where else AI, payments and balance sheet strength might create opportunities, it can help to scan a wider field of stocks with similar traits using the Simply Wall St Screener.
- For investors who want quality at a reasonable entry point, check stocks that combine strong business metrics with attractive pricing through the 27 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, filter for companies with more resilient fundamentals using the 31 resilient stocks with low risk scores.
- For readers who care about financial strength before anything else, start with a list of solid balance sheet and fundamentals (25 results) that already clears basic debt and liquidity checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com