


CarMax (KMX) is back in focus after a cluster of company updates, including fresh executive appointments tied to its Shift into GEAR plan and second quarter earnings with higher sales and net income versus last year.
Recent price action shows that CarMax shares have slipped, with a 30-day share price return of down 11.19%, even though the year to date share price return is up 36.91% and the 1-year total shareholder return is 21.95%. This suggests momentum has cooled after a stronger run as investors reassess the earnings beat, leadership changes and the completed multi year buyback program.
Spot 27 high quality undervalued stocks that, like CarMax after its earnings and leadership shake up, may be resetting expectations and preparing for their next move.CarMax just reported stronger profit figures and refreshed its leadership team, yet the share price has slipped in recent weeks. Is this mainly a reset in sentiment, or does it flag something deeper about what the business is worth today?
Most Popular Narrative: 1% Undervalued
On the Simply Wall St narrative, CarMax is priced close to its estimated fair value, with the $53.79 last close sitting just under a $54.09 narrative fair value. That tiny gap frames the earnings beat and leadership reset less as a bargain and more as a question about how durable the recent improvement really is.
TheGapReport: CarMax, Inc. (NYSE:KMX) Q2 2027 (jun 17 to sep 29)
CarMax reports fiscal second-quarter 2027 results, with used comps at 13%, up from a 0.8% decline the quarter before, and a full-year guide that still has gross profit per used unit falling by less than $200. The line worth reading sits beneath both numbers; the June pledge to fund lower prices through efficiency rather than margin now surfaces mainly in analyst answers, with a fiscal 2028 date, a softer verb, and two more quarters of lower margin in front of it.
See why 1 investors see CarMax as 1% undervalued.
Result: Fair Value of $54.09 (ABOUT RIGHT)
Still, the narrative around CarMax could be tested if management softens its efficiency pledges further or if web traffic slippage begins to erode recent comp strength.
Find out about the key risks to this CarMax narrative.
Another View: What CarMax’s P/E Is Pricing In
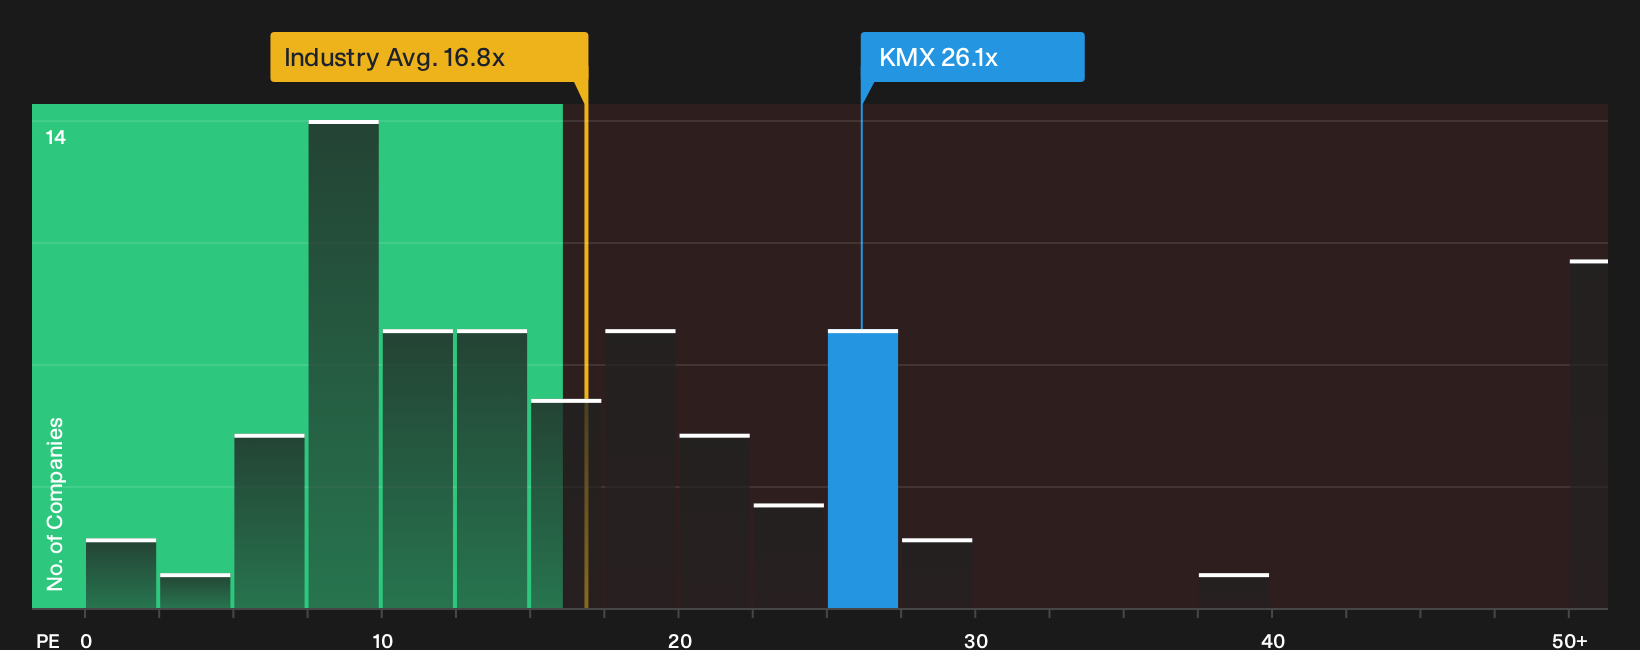
The fair value narrative pins CarMax close to $54, yet the market is already paying a rich multiple for that story. At a P/E of 26.1x versus 11.3x for peers and 16.7x for the US Specialty Retail group, as well as a fair ratio of 21.4x, investors are accepting less margin for error if earnings forecasts slip.
That kind of premium can look justified if the profit ramp materialises as expected, or it can compress quickly if sentiment turns. The question for anyone watching KMX is simple: does this higher multiple feel like a cushion, or more like thin ice?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around CarMax is clearly split, with fresh profit figures and leadership changes weighed against both flagged risks and potential upsides that investors are watching closely. To stress test your own thesis before the market moves again, start with the 1 key reward and 3 important warning signs.
Looking for more CarMax sized investment ideas?
If CarMax has you rethinking where the next opportunity might come from, use the time while sentiment resets to scan for other stocks with compelling setups.
- Target resilient businesses with pricing that still looks compelling by scanning our broad universe for 27 high quality undervalued stocks before the crowd catches on.
- Lock in potential income streams by focusing on companies in our 8 dividend fortresses that pair yield with balance sheet strength.
- Hunt for underfollowed opportunities using the 20 high quality undiscovered gems and get ahead of investors who only react once a story is already crowded.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com