


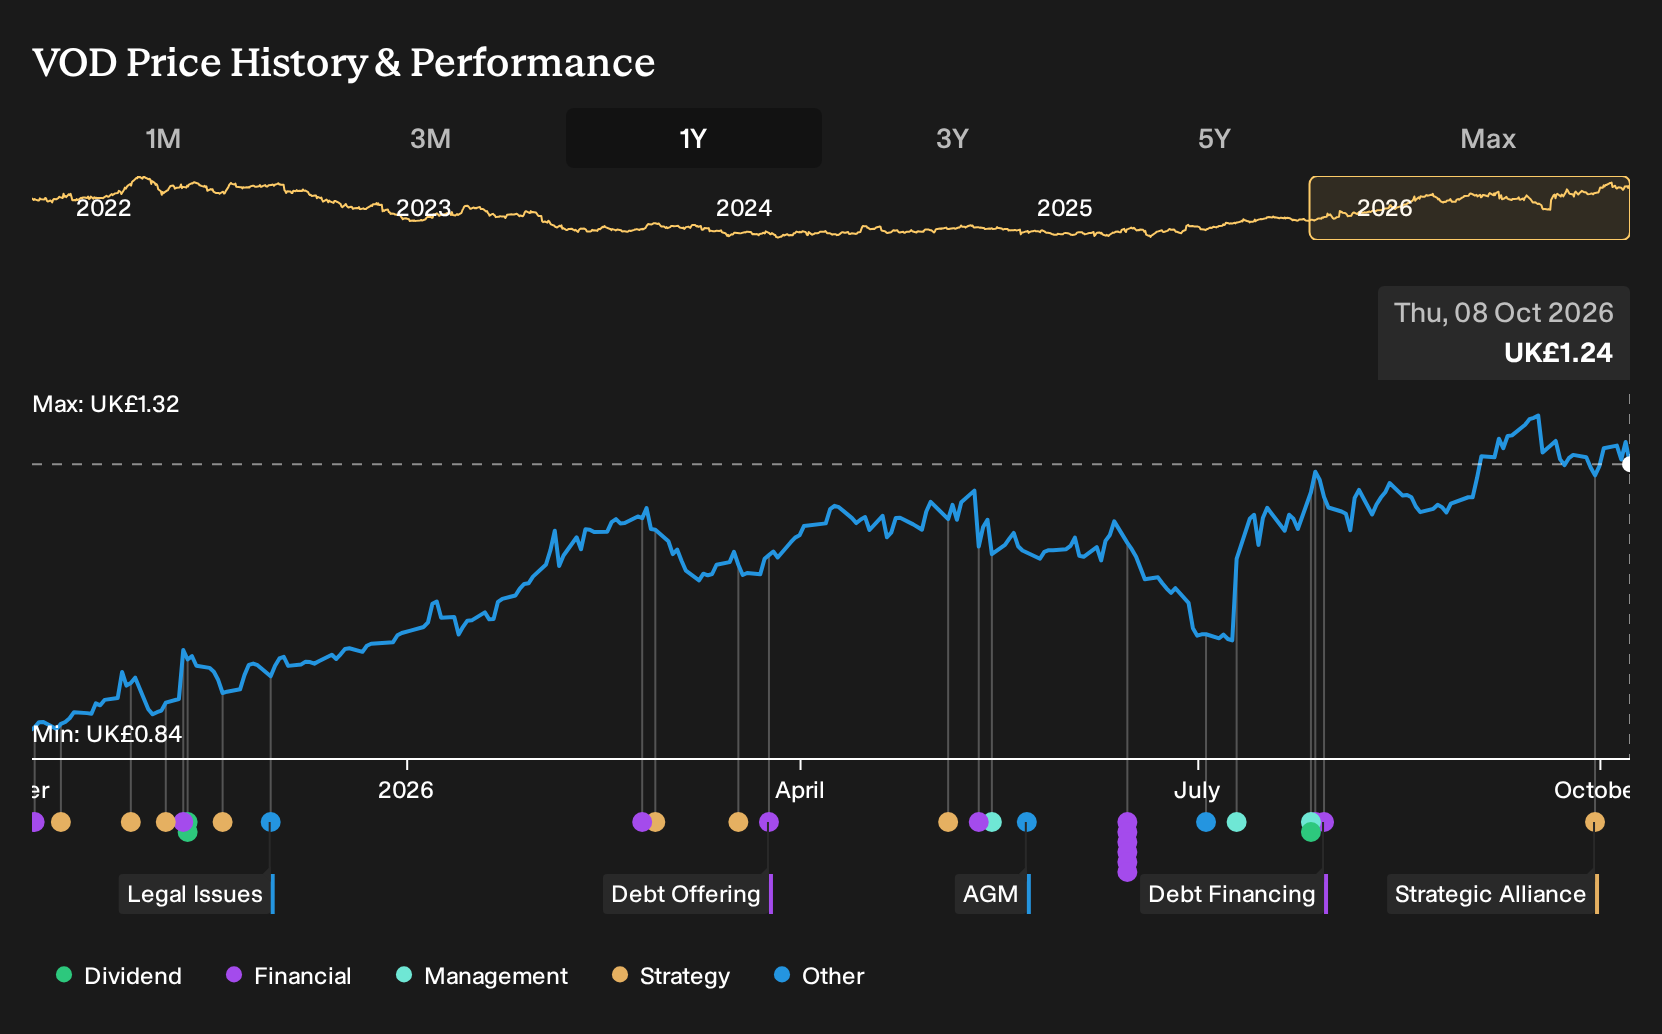
If Vodafone Group sat on your watchlist instead of in your portfolio over the past year, the return may sting. Investors who held Vodafone Group over the past year are up 51.5%, including dividends. That move arrived against a backdrop of bullish forecasts around IoT and 5G driven digital transformation on one side and concerns over rising European compliance costs and shrinking legacy services on the other. If you had been deciding on 8 October 2025, how confident would you have been that digital platforms and 5G scale, rather than regulatory drag, would matter more for the next twelve months?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Vodafone Group. Zero in on 7 high quality undervalued stocks for companies trading below our estimates.
The Two Vodafone Group Stories Investors Had To Balance
The shares cost £0.85 at the start of the period, and Vodafone Group sat between two sharply different but reasonable stories about where the business could head next.
On the bullish side, the IoT And 5G Trends Will Drive Digital Transformation Narrative put Fair Value at £1.36. This view was built on the idea that digital platforms, IoT and 5G services could support higher margins and cash flow than many expected.
The bearish Rising European Compliance Costs Will Erode Legacy Services view set Fair Value at £0.6. This perspective focused on the risk that heavier regulation and shrinking legacy voice and SMS would pressure profitability despite efficiency efforts.
What The Results Changed For The Vodafone Group Story
The clearest shift came from Vodafone Group’s FY26 delivery. Total revenue moved from €37,448m in H2 2025 to €40,461m in H2 2026, and the net loss narrowed from €4,147m to €289m, with net margin improving from -11.1% to -0.7%. Profitability is still not positive; the digital transformation case gained support but was not fully proven.
The episode hinged on one assumption: higher margin 5G and digital services needed to show up in reported revenue and net margin. When you assess another telecom, check whether each set of results brings that margin line closer to sustained profit, rather than only lifting the top line.
What Vodafone Group's Price Already Assumes
Vodafone Group now trades at £1.24, and the selected Narrative places its Fair Value below that level. The current view is that the recent 51.5% gain over the past year already prices in a lot of good execution news.
This Narrative highlights German EBITDA pressure as the key drag, while Africa and the VodafoneThree UK merger are treated as the main offsets. Anyone paying today’s price is effectively assuming free cash flow ambitions hold up, so the question is how much room is left if Germany stays weak for longer.
"Although Vodafone Group points to continued good growth in adjusted EBITDAaL and free cash flow and has set an ambition for double digit free cash flow growth, the expectation that Germany's EBITDA will decline again in FY 27 due to TV and mobile pricing headwinds introduces a risk that group earnings fall short of these goals if the largest European market does not stabilise as assumed."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 36% below our estimate - targets underpenetrated energy transition assets where fee income scales with managed capital.
- Company 2 - 26% below our estimate - uses everyday supplement demand and new distributors to push in-house production utilization higher.
- Company 3 - 24% below our estimate - attracts senior legal professionals to a tech platform sharing revenues and reducing legacy overheads.
Those are three of them. See the full list of 9 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com