


Nanjing Leads Biolabs (SEHK:9887) recently drew investor attention after reporting revenue of CN¥213.224 million alongside a net loss of CN¥266.958 million. The figures highlight a clinical-stage biotech that is balancing growth ambitions with ongoing development costs.
Recent trading tells a cautious story. The latest share price of HK$45.56 comes after a 30-day share price return that fell 27.91% and a 1-year total shareholder return that declined 34.82%, suggesting momentum has cooled as investors reassess Nanjing Leads Biolabs amid its widening losses.
Scan opportunities beyond Nanjing Leads Biolabs by comparing its recent pullback against our hand picked 619 high quality undiscovered gems that also pair early-stage growth stories with meaningful business traction.
Those declines reset expectations around Nanjing Leads Biolabs and its loss making profile. After that pullback, does the potential payoff from its drug pipeline still justify the risk at this valuation?
Preferred Price-to-Sales of 35.6x: Is it justified?
Nanjing Leads Biolabs currently trades on a price-to-sales, or P/S, ratio of 35.6x, which is rich relative to both peers and the wider Hong Kong Biotechs industry given the latest close at HK$45.56. That premium sits uncomfortably beside a loss making profile and a share price that has already pulled back sharply over the past year.
The P/S multiple compares the market value of the equity to its revenue base, which tends to matter most for early stage biopharma where profits are still some way off. In this case, the valuation rests on what investors are willing to pay today for CN¥213.224 million of reported revenue from a clinical stage pipeline that is still working through development and has yet to generate positive earnings.
Analysts expect revenue to grow quickly over the coming years and forecast Nanjing Leads Biolabs to move into profitability. This expectation helps explain why the market has previously been willing to assign such a high sales multiple. Even so, the current P/S of 35.6x is described as expensive compared with the Hong Kong Biotechs industry average of 10x and a fair P/S level of 15.7x, which is a level the valuation work suggests would be more aligned with sector norms and fundamentals.
Explore the SWS fair ratio for Nanjing Leads Biolabs.
Result: Price-to-sales of 35.6x (OVERVALUED)
Still, Nanjing Leads Biolabs faces clear pressure points if clinical results disappoint or if funding needs rise faster than its HK$8.81b market value implies.
Find out about the key risks to this Nanjing Leads Biolabs narrative.
Another View: DCF Signals A Very Different Price For Nanjing Leads Biolabs
Revenue based metrics only tell part of the story. Our DCF model values Nanjing Leads Biolabs future cash flows at HK$18.70 per share, which is well below the current HK$45.56 level. This indicates an overvalued profile on this particular valuation measure. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
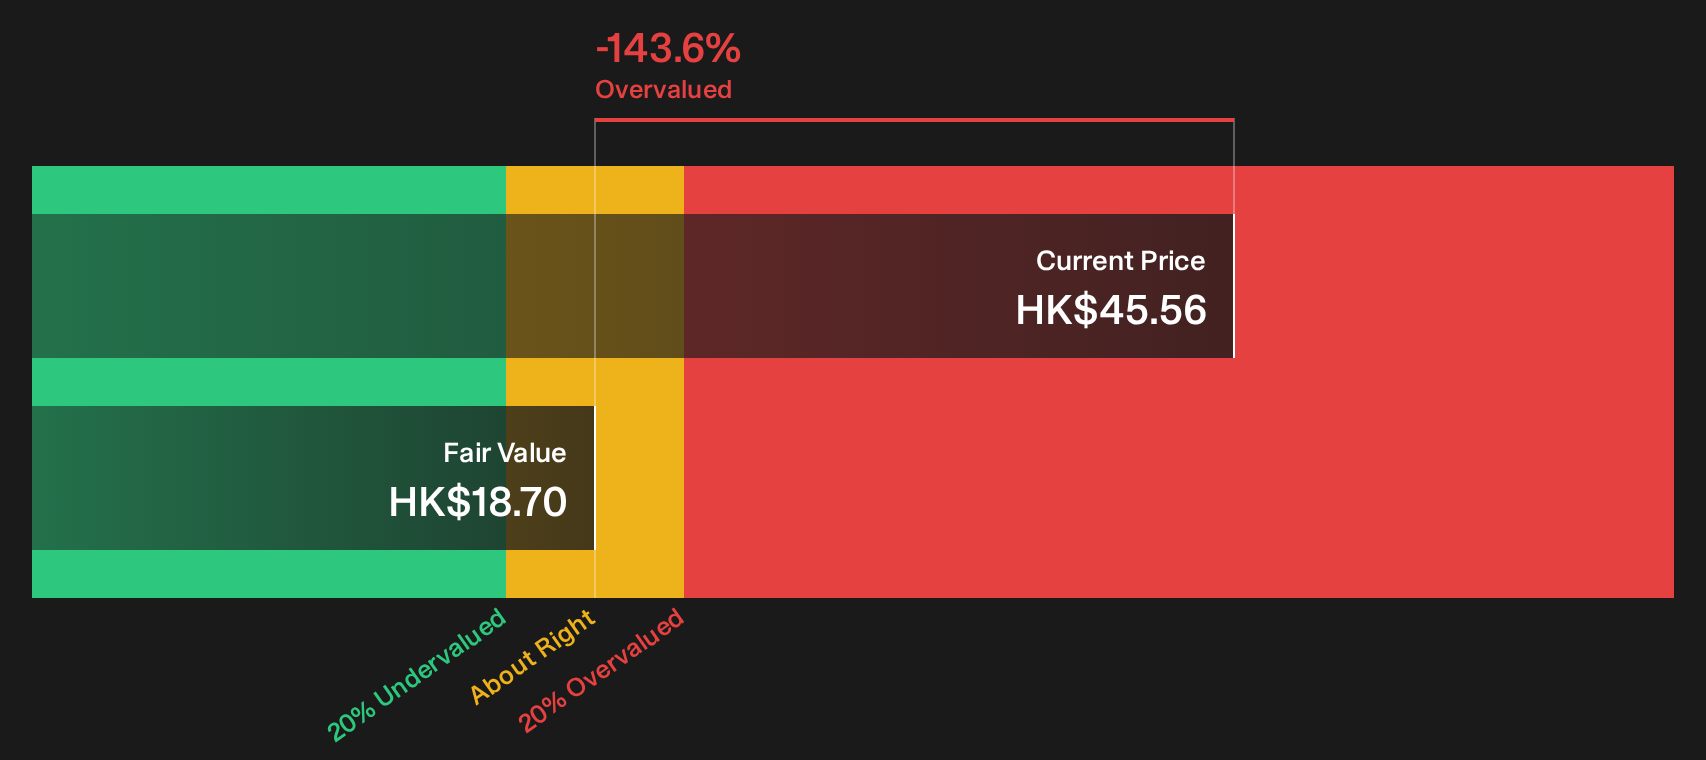
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nanjing Leads Biolabs for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 178 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Nanjing Leads Biolabs so far. If you want to move fast and build your own conviction, consider both the upside and the warning signs in the full 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Nanjing Leads Biolabs?
If Nanjing Leads Biolabs feels too finely balanced, consider broadening your watchlist with targeted screeners that surface clear opportunities before the crowd closes the gap.
- Target stronger value by reviewing companies flagged in the 178 high quality undervalued stocks where quality fundamentals and pricing look out of sync.
- Prioritise resilience by focusing on businesses in the 225 resilient stocks with low risk scores that pair steadier risk profiles with more predictable financial characteristics.
- Strengthen your core holdings by scanning the list of solid balance sheet and fundamentals (205 results) so you do not miss out on sturdier balance sheets when markets turn.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com