


- Marcus & Millichap recently arranged the sale of the UpLift Self Storage Portfolio in Wisconsin and The Groves Apartments in Washington, covering roughly 1,300 storage units and 366 multifamily units respectively, with Marcus & Millichap and its Institutional Property Advisors division representing parties on both transactions.
- These two closings highlight Marcus & Millichap’s active deal flow across self storage and multifamily, reinforcing its fee-driven brokerage model at a time when execution on large, income producing assets can be critical for sustaining transaction based revenue.
- We will now look at how Marcus & Millichap’s recent self storage and multifamily closings might interact with the existing investment narrative.
Scan other real estate brokers and fee-focused operators that look ready to benefit from similar portfolio deals with our curated 20 high quality undiscovered gems.
Marcus & Millichap Investment Narrative Recap
To own Marcus & Millichap, you need to believe its commission heavy brokerage model can turn cyclical deal flow into relatively steady fee income as commercial real estate capital loosens. Recent closings in self storage and multifamily support that narrative, but the most important near term swing factor is still simple transaction volume. These individual deals help, yet do not fundamentally change that exposure.
The key operational worry right now remains reliance on brokerage commissions in a market where some asset classes face structural pressure and fee compression is a live issue. Talent churn and tech disruption sit in the background as additional risks, especially if deal activity slows and recruiting or tools fail to keep producers engaged.
The upcoming InterFace Net Lease conference appearance on 7 October 2026 looks most relevant for thinking about near term catalysts. Net lease investors focus on income stability and cap rates, and this forum gives Marcus & Millichap a stage to showcase its research, agent depth, and capital markets access across that niche.
If the firm can use events like this to deepen relationships with institutions and private buyers in net lease, it may support pipeline visibility and cross selling across property types. Execution still comes down to converting conversations into closings at acceptable commission levels, which directly ties back to the brokerage heavy revenue mix and the margin pressures already in focus.
Marcus & Millichap's narrative projects US$1.1b revenue and US$81.3 million earnings by 2029. That outlook builds on analysts' assumption of 12.0% yearly revenue growth and an earnings improvement of roughly US$81.9 million, from a loss of US$587.0 thousand today to the 2029 consensus figure.
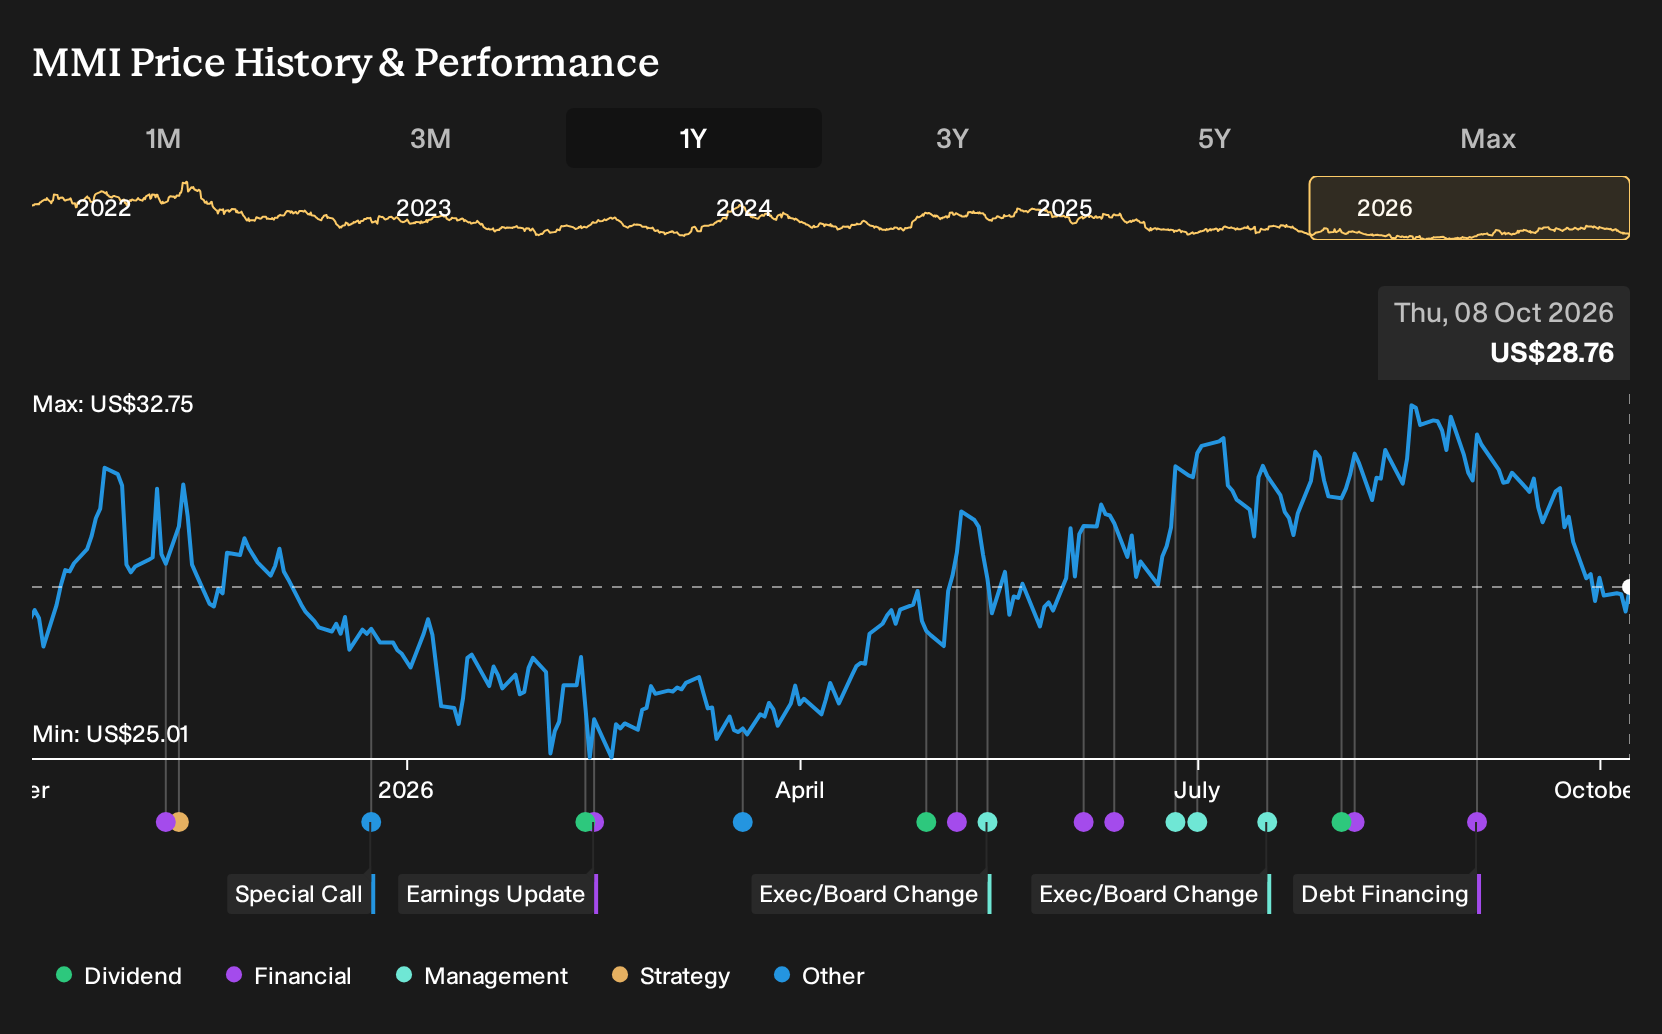
Uncover why Marcus & Millichap's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster in a tight band between about US$26.65 and US$28, which hints at some agreement but also a very small sample of opinions. You still face meaningful debate, given Marcus & Millichap’s heavy reliance on transactions and the push and pull between fee pressure, proptech risk, and potential benefits from institutional capital and M&A. Readers should treat these as just two voices in a wider conversation and seek out more viewpoints before forming a firm valuation view.
Explore another Marcus & Millichap fair value estimate, including one that suggests it could be worth as much as $28.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Marcus & Millichap research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Marcus & Millichap. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marcus & Millichap's overall financial health at a glance.
Looking for more investment ideas beyond Marcus & Millichap?
Once you have a view on Marcus & Millichap, widen the lens and compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who want upside potential with much smaller price tags, scan a focused set of emerging opportunities through 10 elite penny stocks with strong financials.
- If preserving capital is your priority and you prefer steadier profiles, filter for companies with stronger resilience using the 31 resilient stocks with low risk scores.
- For those who care most about robust finances and balance sheet strength, build a watchlist from the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com