


- Golar LNG has acquired the 2013-built LNG carrier Grace Dahlia from NYK Line for conversion into its fourth FLNG unit. The vessel is targeted for redelivery in 2029 with roughly 177,427 cbm of storage at CIMC Raffles’ Yantai shipyard.
- The Grace Dahlia conversion is set to provide about 20% more storage than FLNG Esperanza, which could support greater offloading flexibility and operational scale for future customers.
- We will look at how Golar LNG's investment narrative is affected by adding FLNG #4 using the Grace Dahlia carrier.
Scan how Golar LNG’s FLNG expansion compares with other potentially resilient infrastructure plays by reviewing our curated list of 43 power grid technology and infrastructure stocks today.
Golar LNG Investment Narrative Recap
To own Golar LNG, you need to buy into a simple idea. The business is a specialist in FLNG infrastructure with long dated, contracted cash flow and a plan to scale that model with more units. The Grace Dahlia deal leans into that thesis by expanding future capacity, but it does not change that contracts and execution remain the core drivers.
In the near term, the key catalyst is still how effectively existing FLNG units convert the US$17b EBITDA backlog into cash and support debt and dividends. The biggest risk is that adding FLNG capacity ahead of firm charters layers more CapEx and leverage on a balance sheet where debt is already not well covered by operating cash flow.
With no fresh company announcements beyond the Grace Dahlia purchase, the most relevant reference point is the existing long term FLNG contracts that underpin that US$17b EBITDA backlog. Those agreements shape how much room Golar LNG has to absorb another large conversion project without stretching its financial position.
The combination of contracted cash flows, a forecast step up in earnings, and FLNG #4 as the earliest available capacity creates a clear execution test. Investors will likely watch for charter progress, funding terms, and any update on how additional leverage interacts with dividends that are currently not well covered by free cash flow.
What The Consensus Numbers Assume For Golar LNG
Golar LNG's current analyst narrative leans heavily on a sizeable reset in the income statement over the next few years. Forecasts point to revenue growth of 15.3% a year and a move in earnings from US$163.7 million today to US$501.2 million by 2029. That step up in profit, roughly a 3x increase in absolute terms, would rely on profit margins expanding from 31.3% to 62.4% while the share count edges down by a small 0.28% per year.
On these estimates, 2029 becomes the key reference year. Consensus numbers tie the US$501.2 million earnings figure to revenues of US$802.8 million, which implies much higher profitability on a similar asset base once the current FLNG backlog is fully reflected. The forecast year is also where analyst models anchor their implied P/E of 16.5x, compared with about 30.1x today and a sector marker for US oil and gas stocks around 12.5x.
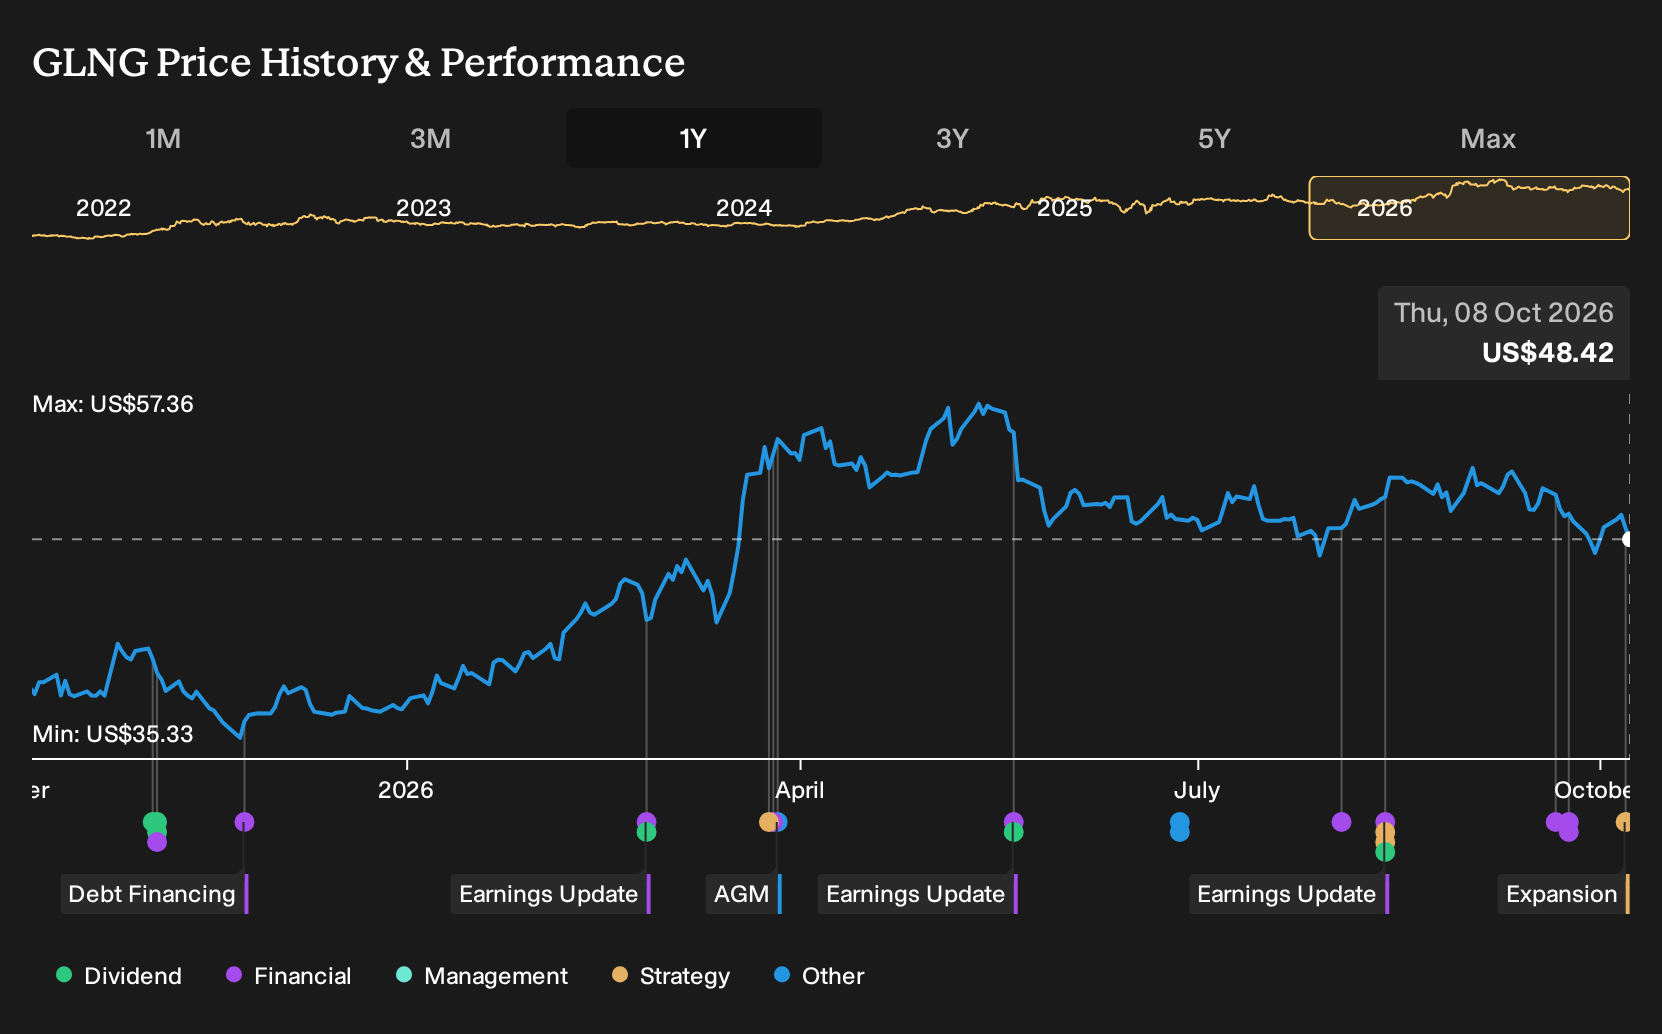
That valuation bridge matters for anyone thinking about how a fourth FLNG could slot into the equity story. The current share price of US$48.23 is being measured against a consensus target of US$66.28, with the most optimistic views at US$75.00 and the most cautious at US$44.50. The spread between those endpoints underlines how much depends on Golar LNG hitting the forecast margin and earnings profile rather than just delivering more tonnage through Grace Dahlia.
Golar LNG's narrative projects US$802.8 million revenue and US$501.2 million earnings by 2029. This assumes 15.3% yearly revenue growth and an earnings increase of about US$337.5 million from current earnings of US$163.7 million.
Discover how Golar LNG's fair value indicates a 37% potential upside to its current price, which could close sooner than many investors expect.
Exploring Other Perspectives
For Golar LNG, the alternate view centers on charter quality rather than sheer growth. The most cautious analysts were only modeling about US$931.5 million of 2029 revenue and US$313.9 million of earnings before this Grace Dahlia news, so they already assumed thinner margins. You can treat this deal as a fresh reason to compare those pessimistic assumptions with more upbeat forecasts and decide which narrative makes more sense to you.
Explore another Golar LNG fair value estimate, including one that suggests it could be worth just $66.28!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Golar LNG research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Golar LNG. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easy to evaluate Golar LNG's overall financial health at a glance.
Looking For More Investment Ideas Beyond Golar LNG?
If the Golar LNG story has sharpened your thinking about risk, contracts, and cash flow, it can be useful to line it up against other opportunities that share some of those traits. The Simply Wall St Screener helps you quickly filter for different profiles so you can build a watchlist that matches your own priorities rather than relying on a single headline idea.
- If you want potential upside with strong financial underpinnings, start by scanning a curated group of 20 high quality undiscovered gems that many investors may not be watching closely yet.
- If balance sheet resilience is your first filter, focus on companies with solid funding and low financial strain by reviewing our list of solid balance sheet and fundamentals (25 results).
- If you prefer to keep downside risk tighter, concentrate on businesses with steadier profiles using our 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com