


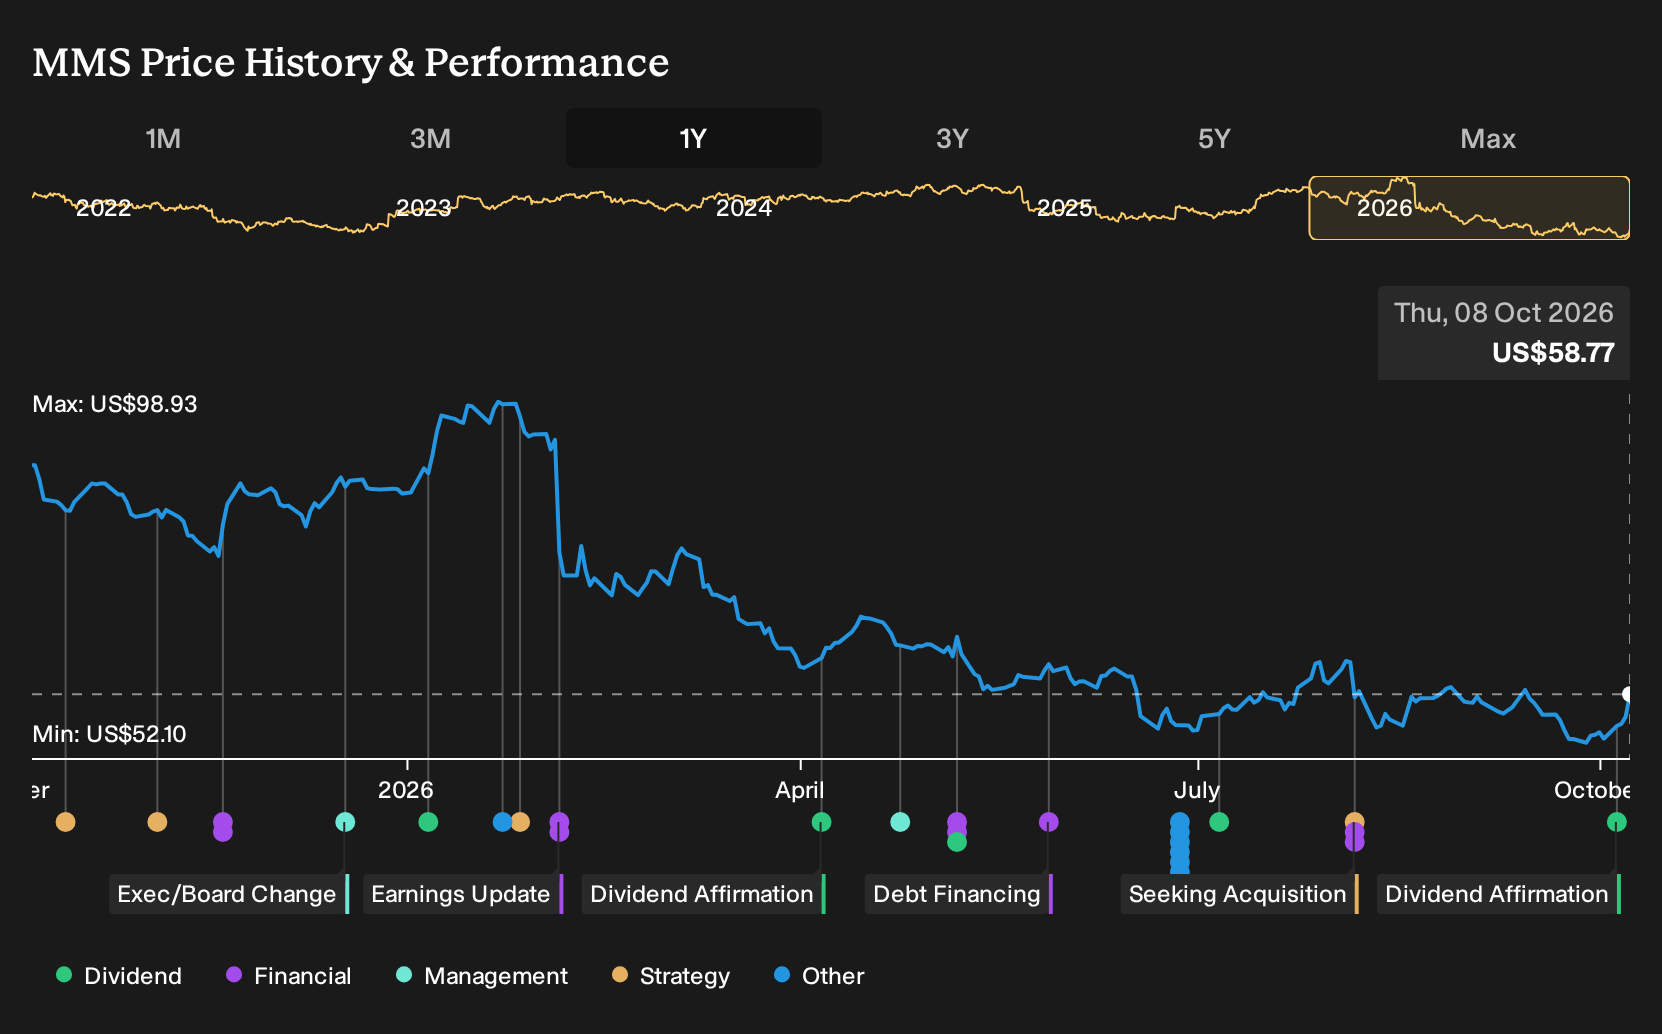
- Maximus reported fiscal Q3 2026 revenue of $1.28b and adjusted EPS of $2.22, broadly matching expectations, while the Board affirmed a quarterly dividend of $0.33 per share payable on November 30, 2026.
- The company cut full year adjusted EPS guidance to a range of $7.90 to $8.20 after a temporary pause in performance incentives on a major VA contract. This highlights how contract terms can directly shape earnings power even when quarterly results track expectations.
- We will look at how Maximus's investment narrative is affected by the lower EPS guidance tied to paused VA performance incentives.
Maximus Investment Narrative Recap
To own Maximus, you need to be comfortable with a contract-driven story where earnings depend heavily on structures set by government clients. The lower adjusted EPS guidance tied to paused VA incentives puts the near-term focus on how quickly those economics normalize and how far U.S. Services can offset any drag from Federal Services.
The key short-term swing factor is still contract conversion and margin on new work in areas such as Medicaid changes and defense and national security. The biggest risk remains longer or broader incentive pauses and low-margin international operations. The latest guidance reset does not change that core equation; it simply makes execution scrutiny tighter.
The dividend affirmation of US$0.33 per share is important here because it highlights cash generation and capital returns while earnings guidance steps down. For an investor tracking Maximus, that payout decision sits alongside the updated US$7.90 to US$8.20 adjusted EPS range as part of the near-term balance of risks and potential rewards.
With the share price down about 32 percent over the past year and the stock described as trading at a low P/E compared with peers, attention shifts to whether contract wins, AI-enabled bids, and program integrity tools translate into steadier earnings. The dividend policy potentially offers some income stability while investors weigh those contract and margin factors against VA-related and international risks.
Maximus's analyst narrative points to forecast revenue of US$6.0b and projected earnings of US$444.7m by 2029, based on an assumed 4.4% yearly increase in revenue and an earnings rise of about US$73.8m from current earnings of US$370.9m.
Uncover why Maximus' fair value indicates a 57% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some analysts focus less on contract risk and more on demand growth for Maximus. Before this dividend news, the lowest targets still assumed revenue of about US$6.1b and earnings near US$458.1m by 2029, yet paired that with a lower implied P/E. That offers you a more cautious lens that may shift as guidance evolves.
Explore 2 other Maximus fair value estimates, including one that suggests there may be as much as 15% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider using your own judgment.
- A great starting point for your Maximus research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Maximus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Maximus' overall financial health at a glance.
Looking for more Maximus-sized investment ideas?
If Maximus has you thinking about contract-driven earnings, balance sheets, and income streams, it can help to set those themes against a wider watchlist. The Simply Wall St Screener lets you scan other companies with similar traits and build a set of comparables that match your own risk tolerance and income needs.
- If you want steadier balance sheets and fewer financial surprises, you can filter for companies with strong fundamentals using this curated 31 resilient stocks with low risk scores.
- If you are income focused and comparing Maximus's payout with others, you can line it up against businesses offering resilient yields through this tailored 8 dividend fortresses.
- If you are hunting for quality that is not widely followed yet, you can broaden your radar with this focused list of 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com