


Shares of consulting giant Accenture (ACN) have had a rough ride on Wall Street this year as fears of artificial intelligence (AI) disruption weighed on the stock. But now, ACN is suddenly back on investors’ radar. One key catalyst was the company’s latest earnings report, which helped restore investor confidence. Then came another boost yesterday, when ACN shares jumped nearly 6% after Accenture announced an expansion of its collaboration with Dell Technologies (DELL), launching the Accenture Dell Business Group to help companies scale AI across private, hybrid, and sovereign environments.
The new group builds on a relationship spanning more than 20 years and is designed to help businesses deploy AI faster while maintaining greater control over their data, more predictable costs, and stronger performance. Accenture also plans to train more than 3,000 practitioners on Dell’s technology to support private AI infrastructure and integrated solutions. The offering will span private AI infrastructure, agentic AI solutions, and open-source models, with the goal of helping businesses move AI projects from experimentation into production. With Accenture doubling down on its AI ambitions, here’s a closer look at the company.
About Accenture Stock
Headquartered in Dublin, Ireland, Accenture is a global professional services company that helps enterprises build digital capabilities and apply AI across their operations. Its strategy focuses on serving as a reinvention partner for clients, supporting the broader adoption of AI, and building an AI-enabled workforce. The company has approximately 814,000 employees and combines proprietary assets and platforms with industry and process expertise and relationships across its ecosystem to provide end-to-end solutions.
Through its Reinvention Services, Accenture operates across Cybersecurity, Digital Core, Finance, Industry and Enterprise, Song, Supply Chain and Engineering, and Talent, with additional capabilities in AI and Data, Industry and Process, and Technology. Today, Accenture serves approximately 9,000 clients across industries and generated approximately $74 billion in revenue in fiscal 2026. With a market capitalization of roughly $127.50 billion, Accenture’s 2026 journey has been anything but smooth.
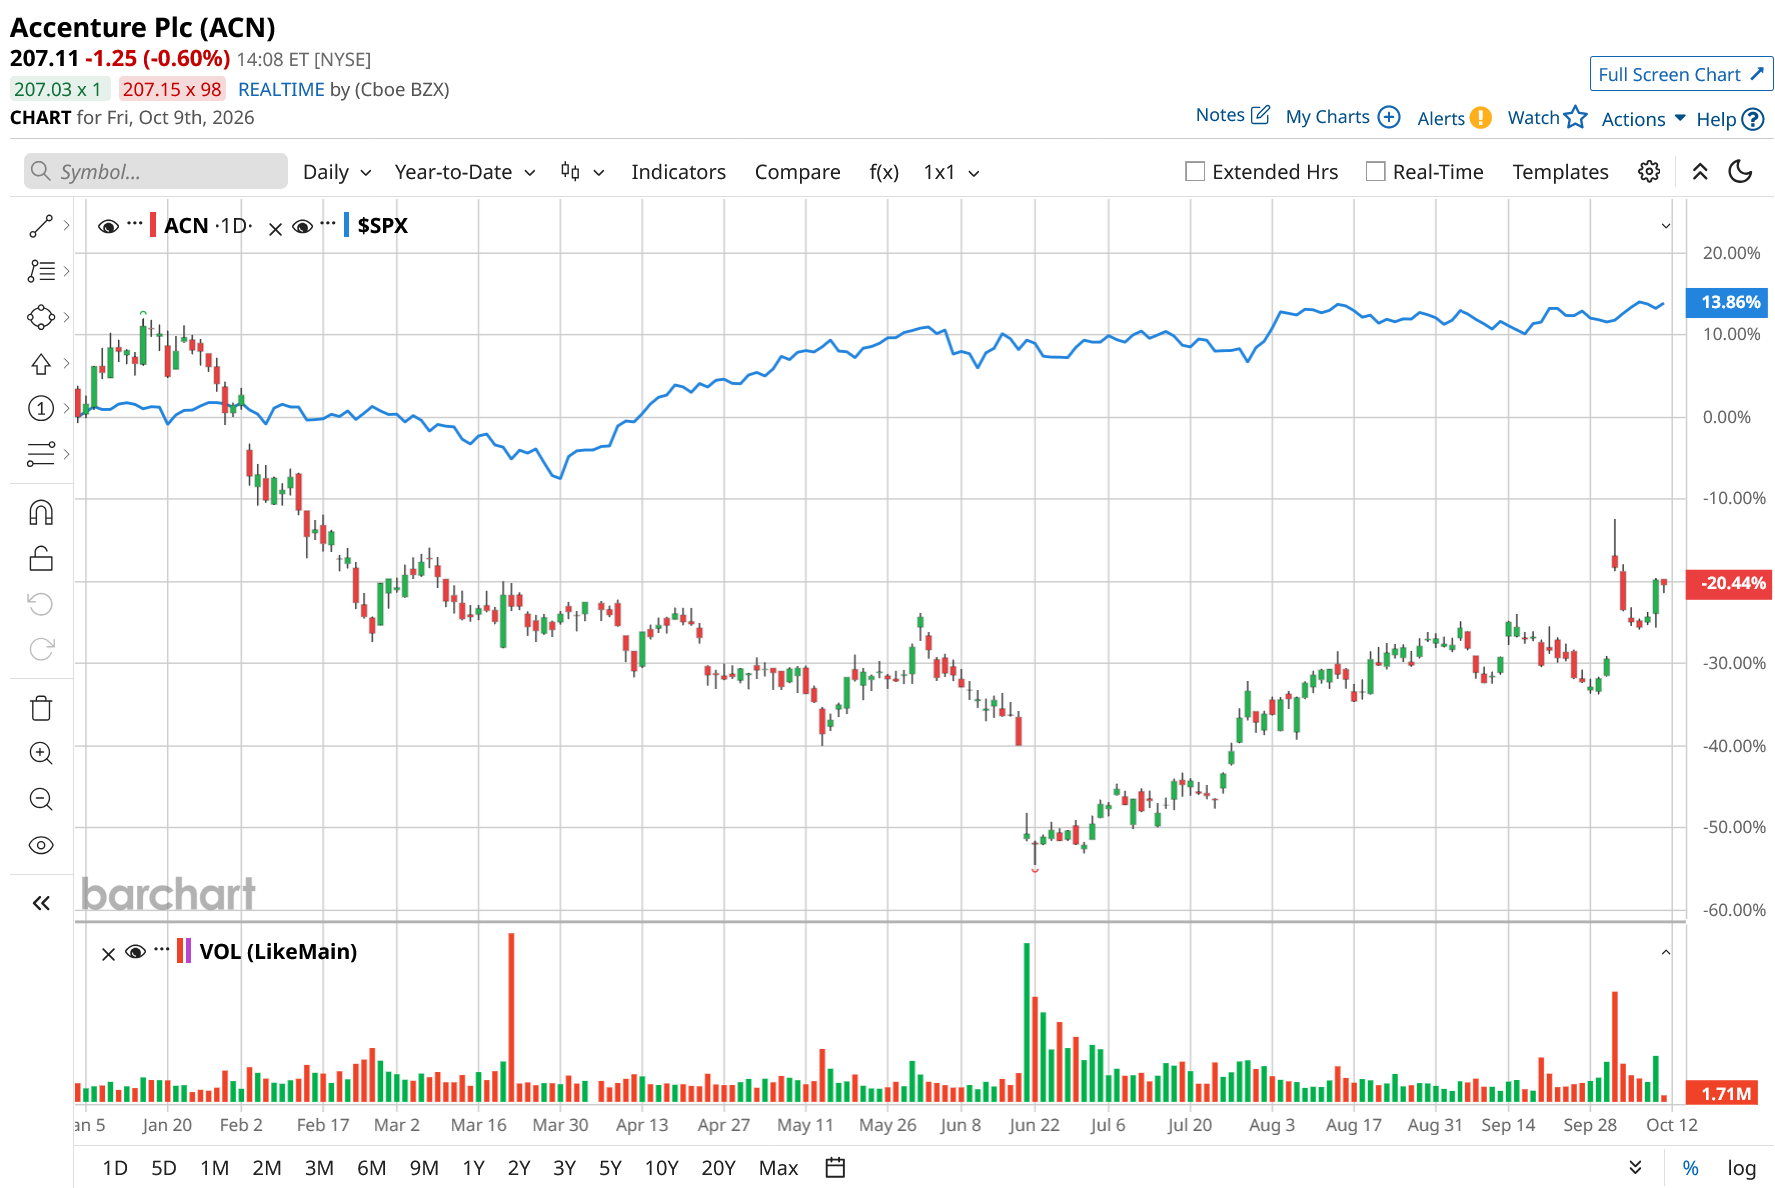
The IT consulting giant has spent much of the year under pressure as concerns over AI-led disruption weighed heavily on the sector. Accenture was caught in that broader selloff, with ACN stock down nearly 23% so far in 2026, sharply underperforming the broader S&P 500 Index ($SPX), which has gained 14% over the same period. However, those AI-related concerns have eased considerably following Accenture’s fiscal 2026 fourth-quarter earnings report earlier this month.
A stronger-than-anticipated annual revenue growth forecast highlighted robust demand from companies turning to external technology partners to automate complex tasks and accelerate AI adoption, helping send the beaten-down stock higher. The turnaround has been notable. Over the past three months, Accenture shares have surged 49%, while the stock is up 18% over the past month, outperforming the broader market during both periods.
Inside Accenture’s Q4 Earnings Report
Accenture pulled back the curtain on its fiscal 2026 fourth-quarter earnings on Oct. 1, and the results gave investors plenty to cheer about. The consulting giant beat Wall Street’s top- and bottom-line expectations, sending ACN shares soaring nearly 15.7% in the same trading session. For the final quarter of fiscal 2026, revenue came in at $18.68 billion, up 6% in U.S. dollars and 7% in local currency, comfortably ahead of Wall Street’s $18.02 billion estimate.
Diluted earnings per share jumped 46% year-over-year (YoY) to $3.29, topping the consensus estimate of $3.19 and pointing to continued operational efficiency. Growth was broad-based across the business, spanning all geographic regions and major industry groups. Both consulting and managed services posted healthy gains, with consulting revenue rising 6% in U.S. dollars to $9.28 billion, while managed services revenue climbed 7% to $9.40 billion.
By industry, Communications, Media & Technology led the pack with 10% growth in U.S. dollars, followed by Health & Public Service at 8%, highlighting continued enterprise demand for digital-core modernization and cloud transformations. Accenture’s bookings provided another strong signal. Fourth-quarter new bookings reached an impressive $22.17 billion, translating into a book-to-bill ratio of 1.2. Managed services bookings hit a record $12.77 billion, while 141 clients booked more than $100 million each.
Profitability also remained a bright spot, reflecting tighter cost discipline and expanding margins. GAAP operating income climbed to $2.86 billion, while reported operating margin expanded by 370 basis points to 15.3%. Free cash flow reached $2.8 billion in the quarter and $11.6 billion for the full fiscal year, giving Accenture ample firepower to return capital to shareholders.
The company returned a record $11.5 billion through share repurchases and dividends during fiscal 2026, up 38% YoY, including $2.3 billion in the fourth quarter alone. Looking ahead, management struck an upbeat tone with its fiscal 2027 outlook. Accenture expects full-year revenue growth of 3% to 6% in local currency, while GAAP diluted EPS is projected at $14.39 to $14.81, representing growth of 6% to 9%. Adjusted EPS is expected to increase 3% to 6%. The company also plans to return at least $9.5 billion in cash to shareholders during fiscal 2027.
What Do Analysts Think About ACN Stock?
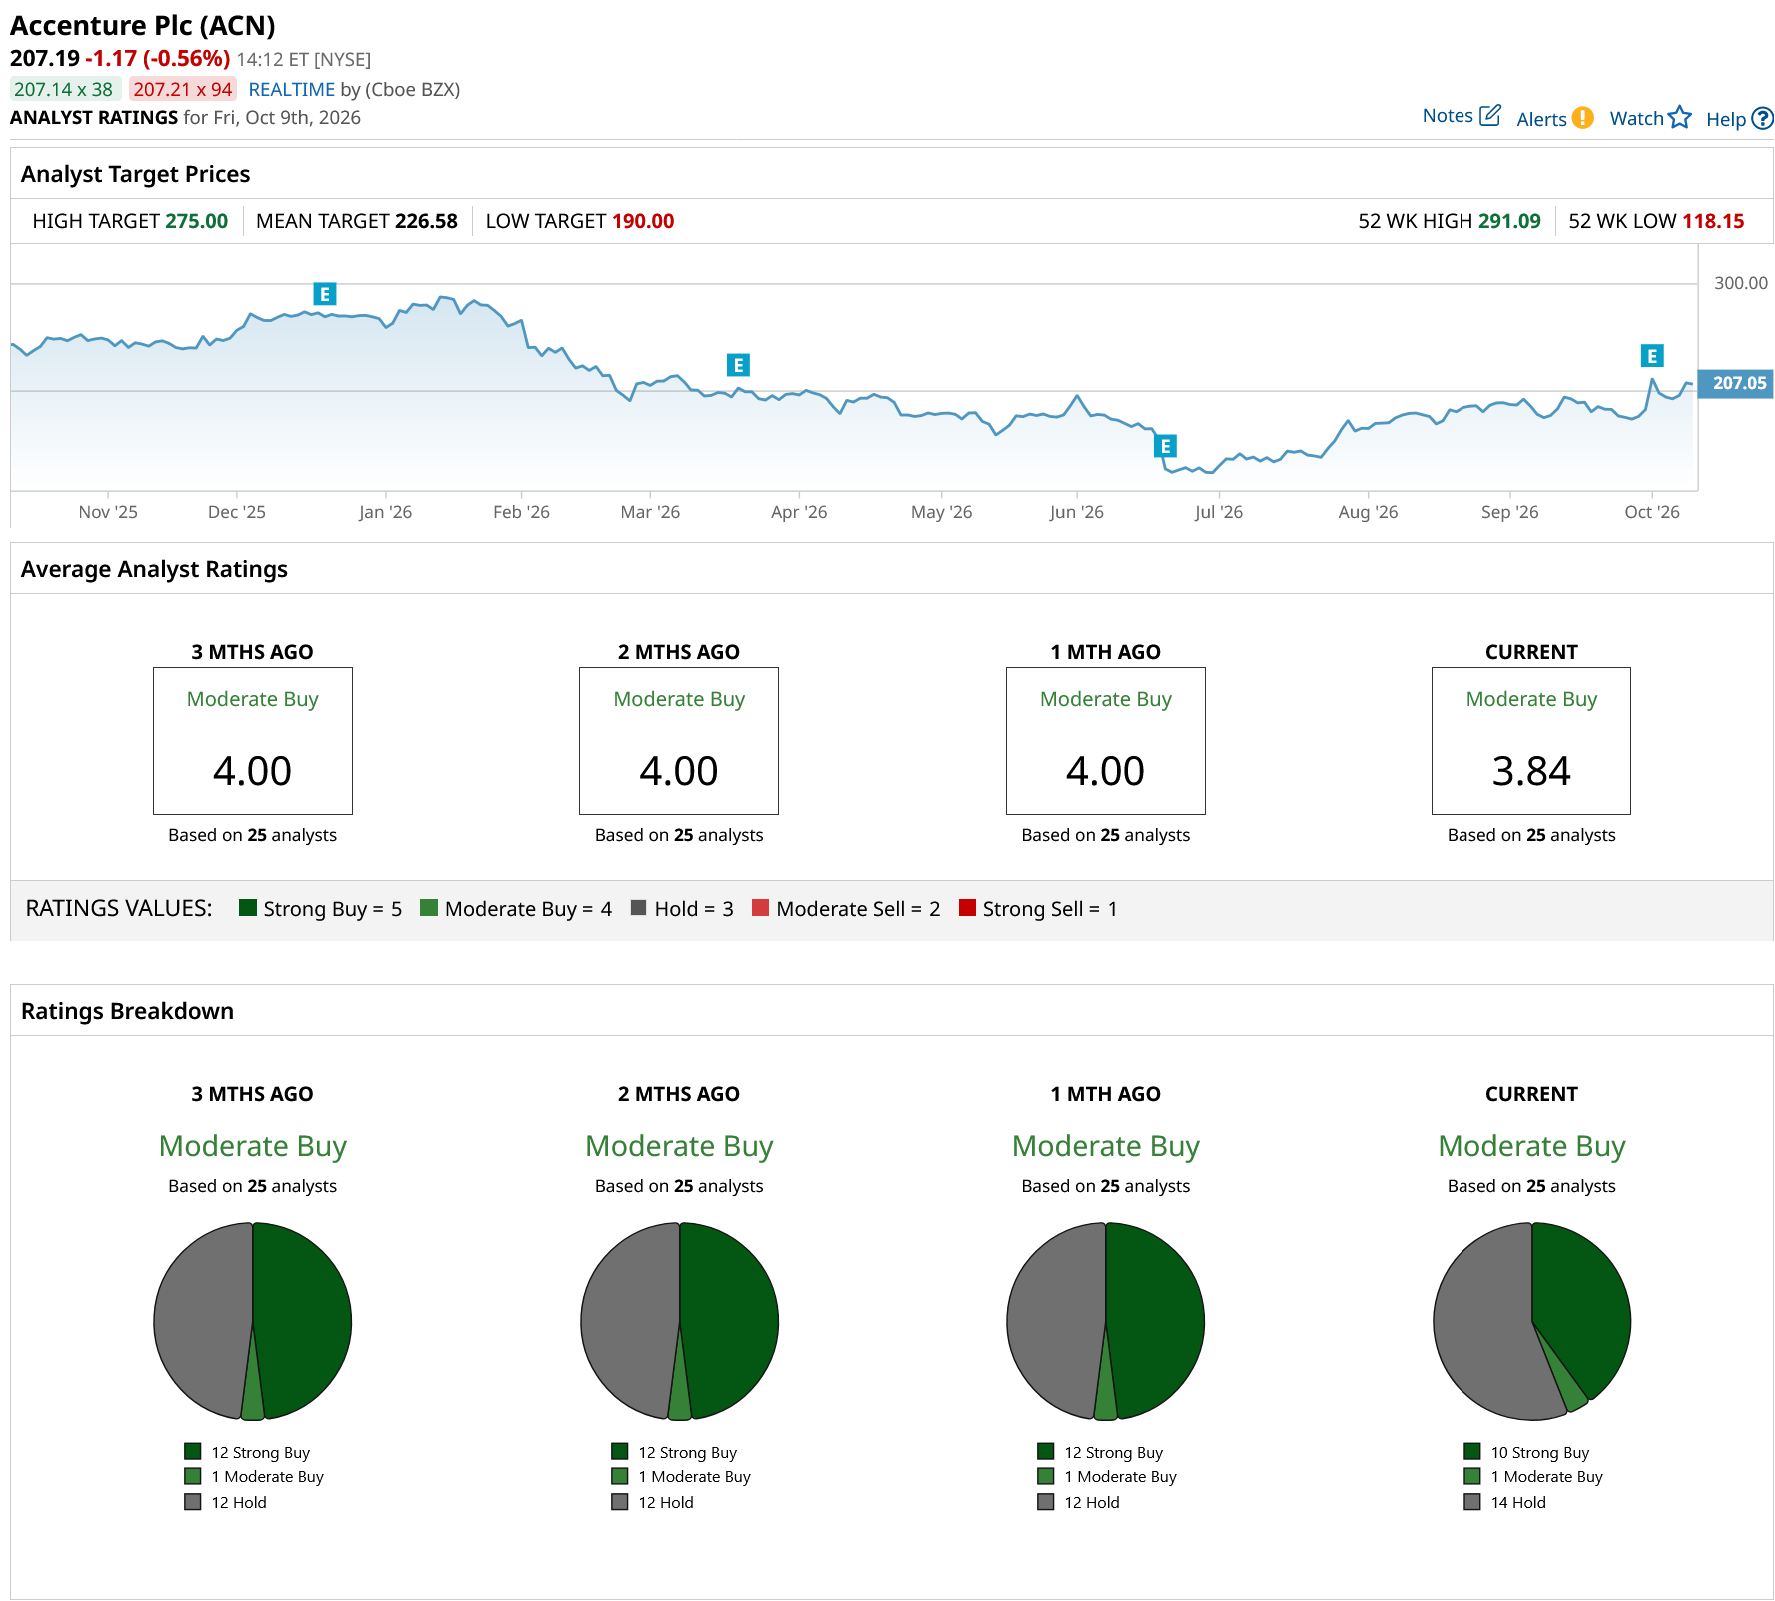
Wall Street remains constructive on ACN, with the stock carrying a consensus “Moderate Buy” rating. Among the 25 analysts covering the company, 10 recommend a “Strong Buy,” one has a “Moderate Buy” rating, and 14 have a “Hold” stance. The average price target of $226.58 points to roughly 9% upside from current levels, while the Street-high target of $275 indicates potential gains of as much as 33%.
On the date of publication, Anushka Mukherji did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.